Emerging Proteins in Aotearoa New Zealand: What will it take for the sector to thrive? - FoodHQ
←
→
Page content transcription
If your browser does not render page correctly, please read the page content below
April 2021

Emerging Proteins in Aotearoa New Zealand:
What will it take for the sector to thrive?

                                      What will it take for the sector to thrive?   1
AT A GLANCE

              This report summarises key observations and opportunities arising from discussions
              with 185 people from throughout the emerging proteins sector. It concludes with some
              recommendations for what is required for this sector to thrive, and some principles upon
              which we believe activity in this sector should be based.
              If we are to succeed in this increasingly competitive space, we need to do more and do it
              faster. We need to remove barriers, increase national and international collaboration, and be
              prepared to invest in world-class talent and infrastructure.
              This report is not intended to be the final answer. We hope it will spark further constructive
              discussions on how we can more rapidly develop a thriving emerging proteins sector as part
              of our future food production systems.

              Observations
              1. There is significant and diverse activity in      6.   We must understand our target consumers
                 emerging proteins throughout NZ, with the              and what products they want, and ensure
                 current focus being on plant-based foods.              these products are visible and accessible.
              2. ‘Plant-based foods’ can be divided into two       7.   The emerging proteins sector is seen as a
                 categories – analogues and whole-plant foods           potential solution for farmers and growers
                 - with different implications.                         and as an opportunity to food producers. It is
              3. “Plant-based” is often associated with healthy,        vital they explore the possibilities together.
                 natural and sustainable by consumers.             8.   We cannot rely on NZ provenance alone.
              4. Developing emerging proteins is about             9.   Currently, NZ law is restricting the development
                 portfolio diversification, not replacing all           of some emerging proteins sectors.
                 traditional agricultural systems and products.
              5. Business models include adding value to
                 imported raw materials or producing one’s
                 own raw materials. We can also develop
                 new ones.

              Opportunities
              1.   NZ could develop a plant-protein ingredients    4. Diversity of the sector could be a real
                   sector, but this is complex and requires           strength, but there is currently limited
                   careful consideration and significant capital      Māori participation at the food end of
                   investment.                                        the value-chain.
              2.   The emerging proteins sector could also         5. Investment in talent and infrastructure
                   be used to accelerate our move to a more           will fast-track emerging proteins sector
                   circular food production system.                   development.
              3.   Developing approaches that reduce
                   duplication and support collaboration will
                   deliver better outcomes for NZ from this
                   sector and others.

2   Emerging proteins in Aotearoa New Zealand
Recommendations
1.   Take a NZ-Inc, whole-of-value-chain                  f.   Review regulations around emerging
     approach to a suite of initiatives:                       proteins and compliance pathways for
                                                               new products.
     a.   Identify commercial or near-to
                                                    2. Formalise and fund a collaborative
          commercial sectors and form
                                                       independent national network to coordinate
          collaborative syndicates to progress
                                                       delivery of initiatives and bring cohesion
          pre-competitive projects in areas such
                                                       to the discussion. This would involve
          as R&D, consumer and market insights,
                                                       industry, research providers, venture capital,
          regulatory framework development,
                                                       government and other interested parties
          infrastructure improvements etc.
                                                       in the wider emerging proteins ecosystem.
     b.   Determine where investment should            This network will not lead all the initiatives
          be made in scale-up infrastructure to        described in recommendation #1 but will
          reduce commercialisation barriers.           provide crucial facilitation and coordination
     c.   Explore how we can market NZ                 to the collective effort.
          emerging proteins foods, leveraging the   3. Enable a single point of contact and
          brand value of NZ traditional proteins       integrated response from government for
          and utilising consumer and market            emerging proteins topics by establishing a
          insights from export markets.                cross-government working group involving
     d.   Establish a talent attraction programme      departments such as MPI, MBIE, NZTE,
          for R&D and innovation experts in            Callaghan Innovation, MFAT, MOE and
          key areas, complemented with a               others interested in this sector.
          multi-disciplinary talent development     4. Develop and implement a New Zealand
          programme that builds local capability       strategy for emerging proteins aligned with
          and capacity.                                potential areas of competitive advantage,
     e.   Foster an entrepreneurial ecosystem          leveraging the networks and information
          around emerging proteins.                    arising from 1-3 above.

Principles
Our Recommendations are underpinned by              3. Māori economy – enable Māori businesses
the following Principles to deliver long-term          to capitalise on the opportunities presented
sustainability and benefit to the country:             by the sector, particularly value-capturing
                                                       and higher returning opportunities.
1.   Circular economy – the sector should be
     developed in alignment with the principles     4. Technology – the sector strategy must
     of circular food production systems               explore relevant technologies and lead the
                                                       discussion on their applicability in the NZ
2.   Integrated value chain – a whole-of-
                                                       context. This includes a national discussion
     value-chain approach integrating on-farm
                                                       on genetic modification and the facilitation
     diversification opportunities with knowledge
                                                       of understanding that ‘GM’ is a suite of
     and expertise on food processing and
                                                       technologies.
     consumer insights.

                                                         What will it take for the sector to thrive?   3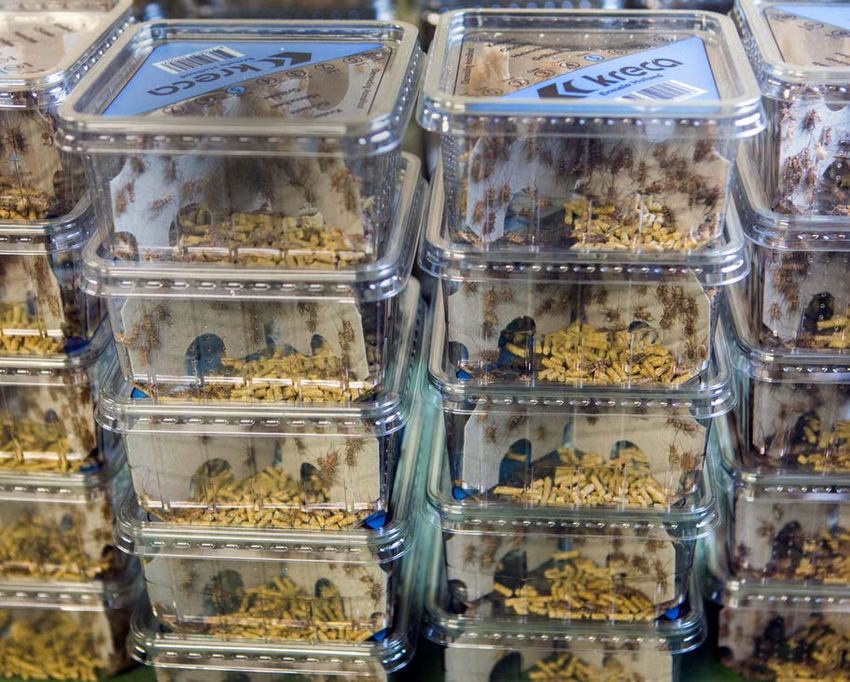
4 Emerging proteins in Aotearoa New Zealand
CONTENTS

 AT A GLANCE                                         2

 INTRODUCTION                                        6

 OBSERVATIONS                                        8

 OPPORTUNITIES                                     34

 RECOMMENDATIONS                                   47

 PRINCIPLES                                        48

 APPENDIX 1.                                       50
 CONTRIBUTORS TO THE
 REPORT

 APPENDIX 2.                                       53
 NZ EMERGING PROTEINS
 RESEARCH PROJECTS

                        What will it take for the sector to thrive?   5
INTRODUCTION

             In September 2019, FoodHQ Business Development Manager, Amos Palfreyman, was
             seconded to Foodvalley NL (FV), a FoodHQ Strategic Partner in Wageningen, the
             Netherlands. While there, he collaborated with FV to compile an Innovation Scan
             summarising some of the more visible activity in emerging proteins in New Zealand and
             the Netherlands. This was released in March 2020¹.
             The Innovation Scan determined that while there was some activity happening in NZ,
             the Dutch emerging proteins sector was significantly more organised, better resourced,
             and more firms were operating at a larger scale. In recognition of the need for more
             collaboration within this developing sector in NZ, FoodHQ subsequently launched a
             virtual network: Emerging Proteins NZ (EPNZ, www.emergingproteins.co.nz). The primary
             focus of this network was to accelerate the development of a NZ emerging proteins
             sector through the sharing of knowledge and establishment of connections in order to
             capture a share of the rapidly growing international market.
             Initial engagement with EPNZ members and the wider agrifood ecosystem indicated
             a need to gain a better understanding of what is currently going on in NZ, as much of
             the activity in this space is happening under the general radar. It also identified that the
             challenges and barriers to the development of the sector and the opportunities for the
             individual NZ firms that seek to operate within it, need to be further explored.
             This led to the launch of the current project, “Understanding NZ’s emerging protein
             sector,” jointly funded by FoodHQ and AGMARDT.
             It is important to note that this has developed into more than a conversation about
             protein, although emerging proteins remains a convenient short-cut for the broader
             category. It is really a conversation about a wide range of foods and ingredients that add
             diversity to our production systems and diets, and which are responding to significant
             global drivers.

             ¹ Reference to joint Alt Proteins scan, March 2020.

6   Emerging proteins in Aotearoa New Zealand
Project process and scope                           Wellington became a series of individual
                                                    interviews due to the numbers and availability
This project captures a snapshot of the NZ          of participants. All such discussions were held
emerging proteins sector. It is based on a large    under Chatham House rules.
number of conversations that occurred between
late 2019-early 2021 as part of various FoodHQ      Overall, 185 people provided useful insights
and EPNZ activities, along with a series of         and perspectives that informed this report,
facilitated individual and group discussions held   either through their participation in structured
throughout NZ in Oct-Dec 2020.                      discussions or via more casual conversations
                                                    and exchanges of ideas.
Those who participated in these conversations
came from across the value chain, from those
involved in crop genetics through to engineering    Project outputs
design, food manufacture and food service.
They covered all sizes of business and stages       The primary output for this project is this report,
of involvement in the sector, and also included     which aims to summarise the key observations
representatives from the research community         and consistent themes arising from the various
and various government organisations.               conversations.
Participation in the formal discussions was         There were many more interesting and valuable
restricted to those already actively involved       ideas which people generously shared during
in emerging proteins or those actively              this project which are not specifically detailed
considering becoming involved. Individuals and      in this report, but which enriched our wider
organisations were identified through a range       understanding of the sector and the individual
of approaches, including the EPNZ Membership        experiences and challenges within it.
database, FoodHQ networks, and referrals from       Another less public outcome has been our
collaborating organisations and individuals         increased collective awareness of the numerous
including the New Zealand Food Innovation           individuals and businesses who are active in this
Network, B.linc and Callaghan Innovation. These     sector. Many participants have expressed how
discussions had a very general framework which      valuable it was to meet with others in their local
included questions around current and future        region who share similar interests and are having
activities, challenges and barriers, gaps and       similar challenges. Hopefully there will be more
opportunities within the wider emerging proteins    opportunities to further build and strengthen
sector. This enabled free-flowing and wide-         these local networks.
ranging discussions which led to observations
                                                    A list of people who contributed ideas and
and comments on topics that may not have been
                                                    insights that we drew upon during this project is
forthcoming in a more tightly structured session.
                                                    given in Appendix 1. We would like to once again
There were 13 facilitated discussions (each         acknowledge their input. Thank you.
2.5-3hrs in duration), held across the following
                                                    We hope this report will stimulate further
locations: Whangarei, Auckland (3 sessions),
                                                    discussions around how we can individually
Hamilton, Gisborne, Napier, Greytown,
                                                    and collectively seek to advance the emerging
Palmerston North, Nelson, Christchurch, Timaru
                                                    proteins sector.
and Dunedin. These were complemented by
additional individual interviews with those who
were unable to attend group sessions. Facilitated
discussions planned for New Plymouth and

                                                      What will it take for the sector to thrive?      7
OBSERVATIONS

              1. There is significant and diverse activity in emerging proteins throughout
              New Zealand, with the current focus being on plant-based foods.

              There are a number of individuals and                 • Biotechnology includes fermentation of
              organisations throughout NZ actively working in         microbes who have been genetically modified
              the emerging proteins space. There are growers          to produce molecules similar or identical to
              who are experimenting with new (and some old)           those from animals, cell-culture techniques
              crops, manufacturers who have expanded their            where stem cells are used to produce meat
              traditional ranges to include vegan products, new       or milk, and other genetic modification-based
              businesses being built from the principles of sole      techniques such as the genetic modification
              or primary focus on emerging protein sources,           to enable plants to express animal proteins.
              and researchers working along the entire value          These all involved genetic modification and
              chain seeking to open new opportunities. Those          as such any research in these areas is tightly
              involved are almost universally passionate about        restricted under current NZ regulations.
              the potential of the sector, while also almost        There are currently no cell culture or fermented
              universally identifying significant challenges in     protein food products made in NZ, and there are
              achieving that potential. These are discussed in      only a handful of small-scale companies who have
              more detail in the coming sections.                   insect-based foods for human consumption. There
              For simplification within this document and in the    is no commercial plant-protein ingredients sector
              broader discussion, we have divided the emerging      in NZ at present. Thus, the main area of current
              proteins category into subcategories of plant,        activity is plant-based foods, and it seems likely
              non-traditional animal proteins and biotechnology.    that this will remain the key area of focus for NZ
              • Plant is the most well developed category.          producers for at least the short to medium term.
                Although not strictly correct from a                Although there is much interest and activity in
                taxonomy perspective, we have included              emerging proteins within NZ, it is important to put
                fungi (mushrooms) and algae/seaweeds.               this into an international context. Many of the
                The development of the algae/seaweeds               more advanced economies we tend to compare
                sector is much less advanced than much of           ourselves with - the Netherlands, Singapore, Israel
                the other more common plants, but is similar        - are investing significantly more, moving much
                to the development of the more novel plant          more rapidly, and doing it at scale. They have
                approaches, such as grass protein ingredients.      deep engagement between industry, government
              • Non-traditional animal proteins are insects and     (especially regulators) and research providers,
                other developing opportunities from animal          and ambitious targets for the role that emerging
                derived products such as wool. There is a lot       proteins will play in their future agri-food sectors.
                of diversity within insects, including a wide       At the moment, NZ is being left behind our peers
                variety of different species, from black soldier    within this increasingly competitive sector.
                fly to crickets, locusts to mealworms; as well as
                the various developmental stages of these (i.e.
                larva, pupa, adult).

8   Emerging proteins in Aotearoa New Zealand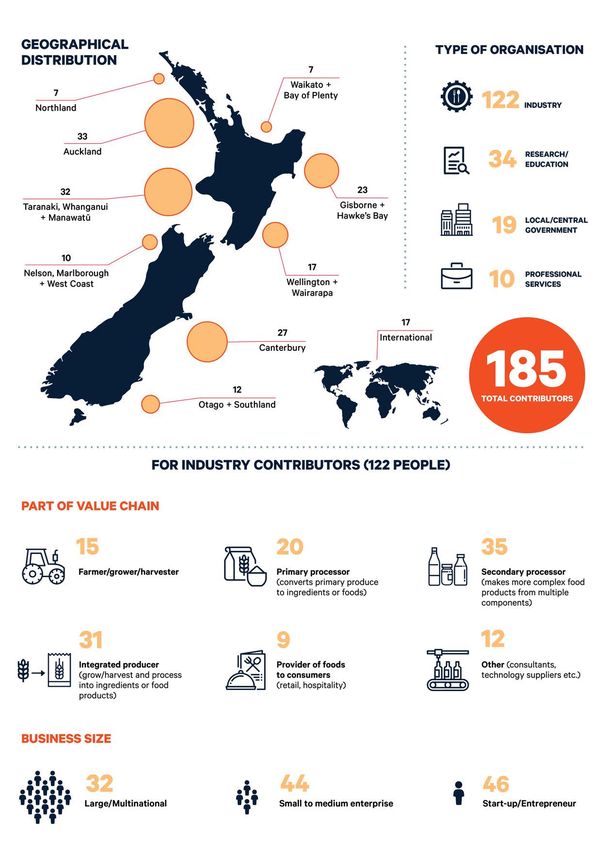
What will it take for the sector to thrive? 9
Vegetarian-friendly animal proteins – no longer an oxymoron.

              Although the focus in emerging proteins is often    identical proteins. The particular amino acids
              on plant based or biotechnology approaches,         in the coil link, like teeth in a zipper, to lock the
              there are also interesting animal-sourced           structure in place. This structure is essential for
              proteins with significant market potential. NZ      the protein to perform its role, either in helping
              company Keraplast Technologies is leading the       skin cells make proteins or in keeping hair strong
              way in the commercialisation of keratin extracted   and flexible.
              from wool shorn from a sheep.                       Many keratin extraction or production
              Keratin is one of nature’s most important           technologies break up the proteins and damage
              cellular building blocks, giving the human body     the amino acids, and in doing so they lose the
              structure and order, and is fundamental in          important “teeth in the zipper” needed for the
              the development of healthy tissues, including       functional benefits.
              skin, hair and nails. It has some similarities to   Keraplast Technologies has developed and
              collagen, which has seen a huge surge in market     patented proprietary manufacturing and
              interest, with a number of successful collagen      processing technologies which gently extract
              products positioned as supporting general           fully bioactive keratin proteins from natural,
              health and beauty.                                  renewable sources (including wool). These
              The amino acids in keratins are linked in           proteins are then developed into a range of
              particular sequences that together like small       product solutions to support healthier hair
              bundles of rope, building strong protein            and skin, increased lean body mass, as well as
              networks. The same sequences are present in         advanced wound care.
              human skin and hair and so functional keratin
              proteins can be considered skin and hair

10   Emerging proteins in Aotearoa New Zealand
2. ‘Plant-based foods’ can be divided into two different categories -
analogues and whole-plant foods - with different implications.
There are two distinct categories of foods that micronutrients). In general, these products are
are generally grouped together when referring considered less ‘high tech’ than meat analogues
to ‘plant-based’ products. However, these have and it would be difficult to formally protect
important differences that need to be considered through patents, but there is significant expertise
when looking at options for NZ within the sector. and skill in the development of the formulation
The first category is the one that often gets the and selection of processing parameters to obtain
most publicity and investment: meat and dairy a really great product. There can be a lot of
analogues. These seek to mimic their animal- natural variability in whole minimally-processed
derived counterparts in terms of appearance, ingredients, which can require significant batch-
sensory characteristics, and how they are to-batch adjustments in order to achieve the
prepared or used. In fact, the closer they are to desired final product.
‘real’ meat and dairy, the more successful they Overall, it seems that whole-plant foods have
are considered to be. Meat analogues tend to advantages in terms of their environmental
use highly refined ingredients and processing footprint, as they primarily use minimally-
technologies such as extrusion, although some processed ingredients which are able to be
of the less structured products (such as mince grown locally and generally require less capital
or sausages) can include less refined ingredients. and expertise-intensive processing equipment.
Dairy analogues are usually prepared from a plant But they do not usually provide protectable
material using a combination of physical and intellectual property. Meat analogues have much
sometimes enzymatic processing steps along with larger environmental footprints, requiring highly
the addition of various oils and micronutrients.
These products are heavily reliant on technology
and there are a large number of different patents
filed on various aspects ranging from ingredients
to processing approaches. Once the formulation
and processing parameters have been finalised, it
is usually possible to produce consistent product
because of the limited variation in raw materials.
The second category is whole-plant foods that
are principally based on whole vegetables, grains,
and other non-animal components (including
mushrooms, which are technically fungi and not
plants). These are usually formed into products
that ‘celebrate’ their plant origins and do not
attempt to look or taste like meat. These are often
lower in protein, although some have had more
concentrated forms of protein (such as plant
protein powders) added to boost protein levels,
but come with other nutritional value courtesy of
the specific plant components used (especially
fibre, complex carbohydrates, and various
What will it take for the sector to thrive? 11refined (and currently imported – see section 9) This fails to recognise the important differences
ingredients and expensive specialist equipment. in the products and their consumers, and the
But there is more opportunity for protectable subsequent implications for the development of
and licensable intellectual property. Different large-scale production in NZ for either product
consumers seem to prefer the different categories, category.
with whole-plant food consumers often talking It is worth noting a difference between meat
disparagingly about why people who choose and dairy analogues in this case - NZ currently
not to eat animal product apparently want foods does not have commercial scale manufacturing
that are copies of animal product, and analogue infrastructure for plant-based milks, with all
consumers believing that a good mimic can make commercial scale plant-based milks being
it so much easier to not miss the real thing. imported. There is milk from NZ oats available, but
NZ companies have successfully commercialised the oats have been shipped from NZ to Europe for
products in both these categories, and there are processing into milk which is then shipped back.
more companies with both types of products However, this is due to change with construction
under development. However, if NZ is to develop of a new oat milk extraction plant planned in
scale within the meat analogue space, it will Southland. It appears that this plant will be solely
either need to develop a domestic plant protein focused on oat milk, and so all other plant-based
ingredients industry or be dependent on a ‘trader’ milks will continue to be imported. There is no
model similar to that of the Netherlands. exporting of NZ-produced or NZ-grown plant-
There is no data that we are aware of that based milks at this stage, but it is anticipated that
compares the relative local and export market there will be exports of NZ oat milk once the new
sizes and values for these two categories, instead plant is up and running.
grouping them together as plant-based foods.
12 Emerging proteins in Aotearoa New Zealand“Oats are very cool right now.” Henry Hawkins, Harraway & Sons CEO
Harroways and other key players in the oat
industry want to capitalise on the potential of
L5 oat milk. NZ’s reputation for quality food and
beverage, the established local oat industry and
a proprietary cultivar which produces a more
desirable product are all important components
required for NZ to succeed internationally.
However, the key missing piece of the puzzle is
the commercial scale processing infrastructure
to produce the milk from the oats.
The oat milk currently sold in NZ is
produced overseas, with the milk from
NZ oats also having been produced in
The increasing market demand for milk Europe from NZ oats that have been
alternatives has led to an explosion of plant-based shipped over to the processing facility.
milks. Among the more common almond and
NZ Functional Foods has been established by
soy-based beverages, there have been multiple
Southland’s economic development agency,
oat-based milk products enter the market.
Great South, to investigate the high value, health
Participants in the various discussions expressed and wellness, export opportunities provided
a level of skepticism around whether NZ could by oats. They have now secured cornerstone
feasibly compete in the international alternative investment for a high-tech oat processing
milks sector, either with the growing of the factory from Sir Stephen Tindall’s start-up
raw materials or the production of the milks backer, K1W1, and are working on securing
themselves. However, unlike soy or almonds, further capital. They aim to start construction
oats have been grown at scale in New Zealand of the plant near Invercargill within the next 18
for over 150 years. This means there is already months, and hope to kick off production a year
existing expertise, infrastructure and logistics from then. L5 oat milk will be the first product
for their growth, harvest, storage and initial launched, targeting both local and export
processing steps, concentrated in Southland. markets. The plant will be available to contract
In addition, an eight-year breeding programme manufacture oat milks on behalf of interested
by the Oat Improvement Group, a collaboration food companies, and the intention is to expand
between research provider Plant Research the processing capability to other oat product
New Zealand Ltd, Southland Oat Growers and types as well.
Harraways has led to the development of a So will NZ be able to play in the international
proprietary oat cultivar, Southern Gold L5. L5 is oat milk market? Well, it has the willingness,
a plump oat with a large groat [kernel] that has the sustainable growing conditions, the
slightly higher yields than existing varieties, but established oat industry, a proprietary cultivar
its main attraction is the overall oat quality, with with advantages over other oats, experience in
milk from L5 appearing to have advantages over food product development, and very soon the
oat milks from other cultivars. commercial scale processing infrastructure.
Watch this space!
What will it take for the sector to thrive? 133. “Plant-based” is often associated with healthy, natural and
sustainable by consumers.
The international consumer trends for ‘natural’, ability to achieve a nutritionally adequate diet
‘healthy’ and ‘sustainable’ food products have purely from plant sources, even for those nutrients
led to increasing demands for more minimally- found at lower levels or with lower bioavailability
processed whole foods, while still maintaining in plants.
expectations around convenience, shelf-life Similarly, it has been noted by Wageningen
and taste. Interestingly enough, many of these University and Research that while minimally
consumers are also purchasing more plant-based processed plant-based foods generally score
foods, including meat analogues. This is despite pretty well in environmental impact assessments,
current plant-based meat analogue products the more processing involved the worse the score,
tending to be highly processed, made from ultra- with ultra-processed products utilising highly
refined ingredients with a range of additives and refined plant-based ingredients being very carbon
processing aids, and in some cases (Impossible intensive. Yet, there seems to be little difference in
Burger) relying on genetic modification. consumer perception of the product sustainability
It is commonly noted that plant-based alternatives at this stage.
to meat and dairy are not nutritionally equal, both It is possible that consumers may become more
in terms of macronutrient content (especially sophisticated in their understanding of these
protein levels) and micronutrients (especially aspects and that this may translate to changes
iron and zinc). However, participants in the in their expectations for the next generation of
discussions observed that they don’t think plant-based products. However, this is likely
that most flexitarian or vegan consumers are to require significant improvements in how
concerned about nutritional equivalency, and information on aspects such as life cycle analysis
that messaging related to this does not seem and nutritional implications are communicated
to be having any impact. Flexitarians appear to to consumers. Right now, there appears limited
generally feel comfortable that their overall diet interest from most consumers in delving into
will be nutritionally adequate, with valuable but these areas, and they feel comfortable with their
different nutritional contributions coming from simplistic assumptions that anything plant-based
their animal, and their plant-based foods. Vegans is healthy and sustainable by default.
are seemingly similarly comfortable with their
14 Emerging proteins in Aotearoa New ZealandConsumer perception becoming their reality.
In Ponsonby Countdown dairy-free ice creams see the “healthier ice cream” signage above
have been located under a sign that reads dairy-free going to assume that this is based
“healthier ice cream”. When questioned about on a credible nutritional assessment rather
this the Manager replied that he is responsible than simply a reflection of the language of
for sign-posting the products so that consumers other consumers?
can find them, and that this was the language Food Standards Australia New Zealand
that consumers used when describing the dairy- (FSANZ) has restrictions around when the
free ice cream options. This is despite many word ‘healthy’ can be used on foods, and the
dairy-free ice creams (especially those based on Commerce Commission regulates comparative
coconut) being comparable with dairy ice creams claims (i.e. healthier than what and by how
in terms of nutritional composition. much?). However, it is unclear whether there
There is an interesting chicken-and-egg are any specific requirements around signage
situation developing here: Are consumers who in a retail environment.
What will it take for the sector to thrive? 15Protein (and nutrition more generally) not front of mind for all consumers.
Protein has been widely touted as a key focus A recent FoodHQ scan of Instagram posts by
for local and international consumers, with international plant-based brands found that
references made to the increasing popularity of only 16 out of 100 contained any mention of
terms such as keto and low-carb on social media protein within the posts or visible on packaging
and in product launches. However, this does not shown within their Instagram images. This
seem to be carrying over into all areas. suggests that these companies do not feel that
Many plant-based foods and beverages are protein content is of particular interest to their
significantly lower in protein than their meat consumers. Health related claims were also made
or dairy counterparts, and the meat and dairy on relatively few products (28% of US brands, 2%
sectors have been advocating the superior of brands from Europe; possibly reflecting either
nutrition of their products for some time. Yet the greater interest in health of US consumers or
increasing numbers of consumers are choosing perhaps the more relaxed regulatory environment
to include plant-based products in their diets. in the US for these sorts of claims). Instead, the
most consistent theme in the Instagram posts
It has been observed that nutritional content was an emphasis on how great the product tasted
claims do not appear to resonate with many (72% of US brands, 54% of brands from Europe
consumers, and that communication about the or the UK). This is in line with the oft repeated
health and wellness benefits (that may arise from phrase in the food industry that ‘Taste is King’.
the nutritional content) may be more engaging. It seems that this is the same for both traditional
These benefit claims are more complex and and emerging protein products.
expensive to validate, and there are different
regulatory requirements for them in different
markets.
16 Emerging proteins in Aotearoa New ZealandWhat will it take for the sector to thrive? 17
4. Developing emerging proteins is about portfolio diversification,
              not replacing all traditional agricultural systems and products

                                                                       high-quality animal and emerging protein
                                                                       products. Holding this perspective requires a
                                                                       somewhat more nuanced view of both sides.
                                                                       The following table summarises some of the
                                                                       common statements in discussions and provides
                                                                       some alternative perspectives that are not
                                                                       necessarily mutually exclusive.
                                                                       There is work (much underway) to be done on
                                                                       both traditional and emerging protein production
                                                                       systems and value chains to ensure they are
                                                                       aligned with consumer demands and are
                                                                       environmentally and financially sustainable.
                                                                       Wageningen University and Research (WUR),
                                                                       an international thought-leader in circular food
                                                                       production, supports the presence of animals
                                                                       within sustainable food production systems. They
                                                                       have proposed redefining the role of animals as
                                                                       ‘protein converters’ rather than ‘protein sources’
              There were quite a few heated discussions around         to better reflect their consumption of protein
              the country regarding the future for NZ in both          (from crops, pasture or other sources) in order to
              traditional and emerging protein products.               produce the protein in their meat, milk or eggs.

              There are those who are adamant that a                   Traditional meat and dairy remain strong export
              successful future NZ must move completely away           sectors for NZ and demand for these products is
              from traditional animal agriculture; but there are       still growing rather than slowing. However, there
              also those who are equally adamant that NZ               is an increasingly broad range of possibilities for
              does not have a clear pathway to international           future food production being developed by some
              success in emerging proteins. In both cases, there       of the world’s smartest thinkers.
              were fairly strong lines of reasoning for why the        It doesn’t benefit our existing industry to deny the
              particular perspective was considered likely to be       potential for serious disruption, nor is it necessary
              true, usually built upon broad generalisations and       to abandon traditional proteins in order to take
              high-level observations.                                 advantage of emerging ones. The sooner this
              However, the majority of participants felt strongly      becomes an ‘and/both’ discussion rather than an
              that this was unlikely to be an ‘either/or’ situation,   ‘either/or,’ then the sooner we can work together
              at least for the foreseeable future. Instead, there is   to identify how NZ can best move forward.
              an opportunity for NZ to have a more diverse food
              production system that produces both sustainable

18   Emerging proteins in Aotearoa New Zealand
Common statements that Alternative perspectives that may also be true
may be true
People will always want to In addition to consuming some animal protein, many people
eat animal protein. will also choose to eat more plant, fungi, algae and eventually
insect-containing foods.
The most efficient and Animals can convert protein from feed not suitable for human
environmentally sustainable consumption (pasture, biomass remaining after crop harvesting,
food production system is by-products and waste from food processing, etc.) into protein that
purely plant-based. humans can consume. This role of protein conversion is a valuable
part of a circular food production system with minimal waste.
Most people won’t trust With time, many more people will be comfortable eating proteins
genetically modified or from fermentation and cell culture technologies – especially those
synthetic proteins. who are not connected to traditional production systems, such as
urban Asian consumers.
NZ will never grow NZ science and innovation, combined with deep consumer
plant-based proteins understanding and a genuinely sustainable NZ provenance story,
economically has the potential to enable the economically viable modest-scale
production of plants that can be converted into products that
discerning consumers will pay a premium for.
Regardless of what Although our seafood industry is not currently under as much
happens to our pastural pressure as pastoral agriculture, there are still many of the same
agriculture, we always have challenges. Climate change will affect our fisheries, both wild-catch
seafood and aquaculture. and farmed. Consumer concerns about the environmental impact
of fishing and microplastics in seafood will increase. Seafood
substitutes will become increasingly sophisticated and available.
NZ will always have an New technology and innovation (including the use of GM) will
advantage because of its allow other nations to produce foods without such plentiful natural
plentiful natural resources resources. They will get better at telling their stories, which may
and provenance. be based on natural resources and provenance or on technology
and innovation. Climate change will affect the feasibility and
outputs of our current food production systems and locations.
It is not cost-effective Land and water will become more highly valued, driving a focus on
for NZ to adopt capital- better utilisation. High-tech production systems will reduce in cost
intensive food production as the technology matures, and the increased certainty around
systems because land and quality and yield from these systems will become more attractive,
water is relatively cheap especially as climate change increases the frequency of extreme
and plentiful. weather events.
NZ always has and NZ could develop a significant ‘weightless’ export industry
always will be a food leveraging our food-related intellectual property and innovative
exporting nation. capital. This industry is starting from a relatively low base but has
the potential to grow exponentially as we attract more top talent
and investment.
What will it take for the sector to thrive? 195. There are various business models for emerging proteins, including
adding value to imported raw materials or producing one’s own raw
materials. We can also develop new ones.
The very successful Dutch food industry (the adopting successful approaches from the Dutch,
second largest food exporter in the world) but our distance from ingredient sources and our
is based upon a ‘trading model’ of importing export markets does put us in a different position.
ingredients, adding value through combining This approach would appear to be most likely
ingredients and processing, then exporting the to suit NZ foods where there is a significant
resulting food products. They have a natural proportion of NZ sourced ingredients, where
advantage due to their proximity both to the at least one of those ingredients is something
sources of the ingredients and large consumer particularly unique to NZ, or where there is
markets but they also invest in talent and sufficient consumer value in the product being
infrastructure related to food, and take full ‘made in NZ’. In other circumstances, it may
advantage of this model’s flexibility to rapidly be worth considering whether a more efficient
respond to changing consumer demands. (environmentally and financially) business model
It is common in the NZ food industry to import is presented for the products to be made closer
some of the ingredients used in foods for both our to the targeted market through a local contract
local and export markets, but it is less common for manufacturer or via some sort of partnership with
our exported foods to be predominately based on a local firm.
imported ingredients. There is a certain appeal in
20 Emerging proteins in Aotearoa New ZealandFor products dependent on the importation of become large players in the local and export
large volumes of ingredients, there is a risk in the markets. However, international experience
adoption of this import/process/export model has been that most brands with large market
around the increasing consumer awareness of the share have grown via start-ups or SMEs who
contribution of food production and distribution to have then partnered with, or been acquired by,
climate change. At the moment, consumers do not large companies. These big food companies can
appear to be aware of and/or concerned about this unlock the efficiencies of scale to enable rapid
for plant-based foods as there does seem to be a and cost-effective expansion that can make the
bit of a sustainability halo around them regardless products more widely available and accessible.
of the specific nature of their production. It seems likely that a successful NZ emerging
Another business model that is starting to be proteins industry will require a combination
more widely discussed in the NZ food sector of innovation and responsiveness from small
is that of the export of ‘weightless’ intellectual companies with the resources and involvement
property rather than our traditional physical food of large existing businesses. Many of NZ’s larger
products. We have the opportunity to use our food companies participated in the discussions
Kiwi ingenuity to develop new knowledge and for this project and have indicated varying
products within the emerging proteins space levels of interest in the sector ranging from
that can then be used to produce foods closer current active participation through to keeping
to either the primary raw materials or the target a watching brief. The challenge will be in finding
market. This requires careful partnerships and/ business models that successfully respect,
or licensing arrangements, but does open up the protect and leverage the respective strengths
opportunity for NZ to be earning income from our of the different companies. It also seems likely
food science expertise and innovation capability, that other market consolidation models such
without us necessarily having to use NZ resources as syndicates and cooperatives may have roles
to produce the products. to play, particularly to enable groups of growers
Irrespective of the business model, it will (at to achieve the scale and reliability of supply
some point) need to have scale in order to have required by larger food manufacturers.
impact. Start-ups and SME food businesses
have been very successful in sparking increasing
consumer interest in emerging proteins with the
development of new products either based on
what is available overseas or in some cases on
novel intellectual property. Small food businesses
can innovate fast, develop deep understanding
of their niche consumers and engender trust
through clear communication of and commitment
to their values. It is possible that some of these
businesses will be able to successfully scale and
What will it take for the sector to thrive? 216. We must understand our target consumers and what products they
want, and ensure these products are visible and accessible.
The international consumers of NZ’s food our products meet the needs of their target
products in the future will be knowledgeable, consumers. While the broader the target
conscious, tech savvy and data hungry, and in consumer the larger the potential market, it is rare
many cases they will be different from those to find products that large numbers of general
consumers the NZ food sector has previously consumers really connect with. More often, it is
served. This is exacerbated when we think about the more niche products that resonate strongly
the future consumers of NZ’s emerging protein with their consumers and inspire engagement and
products. These consumers are likely to also have loyalty. Given the very small scale of NZ’s food
expectations not just around the food product but production on the international market (even our
also its packaging, and, increasingly, the wider set dairy industry only produces 2% of the world’s
of values of the food producer. milk supply) and higher production costs, serving
Different discussion participants were targeting premium niches appears an attractive strategy.
different consumers in different markets with their Achieving this requires us to segment markets
products. In many instances, the target consumer and deeply understand sustainable consumer
group was fairly loosely defined, with participants niches (i.e. not just passing fads) so we can
seemingly relying on a very broad set of potential develop products tailored for them, making sure
consumers for their products. we recognise the different drivers for different
If we are to step outside our reliance on NZ consumers and align our products and marketing
provenance alone, it is very important that accordingly. This requires high quality, accessible,
Vegan vs. plant-based.
The language used to describe foods with no An example of this is provided by unsuccessful
animal products seems to be shifting. Not long Dunedin plant-based burger joint “Straight Up
ago these products would be simply classified Vegan”. Despite confidence around consumer
as ‘vegan’. However, the term ‘plant-based’ has trends, sales were slow, and it seemed it was
become increasingly visible in the past few years, viewed as a niche offering for animal free
especially with younger (more ‘hip’) consumers advocates combined with a perception that
and flexitarians. vegan food was lacking in flavour and required
While technically meaning pretty much the consumers to ‘give something up’. They
same thing, it seems that ‘plant-based’ is rebranded “Burger Plant”, and while the food did
generally perceived as being more inclusive and not change, business has boomed as a wider
accessible than ‘vegan’, with the latter having array of consumers are coming in expecting (and
become symbolic to many people of an extreme receiving) tasty food that just happens to be
position (both in terms of food and wider social based on plants.
stances) that does not resonate as well with
many new consumers.
22 Emerging proteins in Aotearoa New Zealandtailored and recent market and consumer insights. hybrid products (usually whole-food blends i.e.
This was identified by a number of participants beef and beetroot burger patties) that purport to
as being either unavailable for the categories/ offer the taste, texture and micronutrients of meat
markets they were focused on, or too expensive combined with the lower environmental footprint,
for them to access as SMEs or start-ups. reduced fat and higher fibre of plants - the best
Investment is also required to develop business of both worlds in a single food item. However, it
consumer and sensory science capability and has been claimed by some consumers that the
understanding to enable them to utilise such data. products are simply not as tasty as real meat and
Despite the reports of increasing numbers not as healthy or sustainable as plant products.
of people choosing to consume a vegan diet, It will be interesting to see whether adoption of
the vast majority of consumers still choose these products increases as consumers become
to eat both plant and animal products. Many more accustomed to them, or whether the
consumers throughout the world (especially in products become more sophisticated in terms
more developed markets) do report that they are of ingredients, processing technologies, or other
interested in new food choices and are currently means of improvement. Data shows that sensory
or potentially considering reducing or changing experience is key in driving repeat purchasing.
their consumption of traditional protein sources. The size of the flexitarian market also potentially
Other consumers (primarily in emerging markets) influences product branding. It has been assumed
still appear to consider it desirable to increase that vegans would prefer not to purchase vegan
the amount of animal protein foods in their diets, products from companies who also produce
although in some cases there may be a shift in animal-protein products. However, this would
what type of animal proteins they may prefer. seem to be less of a concern for flexitarians, and
At almost every session, there was an in fact there may be advantages in leveraging a
acknowledgement that the majority of current brand these consumers already know and trust.
potential consumers for NZ emerging proteins
food products are not in fact vegans, but are
people who are interested in a more varied
diet that includes new (at this stage primarily
plant-based) foods and ingredients whilst still
consuming some traditional meat and/or dairy.
These are sometimes referred to as ‘flexitarians’.
It seems most flexitarians who wish to increase
the proportion of plants in their diet are achieving
this by purchasing more plant-based foods (those
that in theory would be suitable for vegans).
But they do not necessarily require them to be
vegan and in principle ‘hybrid’ products that
contain both plant and animal components would
also help them achieve their dietary shifts. This
observation has led to the launch of a number of
What will it take for the sector to thrive? 23Where can consumers find emerging proteins at the supermarket?
Several participants commented on the However, other similar plant-based food
challenges for food producers and consumers products may be located among their chilled or
in ensuring that the full range of options is frozen meat-based or hybrid equivalents either
easily accessible and comparable. in a dedicated section (“lamb”, “beef”, “chicken”,
Different retailers (even different branches of “plant-based”) or else distributed alongside
the same retailer) are taking different approaches products of similar types (i.e. sausages, minces,
to where they display the ‘centre of plate’ crumbed nuggets).
emerging protein products. ‘Centre of plate’ Similarly, most plant-based milks are currently
products are those which a meal is commonly ambient stable and thus displayed in the middle
built around – traditionally the meat, now aisles in tetrapacks, while the chilled dairy milks
possibly the plant-based pattie or mince. are in a separate area usually around the edge of
Traditional vegan products such as tofu have the store.
usually been located in the chilled section Consumers can only buy something if they can
along from dairy products, deli meats, soups find it, and if they don’t even know something
and hummus. It is now common to find a larger exists then they won’t even think about where it
range of soy-based foods as well as a selection may be located.
of plant-based burgers or sausages from certain
brands on these shelves.
24 Emerging proteins in Aotearoa New ZealandWhy do some non-meat eaters want products that mimic meat?
A common question in discussions on emerging Meat analogues continue to be an area of
proteins refers to the increasing numbers of significant sales growth and investment in the
meat analogues or mimics on the market or in consumer foods market. There are increasingly
development. sophisticated options becoming available all the
Why, if someone does not want to eat meat, might time, and it seems likely that in future there will be
they want to eat something that looks, smells and more meat mimics that are much closer to the real
tastes like meat? thing.
One answer is simply that for many (but not all), Some Dutch colleagues have referred to meat
just because although they choose not to eat analogue products as a transition stage that
meat they still enjoy the meat eating experience. is necessary to help individual consumers and
Another answer is convenience – they know how indeed wider society move away from more
to structure a meal around meat products, and traditional eating patterns into new ones. They
it is easier to substitute out real meat for a meat believe that with time there will be less interest in
mimic. For some, it may be their first brave step meat mimics and instead consumers will embrace
towards plant based foods which look and taste more diverse plant-based foods formats and taste
familiar to ‘meat-like’ foods. profiles. Only time will tell!
What will it take for the sector to thrive? 257. The emerging proteins sector is seen as a potential solution for
farmers and growers and as an opportunity to food producers. It is
vital they explore the possibilities together.
The interest in the NZ emerging proteins sector content to be using existing approaches but
has a range of drivers. These generally fall into possibly adapting these by using new ingredients
two broad categories: or tailored for new niche consumer groups.
a. Offering a solution to farmers and growers These two categories are potentially, but not
seeking to future-proof their businesses necessarily, complementary. There is the potential
through enabling better financial and/or for the diversification of land use to align well
environmental performance; and with new consumer demands, but this does not
b. Providing an opportunity for new and existing happen by default. Ultimately, just because we
food producers to profitably capitalise on the can grow something doesn’t mean that we have
growing national and international consumer the right infrastructure to transform it into the
demand for new foods. right products, in the right format, for enough
consumers in a particular market to pay enough
For NZ arable farmers, the interest in for it to be a viable business. This is why it is
emerging proteins has sparked as they look absolutely vital a whole value chain approach is
for opportunities to shift to higher value crops taken to developing this sector in NZ.
that would be used for (higher value) human
At present, there is significant public and private
foods rather than animal feed. For many animal
sector investment into the evaluation of what
farmers, interest has been stimulated as part of
various tracts of land could successfully grow.
an evaluation of potential responses to tightening
However, there is much less investment to
environmental limitations (either now or expected
support the broader feasibility assessment that
in the future).
considers the consumer and market insights
In parallel, increasing awareness of the strong as well as the infrastructure availability. All
growth (albeit off a relatively low base) in sales these components must be looked at together
of foods incorporating emerging protein sources in an integrated fashion to efficiently identify
has led existing food producers to expand their opportunities that are likely to succeed.
product ranges and encouraged entrepreneurs to
Matching supply and demand in any new sector
establish new businesses focusing on this space.
is challenging, especially when crops take months
They feel that there are opportunities for products
to grow and potential sales of new products can
that better align with consumer expectations,
be difficult to predict. In one case, a farmer grew
particularly around flavour and texture. Some
a ‘small amount’ of a new crop (180 tonnes) of
of the participants were seeking to develop or
which 1 tonne went into a new food product,
take advantage of technological innovations
with the other 179 tonnes going to animal feed.
that would enable them to provide new products
Fortunately, there was a good relationship
or potentially unlock new sectors; others were
26 Emerging proteins in Aotearoa New Zealandbetween the parties and they are continuing to It is inevitable that there will need to be calculated
work to build this opportunity. There were also risks taken when developing a new sector.
several reports of neighbours looking over the However, the excitement over the potential for
fence at trial fields of new crops and proceeding emerging proteins to offer profitable solutions
to plant the same crops themselves, then at to farmers combined with the ease (in many
harvest time the neighbours coming by to ask cases) of ‘just putting some seeds in the ground’
who would be buying the crop. Most of those does mean there is a significant risk of supply
neighbouring crops ended up as animal feed. outpacing demand, especially in these early years.
Selling into channels producing food for human Other sectors have shown that this can lead to
consumption offered a significant potential the collapse of prices and the loss of appetite for
premium over the lower priced commodity animal further investment in the sector. It is important
feed channels, and while it is very useful to have that attention is paid to aligning demand with
the animal feed market as a fall-back option to supply as much as is possible, and that there is an
take surplus crops, there is insufficient financial awareness that the development of a new sector
incentive to develop new crops purely based on is a long game.
returns from animal feed.
What will it take for the sector to thrive? 278. We cannot rely on NZ provenance alone.
The participants generally agreed that, at least In terms of export markets, NZ does not have
in the short to medium term, it seems likely that the same long history of growing and producing
there will be continued demand for products emerging protein products as we do with our
consumers perceive as safe, sustainable, high traditional meat and dairy products. International
quality, ‘natural’ and as having a great provenance consumers have only recently begun to associate
story. However, it was noted that while NZ NZ with top quality wine and kiwifruit – and
provenance can be valuable, it is not enough that has taken many years and considerable
in itself to guarantee consumer purchase, and marketing. It is possible that with time and
there are many other countries who are investing resources, international consumers will associate
significantly in building their reputations as quality NZ with high quality, sustainable plant-based food
food providers, such as Ireland with its Origin products as well, but this is not something that will
Green initiative. Credibly leveraging provenance happen overnight.
can also become more complex in processed Businesses looking to export NZ grown products
foods, or where there are multiple ingredients. have reported that they are having to compete
There are producers who are successfully with cheaper imported emerging proteins
achieving a premium both locally and products being re-packaged then re-exported
internationally for their NZ-grown or NZ-produced with the NZ name prominently displayed
products. Pic’s Peanut butter is a remarkable (and ‘packed in’ shown in smaller font). This
‘brand NZ’ success story both here and in key is permitted under current regulations but is
Asian markets, despite the key ingredient, undermining our local producers with higher
peanuts, being imported to NZ prior to local costs of production and there is significant risk of
processing. Peanut growing trials in Northland consumers feeling misled if they realise the true
may lead to a supply of NZ peanuts in future, situation.
but local production is likely to remain relatively It is very important that we understand where
small scale and more expensive than is possible consumers feel the use of the NZ provenance is
overseas. As the ‘hero’ ingredient in peanut authentic, and where it is potentially too much
butter, it would be expected that use of NZ of a stretch. If there is misuse of the provenance
peanuts would be clearly highlighted on the label, it erodes trust and dilutes its value, affecting all
and Pic is anticipating some consumers will pay a producers.
premium for this.
There must also be awareness of the risk
On the other side, there are producers who report associated with relying solely on the provenance
that they are struggling to get domestic food angle. There is always the chance of a significant
service and food manufacturers to pay extra for a enough event or series of incidents and media
NZ-grown ingredient. This is especially common reports that undermine the consumer perception
where there is limited opportunity (or consumer of NZ as clean, green and safe. We must do
expectations) to communicate with the consumer everything we can to collectively protect and live
regarding the origin of that particular ingredient. up to the ‘brand NZ’ our consumers engage with;
Current regulations which enable a general “made but at the same time, it seems sensible to ensure
in NZ from local and imported ingredients” label that our products resonate with our consumers for
do not require transparency at the individual other reasons as well.
ingredient level, and while these are pragmatic
in many ways, they do not support the uptake of
locally-produced ingredients.
28 Emerging proteins in Aotearoa New ZealandYou can also read


