Country Profile Greece - www.lloyds.com/GreeceMI
←
→
Page content transcription
If your browser does not render page correctly, please read the page content below
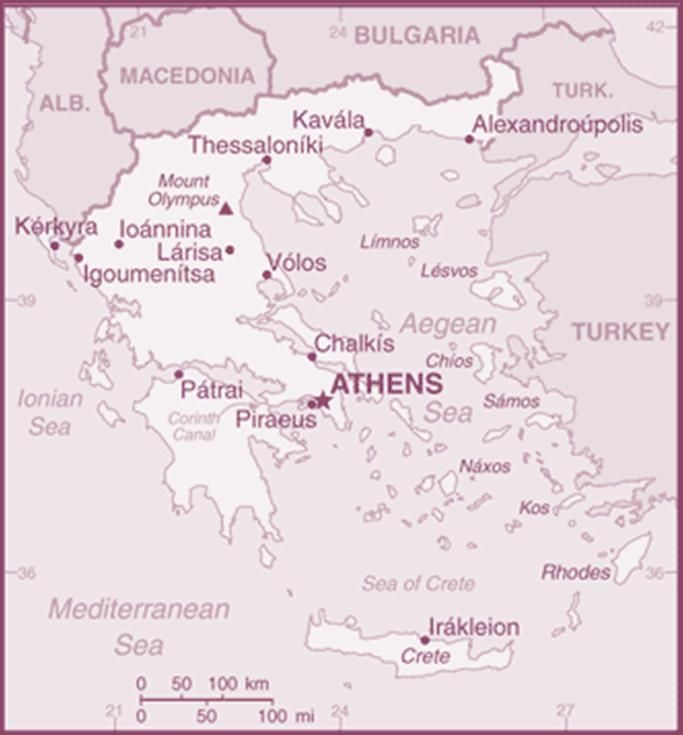
Country Profile
Greece
www.lloyds.com/GreeceMI

April 2014
filip.wuebbeler@lloyds.com
KEY FACTS

FULL NAME / CAPITAL CITY: Hellenic Republic / Athens                                                         GDP (PPP):                            US$ 266bn (Global Rank #51)

LANGUAGE:                             Greek                                                                  POPULATION:                           10.7m (Global Rank #81)

                                                                                                             IMF CATEGORISATION:                   “Developed”

MAIN EXPORT PARTNERS:                 Turkey 11%, Italy 8%, Germany 7% (2012)

MAIN IMPORT PARTNERS:                 Russia 12%, Germany 9.5%, Italy 8% (2012)

MAIN EXPORTS:                         Food and beverages, manufactured goods,
                                      petroleum products

MAIN IMPORTS:                         Machinery, transport equipment, fuels

                                          2012 Rank        2013 Rank       Change in Rank
EASE OF DOING BUSINESS:                         100              78                 22
COMPETITIVENESS:                                 90              96                 -6
FREEDOM FROM CORRUPTION:                         80              78                 2

   DISASTER               YEAR                   ECONOMIC COST (US$ x 1000)
Earthquake                1999                                                           4,200,000
Wildfire                  2007                                                           1,750,000
Drought                   1990                                                           1,000,000
Earthquake                1981                                                            900,000
Earthquake                1986                                                            745,000

 Source: Disaster Statistics based on: Prevention Web (2013); Export Statistics based on CIA World Factbook; Doing Business Indicators based on World Bank & World Economic Forum

                                                                                                                                                             © Lloyd’s              2
KEY STATISTICS
GOVERNANCE INDICATORS SIZE OF ECONOMY WEALTH PER CAPITA
Percentile Rank (1-100) 2012 Purchasing Power Parity (PPP) basis Purchasing Power Parity (PPP) basis
GR CY TR in International $ bn in International $
1,800 40,000
30,118
Greece Cyprus Turkey
26,875
2012 1,600
24,260
Government Effectiveness 62 88 65 1,400 30,000
1,200
Political Stability and Absence of
38 68 13 1,000
Violence/Terrorism 20,000
800
Control of Corruption 51 85 63
600
337
299
274
400 10,000
Regulatory Quality 68 84 66
200
Rule of Law 64 84 57 0 0
2006 2012 2018f 2006 2012 2018f
Voice and Accountability 67 79 41
GR CY TR GR CY TR
TOTAL NON-LIFE DIRECT INSURANCE MARKET* NON-LIFE DIRECT INSURANCE MARKET LLOYD’S 2013 GROSS SIGNED PREMIUMS
Premiums in US$ m Premiums in US$ m; by OECD Class Gross Signed Premiums in US$ m; by country of origin
10,000 250
216
206
Motor
200
800
9,000
940
8,000 200
PA & Health
7,000 4,456
6,000 150
Greece
3,755
Property
3,289
5,000
3,055
3,083 2012 100
4,000
Liability US$ 3.0bn
3,000
2,000 50
MAT
1,000
0 0
Miscellaneous 3,479
2011 2012 2013 2011 2012 2013
GR CY TR GR CY TR
All data, sources & data limitations are available for download at www.lloyds.com/comparecountries; * 2013 total non-life based on CAGR projection
LLOYD’S TRADING POSITION Insurance: Yes for all classes on a Freedom of Services basis, and Yes for all classes except for term life on an
Greece Establishment basis.
Reinsurance: Yes
www.lloyds.com/crystal Coverholders: Yes
© Lloyd’s 3BUSINESS ENVIRONMENT
Only gradually recovering European growth and lingering Swiss franc strength will restrain economy and inflation: Coalition government remains on
shaky ground, but short-term stability likely to be assured. The two-party ruling coalition of the centre-right New Democracy (Néa Dimokratía: ND) and left-
leaning Panhellenic Socialist Movement (PASOK) has a slim, three-seat majority in the Greek legislature. Prime Minister Antonis Samaras is keen to prevent
major internal rifts that could lead to a potential government collapse. This is particularly the case during the first half of 2014, when Greece holds the rotating
presidency of the Council of the European Union. However, challenges remain, particularly regaridng the future trajectory of the government's socio-economic
policies and further austerity and restructuring measures, which will test the coalition's stability several times.
Demonstrations and strikes continue to trouble politicians, violent attacks also on the rise. Protests tend to attract large numbers, can affect vital public
services, and often turn violent. In 2012, violent riots broke out in the capital, Athens, with dozens of businesses looted and numerous properties set ablaze. In
2013, there were a number of attacks on political figures, as well as businesses, with nationwide strikes and demonstrations taking place regularly throughout
the year. Ongoing fiscal and economic difficulties, accompanied by austerity measures, will continue to test public patience throughout 2014.
Economy will contract at decelerating pace in 2014. Activity fell for the sixth consecutive year in 2013 and the economy is expected to contract again,
although at a modest pace, in 2014. External demand is seen firming in 2014, which should help to sustain export growth. Domestic demand will remain under
intense pressure, although the stabilisation of the labour market situation, falling prices, and some easing of fiscal tightening should provide some support.
Delays in implementation of some structural reforms and privatisation receipts raise concerns. Although labour market reforms have been advancing at
a good pace, there have been delays in the implementation of reforms aimed at liberalising product and service markets. At the same time, meeting the
privatisation target for 2014 will also be challenging. Reforms will largely determine the performance of the economy over the medium to long term, but they will
also be an important factor for Greece's official creditors when they evaluate the success of the adjustment.
GROSS DOMESTIC PRODUCT (GDP) TOP-10 SECTORS (BY VALUE ADDED) BUSINESS ENVIRONMENT INFORMATION
(nominal GDP levels in billion US$; Real GDP change) (value added in billion US$ & 2014 Change in real %) (provided by IHS Global Insight, April 2014)
400 4% 2013 2014
TOP SECTORS Value Percentage
2.1% 2.3% Added Change
2%
1.7% 1.5% 1. Real estate 27.4 1.3
0% 2. Public Admin. & Defence 26.3 -3.5
-0.2%
3. Retail trade - total 17.1 -0.7
200 -2% 4. Education 17.0 -1.4
5. Wholesale trade 16.2 0.4
-3.9% -4% 6. Hotels & restaurants 14.6 -1.6
-4.9% 7. Health and social services 11.1 -1.9
-6%
8. Agriculture 11.0 1.8
-7.0%
9. Banking & related financial 10.7 1.7
-7.1%
0 -8%
10. Water transport 8.8 1.6
2010 2011 2012 2013 2014 2015 2016 2017 2018 Top-10 Total 160.2 For daily updates visit: > www.ihsglobalinsight.com
© Lloyd’s 4INSURANCE ENVIRONMENT
2012 MAJOR DIRECT INSURERS 2012 DIRECT GROSS PREMIUMS QUICK LINKS / USEFUL SOURCES
(GWP in million US$) (Gross Written Premium in % of total)
Insurance Market Profiles
0 500 1000
> www.iii.org/international/profiles
Ethniki 1,158.8 Motor 257
56
The Greek Insurance Association
American Life 437.4 102 > www.eaee.gr
ING EAAEZ 415.5 PA & Health
The Insurance Regulator
EFG Eurollife 350.7
> http://www.bankofgreece.gr
Property Greece
Interamerican Life 322.2 2012
675
Lloyd’s Agency Network
Allianz 320.7 Liability US$ 3.0bn > www.lloyds.com/agency
NOTE:
1,885
Interamerican Non-Life 318.3 This ranking includes
life & non-life Lloyd’s Claims Team
Agrotiki 298.2 MAT
companies 81 > www.lloyds.com/claims
AXA 276.8
Miscellaneous
Groupama Phoenix 266.3
BUSINESS CULTURE GUIDE
> http://www.kwintessential.co.uk
Source: Association: > www.eaee.gr Source: Regulator: > www.eaee.gr (View Resources > Culture Guide)
The Greek non-life insurance market is estimated to be worth around US$ 3bn in 2012: In 2011, there were 69 companies (down from 73 in 2010) active in the market
(SA companies and branches of foreign insurance companies). The expectation is that there will be a further reduction with small and undercapitalised companies either shut
down or absorbed, as a result of the financial crisis and enhanced regulatory requirements. The insurance sector has also suffered losses from the fall in investments' value
and from the participation to the Greek State Bonds exchange program (PSI). Insurance in the country continues to be marked by significantly low levels of penetration.
International foreign insurers: The Greek insurance market has a number of foreign players including Interamerican (owned by Eureko insurance group) as well Groupama
Phoenix (owned by French group) amongst others.
Broker Market: The use of brokers has only relatively recently been introduced to the Greek insurance market. Brokers are increasing and becoming more popular by buying
significant industrial accounts as well as commercial ones.
No local reinsurers: Mapfre is the only major Continental reinsurer with a representative office in Athens.
Outlook: The drastic reduction in household budgets following the cuts decided by the government on salaries and pensions in the public sector, zero salary increases in the
private sector, high unemployment, coupled with the low insurance awareness of Greek consumers, means that growth rates are likely to be subdued for the insurance market
over the medium term.
© Lloyd’s 5LLOYD’S BUSINESS
2009-2013 LLOYD’S TOTAL PREMIUMS 2013 LLOYD’S HIGH LEVEL CLASSES
Gross Signed Premiums; Direct versus Reinsurance; in million US$ Gross Signed Premiums; high level classes; in million US$
250 2013 GROSS SIGNED PREMIUMS*
UK Motor 0.0
Total US$ 200m Overseas Motor 0.2
200 45 36
54 39 37 Property Treaty 4.9
150 Reinsurance US$ 37m
Property (D&F) 16.7
Direct US$ 164m
Marine 134.3
100
176 181
167
*COUNTRY OF ORIGIN PREMIUMS Energy 4.2
165 164
Policyholders are based or
50 headquartered in this territory;
Casualty 26.6
Casualty Treaty 1.3
Premiums may be written outside
0 this territory; Aviation 2.5
2009 2010 2011 2012 2013
X Not necessarily where risks are located Accident & Health 9.8
Direct Reinsurance
X May differ to what is reported to
local regulator (dependent on local requirements). 0 20 40 60 80 100 120 140 160
SOURCE: Market Intelligence based on *Gross Signed premiums; Xchanging (2014); unaudited figures based on country of origin and processing by calendar year; see Appendix for details
A Type 2 office is defined as a Country Representative, Ms Marianna Papadakis
who is either employed directly or who is a third party Office in Greece
retained by Lloyd’s. A type 2 Representative satisfies the Lloyd’s 25A Boukourestiou Street
Type 2 Country 106 71 Athens, Greece
minimum requirements for the licence in the territory and
Office Manager
may also undertake additional regulatory or legislative TELEPHONE: +44 0207 327 6802
functions. They are also responsible for the promotion of +30 210 363 9156
Lloyd’s and the protection of the brand within the country EMAIL: marianna.papadakis@lloyds.com
© Lloyd’s 6LLOYD’S OBJECTIVES
Maintain and enhance Lloyd’s position as a strong, secure, reliable and stable specialist insurance provider for the local business community.
LLOYD’S KEY INITIATIVES 2014
Demonstrate thought leadership in protecting the brand and ensure continuous business development despite the challenging local environment: To be
achieved by maintaining good relationships with the Bank of Greece and ICCS, staying close to political events and strengthening the coverholder network.
Profile Lloyd’s as a partner to local industry: Play a more active role in supporting the local insurance and broking associations and promoting education initiatives for
local insurance stakeholders, encouraging them to use Lloyd’s more as a specialist market participant.
Identify and support business opportunities where there is local demand: Explore with underwriters, brokers and local stakeholders appetite to promote specific
classes and re-focus on local strengths.
EVENTS & MARKET INTELLIGENCE
2014 INDUSTRY EVENTS 2014 LLOYD’S EVENTS MARKET INTELLIGENCE
Available Market Intelligence products for this territory include:
Hydra Insurance and Reinsurance Meeting, Local Market Presentation, TBC Country Profile
September Class of Business Event, TBC
Market Presentation
Posidonia Shipping Event, June
Class Review – Lite (work in progress)
www.lloyds.com/GreeceMI
© Lloyd’s 7APPENDIX
MACRO-ECONOMIC & BUSINESS ENVIRONMENT DATA
Source: IMF (www.imf.org/external/data.htm), World Bank (http://data.worldbank.org/), IHS Global Insight.
Notes: GDP data on size and wealth of the economy is reported in Purchasing Power Parity (PPP) terms; this is the most accurate indicator of the true standard of living in
each country and therefore potential demand. To calculate this, GDP is converted from local currency to an international $ currency using PPP exchange rates rather than the
market exchange rate. The PPP local currency-to-international $ exchange rates are determined such that a standard basket of goods has the same price in international $
terms in each country. This adjusts for the differing costs of goods across countries, when converted at market exchange rates.
INSURANCE MARKET DATA
Source: Reported data derived by Lloyd’s Market Intelligence team; original source is regulatory bodies, associations, third party information providers.
Notes: Data is reported in US$. For more information, see www.lloyds.com/comparecountries.
Exchange Rates Note: Where required, data has been converted to US$ using annual average exchange rates as per www.oanda.com.
LLOYD’S PREMIUM DATA
Source: Reported data derived by Lloyd’s; original source is Xchanging (data therefore contains only premiums processed by Xchanging).
Notes: Data is reported is US$, on a calendar year basis and is signed gross premiums. This differs from the data published in the Lloyd’s Annual Report, which is also on a
calendar year basis, but is written gross premiums and sourced directly from Syndicates. Differences are therefore (1) timing inconsistencies between signed and written gross
premiums; (2) inconsistent use of exchange rates by Syndicates and Xchanging; & (3) incompleteness of Xchanging data set for certain classes of business (a substantial
amount of premium is not processed by Xchanging and missing from the REG 258 data set; this comprises, for example, UK Motor).
Exchange Rates Note: Data has been converted to US$ using monthly exchange rates provided by Xchanging.
Definitions:
Gross Signed Premiums: Original and additional inward premiums, plus any amount in respect of administration fees or policy expenses remitted with a premium but
before the deduction of outward reinsurance premiums.
Calendar Year: Relates to the calendar year in which the premium, additional or return, is processed by Xchanging. This is irrespective of the actual underwriting year of
account, which is determined by the inception date of each risk.
Country of Origin: Denotes the domicile of the insured party (i.e. the coverholder or policyholder). This is the country from which demand for the insurance / reinsurance
emanates, & is irrespective of the country to which the risk is classified for regulatory reporting purposes.
Example: A policy holder in the UK insuring a holiday home in France would be classified as a UK risk by “Country Of Origin”, but “French” for regulatory reporting
purposes. Similarly a risk incepting on 1st December 2007 would be classified at 2007 “Underwriting Year of Account” but may not be processed by Xchanging until 2008
and so be allocated to the 2008 “processing year”.
ACCESSING THE DATA: to access the raw data in this document, and equivalent data for other countries, see www.lloyds.com/comparecountries.
DISCLAIMER: This document is intended for general information purposes only. Whilst all care has been taken to ensure the accuracy of the information, Lloyd's does not
accept any responsibility for any errors or omissions. Lloyd's does not accept any responsibility or liability for any loss to any person acting or refraining from action as a
result of, but not limited to, any statement, fact, figure, expression of opinion or belief contained in this document.
© Lloyd’s 8You can also read


