FINGER ON THE PULSE CAN AUSTRALIA'S DIGITAL ID SCHEME ACHIEVE LIFT-OFF? - trust eu affairs
←
→
Page content transcription
If your browser does not render page correctly, please read the page content below
www.e lectroni cpaymentsi nternati onal .com         Issue 366 / DecemBER 2017

              FINGER ON THE PULSE

                               CAN AUSTRALIA’S DIGITAL
                            ID SCHEME ACHIEVE LIFT-OFF?
                COUNTRY SURVEYS                             FEATURE                               INSIGHT
                 The state of play for                   DBC Debate: The                   Ignore consumer payment
              payments in Chile, Iran and                 challenges and                      preferences and risk
                    New Zealand                        opportunities of PSD2                     missing a trick

EPI December 366.indd 1                                                                                             09/11/2017 17:30:57
contents

              this month
                   COVER STORY                                                                                                          NEWS
                                                                                                                                       05 / EDITOR’S LETTER
                   DIGITAL ID                                                                                                          06 / DIGEST
                                                                                                                                       • WorldRemit introduces service for
                                                                                                                                         remittances to Hungary
                                                                                                                                       • Paytm launches Inbox chat platform
                                                                                                                                       • Visa Direct makes debut in Europe
                                                                                                                                       • DBS launches new API platform
                                                                                                                                       • EMQ partners with QFPay in
                                                                                                                                         Indonesia
                                                                                                                                       • American Express adds Samsung Pay
                                                                                                                                         support in Canada
                                                                                                                                       • Indian banks to bring digital payment
                                                                                                                                         solutions under BHIM
                                                                                                                                       • US Bank unveils two digital
                                                                                                                                         payment solutions
                                                                                                                                       • Interac supports Samsung Pay

                                                                                                                          12
                        Editor: Douglas Blakey                  Group Editorial Director:           Director of Events: Ray Giddings
                        +44 (0)20 7406 6523                          Ana Gyorkos                           +44 (0)20 3096 2585
                     douglas.blakey@verdict.co.uk                +44 (0)20 7406 6707                   ray.giddings@compelo.com
                                                              ana.gyorkos@globaldata.com                  Head of Subscriptions:
                            Senior Reporter:                                                                   Alex Aubrey
                           Patrick Brusnahan                     Sub-editor: Nick Midgley                  +44 (0)20 3096 2603
                         +44 (0)20 7406 6526                      +44 (0)161 359 5829                   alex.aubrey@verdict.co.uk
                   patrick.brusnahan@verdict.co.uk            nick.midgley@uk.timetric.com
                                                                                                      Sales Executive: Jamie Baker
                    Junior Reporter: Briony Richter               Publishing Assistant:                    +44 203 096 2622
                                                                       Joe Pickard
                         +44 (0)20 7406 6701                                                           jamie.baker@verdict.co.uk
                                                                  +44 (0)20 7406 6592
                     briony.richter@verdict.co.uk
                                                                joe.pickard@verdict.co.uk

                                                                                                                                       06
                          Customer Services: +44 (0)20 3096 2603 or +44 (0)20 3096 2636, briefings@verdict.co.uk

                               Financial News Publishing, 2012. Registered in the UK No 6931627. ISSN 0956-5558
                      Unauthorised photocopying is illegal. The contents of this publication, either in whole or part, may not be
                      reproduced, stored in a data retrieval system or transmitted by any form or means, electronic, mechanical,
                               photocopying, recording or otherwise, without the prior permission of the publishers.
                                        For more information on Verdict, visit our website at www.verdict.co.uk.
                           As a subscriber you are automatically entitled to online access to Electronic Payments International.
                             For more information, please telephone +44 (0)20 7406 6536 or email briefings@verdict.co.uk.
                                                  London Office: 71-73 Carter Lane, London, EC4V 5EQ
                                                Asia Office: 1 Finlayson Green, #09-01, Singapore 049246
                                       Tel: +65 6383 4688, Fax: +65 6383 5433 Email: asiapacific@sg.timetric.com

                                                                                                                                         follow EPI on twitter
                                                                                                                                           @Payments_News

   2 | December 2017 | Electronic Payments International

EPI December 366.indd 2                                                                                                                                                09/11/2017 17:31:15
contents

                                                                        december 2017
         FEATURES
        09 / DBC DEBATE
        With the deadline for PDS2 just around the
        corner, banks and fintechs must be prepared
        for the challenges it brings as well as the
        opportunities that come with it. Briony
        Richter reports from the latest Digital
        Banking Club debate

        12 / DIGITAL ID
        Australia Post has launched a smartphone-
        based national digital ID scheme. However,
        until it gains a significant number of partners,
        particularly in the banking sector, the

                                                                                                                                                19
        scheme’s adoption may be limited. Robin
        Arnfield reports

        14 / FISERV
        With cryptocurrencies, the Internet of Things      s to talk about cracking China, disrupting        s to talk about cracking China, disrupting
        and APIs, a lot is happening in payments.           COUNTRY SNAPSHOTS
                                                           SWIFT, and leveraging WeCha                        INDUSTRY INSIGHT
                                                                                                             SWIFT, and leveraging WeCha
        Patrick Brusnahan spoke to experts from
        Fiserv to see how the sector will develop in
        the coming years. What is set to make an
                                                           18 / CHILE                                        17 / ACI WORLDWIDE
                                                           Cash remains the preferred method of              With more than five million high-spending
        impact, and what will be a damp squib?
                                                           consumer payments in Chile, accounting for        tourists from China expected to travel to
                                                           76% of total payment transaction volume           Europe this year alone, merchants that ignore

        15 / AMAZON WEB                                    in 2016. However, initiatives to reduce the
                                                           unbanked population are taking effect
                                                                                                             their payment preferences risk missing a huge
                                                                                                             trick, writes Andy McDonald
             SERVICES
        From social media to payments to location,
        all forms of data can be used to help the
                                                           19 / IRAN
                                                           Iran’s payment cards market recorded robust
        consumer. With open banking it is becoming         growth in terms of cards in circulation,
        even more accessible, but how can a company        transaction volume and value between 2012
        go through it all? Patrick Brusnahan speaks        and 2016, despite international sanctions
        to Amazon Web Services to find out                 against the country

        16 / MOBILE MONEY                                  20 / NEW ZEALAND
                                                                                                              17
        Mobile devices are rapidly becoming the
        consumer’s most popular way to bank,
                                                           New Zealand’s cards and payments industry
                                                           is well developed, and consumers are prolific
                                                                                                             21 / TRUSTEUAFFAIRS
                                                                                                             5AMLD is a set of proposed amendments to
        according to Visa’s third Digital Payment          users of payment cards. Banks and payment
                                                                                                             the anti-money laundering directive in the
        Study. Briony Richter takes a closer look at       companies also take regular initiatives to
                                                                                                             light of recent terrorist attacks. As Monica
        the survey results                                 improve financial literacy
                                                                                                             Monaco writes, it covers key areas including
                                                                                                             virtual currencies and prepaid cards

                                                                                                             22 / PPRO GROUP
                                                                                                             No matter what happens, someone
                                                                                                             somewhere finds a way to turn a profit. So
                                                                                                             much focus has been on the negatives of

                                                                                                 09          Brexit that there is a danger that opportunities
                                                                                                             will be missed, writes Simon Black

                                                                                                        www.electronicpaymentsinternational.com | 3

EPI December 366.indd 3                                                                                                                                   09/11/2017 17:31:21
Simple, secure and effortless digital
          solutions for financial services organisations

                                       To find out more please visit:
                                       www.intelligentenvironments.com
                                             @IntelEnviro

      Intelligent Environments is an international provider of innovative financial services technology. Our mission is to
      enable our clients to deliver a simple, secure and effortless digital customer experience.

      We do this through Interact®, our digital financial services platform, which enables secure customer acquisition,
      onboarding, engagement, transactions and servicing across any digital channel and device. Today these are
      predominantly focused on smartphones, PCs and tablets. However Interact® will support other devices, if and when
      they become mainstream.

      We provide a more viable option to internally developed technology, enabling our clients with a fast route to market
      whilst providing the expertise to manage the complexity of multiple channels, devices and operating systems.
      Interact® is a continuously evolving digital customer engagement platform that ensures our clients keep pace with
      the fast moving digital landscape.

      We are immensely proud of our achievements, in relation to our innovation, our thought leadership, our
      industrywide recognition, our demonstrable product differentiation, the diversity of our client base, and the calibre of
      our partners.

      For many years we have been the digital heart of a diverse range of financial services providers including Generali
      Worldwide, HRG, Ikano Retail Finance, Lloyds Banking Group, MotoNovo Finance, Think Money Group and Toyota
      Financial Services.

IE Adverts - 2017 MG Edit.indd 1                                                                                      27/07/2017 12:46:16
editor’s letter

                            e-wallet growth set to
                            take off, and a huge
                            payments hit for Walmart
                                                                                                              Douglas Blakey, Editor

        I
              t has been a busy month for global payments reports.        baby boomers are increasingly enthusiastic about shopping
              First up came the annual 2017 World Payments                online. It notes that global household spending by people aged
              Report from Capgemini and BNP Paribas, followed by          over 60 will reach $15trn by 2020, twice as much as in 2010.
        McKinsey’s annual survey and finally Worldpay’s Global              In Europe, people aged over 50 spend 71% more than young
        Payments Report.                                                  people on their average purchases. In the US, consumers aged
           Worldpay’s research examines the online shopping market in     over 50 will soon account for 70% of the country’s disposable
        36 countries, and forecasts a major drop in established forms     income. It makes a change not to read a report obsessed with
        of payments such as debit and credit cards in the period to       the millennial segment.
        2021. In 24 of the countries surveyed, there will be double-        By 2021, Worldpay estimates that China’s e-commerce
        digit CAGR in e-commerce in the five years to 2021 (see table).   will be worth $1.55trn a year, ahead of the US ($1.08trn) and
           E-wallets are set for dramatic growth and will become the      the UK third on $268bn. Japan ($183bn), Germany ($123bn),
        most popular payment method for online transactions, taking       France ($122bn) and India ($105bn) come net ahead of South
        46% of the market, according to WorldPay – double the             Korea ($81bn) and Canada ($69bn).
        combined sum for credit and debit cards.
                                                                          Walmart scores QR hit
           The Worldpay report is notable for its comments relating
        to baby boomers and silver surfers, a demographic that will       Here is one in the eye for the Apple evangelists who tried to

        reshape the global payments market. The report notes that         persuade us all that Apple Pay would do for mobile payments
                                                                          what the iPod did for music. And also a lesson for some of us
                                                                          who, years back, took one look at QR codes as a method of
         FASTEST-GROWING E-COMMERCE MARKETS TO 2021 (CAGR)                payments and said ‘no thanks’.
         Colombia            31%        Netherlands          14%            Reuters has the interesting story as EPI goes to press that
         Nigeria             30%        Turkey               13%
                                                                          Walmart’s mobile app is about to overhaul Apple Pay as the
         Argentina           24%        UAE                  12%
                                                                          most popular mobile payment method in the US.
         India               24%        Canada               11%
                                                                            Available in almost 5,000 stores, Walmart Pay was launched
         Indonesia           23%        China                11%
                                                                          as recently as December 2015, more than a year after Apple
         Vietnam             22%        Germany              11%
                                                                          Pay went live. Unlike Apple Pay, Walmart Pay works with both
         Philippines         21%        South Africa         11%
                                                                          iOS and Android phones.
         South Korea         19%        Denmark              10%
                                                                            Witnessing a demonstration of how Walmart Pay works, it
         Thailand            17%        Hong Kong            10%
         Meico               17%        Norway               10%
                                                                          seemed to the writer that it was clunky and more trouble than

         Malaysia            15%        UK                   10%          it was worth, but – and it is a big but – in June it was used by
         Italy               14%        US                   10%          more than 5% of Walmart’s shoppers. That is a lot of shoppers.
         Source: Worldpay                                                 Fair play to them. <

                            Get in touch with the editor at: douglas.blakey@verdict.co.uk

                                                                                         www.electronicpaymentsinternational.com | 5

EPI December 366.indd 5                                                                                                                   09/11/2017 17:31:27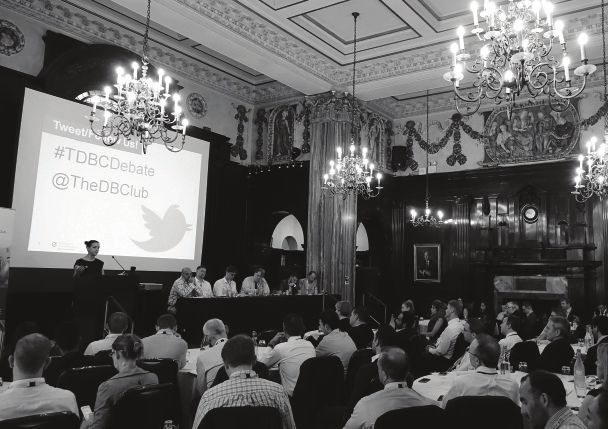
News | Digest

              news digest
              WorldRemit introduces service                                                                      Visa Direct makes
                                                                                                                 debut in Europe
              for remittances to Hungary
              UK-based global digital money-transfer               Commenting on the launch, WorldRemit
                                                                                                                 Visa has launched a real-time payments
                                                                                                                 platform, Visa Direct, in Europe to enable
              business WorldRemit has launched instant          founder and CEO Ismail Ahmed said:               companies to transform domestic and
              money transfers to Hungary.                       “Hungary’s diaspora has a growing need to        cross-border payments for businesses and
                 The newly launched service enables             access quick, secure and convenient money        consumers.
              migrants in over 50 countries to send             transfers. WorldRemit’s service answers             Visa Direct allows secure money
              remittances directly to bank accounts in          that need.                                       transfers and provides immediate access
              Hungary through the WorldRemit app or                “Now a Hungarian waiter, language             to funds and also the ability to make
              website. It allows users to send money            interpreter or IT professional in London         purchases at 44 million retail locations
              directly from mobile devices with just few        can transfer money back home as easily as        globally. The platform enables B2B, B2C
              taps, eliminating the need to visit an agent.     sending an instant message.”                     and P2P payments.
                 Approximately 600,000 Hungarian                   According to the World Bank, Hungary             The platform is one of the application
              citizens are living abroad, with top              received $4.5bn in 2015, making the              programme interface-based network
              migration destinations including Germany,         nation one of the top remittance-receiving       capabilities available on the Visa
              the UK, Austria and Switzerland.                  destinations in Europe. <                        Developer Platform. It aims to help
                                                                                                                 financial institutions, merchants and

              Paytm launches Inbox chat platform
                                                                                                                 technology companies meet the demands
                                                                                                                 of consumers and merchants who use
                                                                                                                 connected devices to shop. Visa has
                                                                                                                 partnered Worldpay to increase the
                                                                                                                 availability of Visa Direct to merchants in
                                                                                                                 Europe and markets worldwide.
                                                                                                                    Visa Europe product solutions senior
                                                                                                                 vice-president Mike Lemberger said:
                                                                                                                 “For decades, Visa has led the way in
                                                                                                                 transforming the way we pay in stores and
                                                                                                                 online. Now we have an opportunity to
                                                                                                                 transform how consumers and business
                                                                                                                 pay each other in a fast, convenient and
                                                                                                                 secure way.
                                                                                                                    “Visa Direct is a proven platform that
                                                                                                                 enables technology companies, businesses
                                                                                                                 and financial institutions to meet the
                                                                                                                 demand for real-time payments, backed by
              Indian digital wallet and payment service         peer payment service for Indian customers by     the ubiquity, cost-efficiency and speed of
              Paytm has introduced Inbox, a messaging           the end of 2017.                                 Visa’s global network.”
              service that allows users to chat, send and          Paytm senior vice-president Deepak Abbot         Worldpay global e-commerce chief
              request money to friends and family.              said: “We have realised that besides making      product officer Dave Glaser said: “In
                 The messenger also enables users to            payments, our users and merchants also like to   recent years, the payments landscape
              send photos and videos instantly, share live      communicate with each other. There is a need     has changed dramatically with clients and
              locations, and recall messages using its Delete   for social messaging, commerce and payments      consumers alike expecting to be able to
              for All function.                                 seamlessly blending into one another.            make a payment under their own terms
                 The Paytm Inbox also features notifications,      “One step for us towards meeting this         – whether that is making a real-time
              orders and games as well as the messaging         consumer need is Paytm Inbox, where you can      payment or using a specific method.
              service. It will be initially made available to   chat with friends or merchants and send and         “We are proud to be working with Visa
              Android phone users, and subsequently to          receive money effortlessly and securely.         on this unrivalled platform as an early
              iOS customers.                                       “This will help us drive greater engagement   adopter in Europe and other global markets
                 The update comes immediately after             on our platform and build a stronger bond        and believe that Visa Direct is an important
              WhatsApp revealed plans to launch a peer-to-      with our customers.” <                           step in meeting those needs.” <

   6 | December 2017 | Electronic Payments International

EPI December 366.indd 6                                                                                                                              09/11/2017 17:31:31
News | digest

        DBS launches new API platform                                                                       EMQ partners with
        DBS Bank has unveiled the world’s largest
        API developer platform. The platform
                                                             A McDonald’s spokesperson said: “The
                                                          DBS API partnership has helped us to speed        QFPay in Indonesia
        encompasses 155 APIs in more than 20              up the process of payments so that our            EMQ, a Hong Kong-based financial
        categories, such as fund transfers, rewards and   customers can focus on enjoying their meals.      technology startup, has entered into a
        real-time payments.                                  “Speed is essential in this process, and       strategic partnership with mobile payment
           Shee Tse Koon, group head of strategy and      we’re delighted that banks such as DBS are        and big data technology company QFPay
        planning, and head of ecosystems, stated:         exploring the use of digital capabilities to      to enable merchant settlement across
        “The digital momentum that we see today           smoothen such experiences.”                       Indonesia.
        is just the tip of the iceberg. By creating          DBS has recently collaborated with                The new merchant-settlement platform,
        ecosystem partnerships – collaborating,           governments, partners, fintechs and other         which uses EMQ’s scalable API, is designed
        creating and innovating together with partners    industry players to make banking quicker,         to enable consistent settlement processes
        – we believe that we can provide the best         simpler and efficient through the use of APIs.    for businesses.
        products, solutions and experiences.”                David Gledhill, group chief information           The platform claims to deliver a secure
           DBS says it is continuing its efforts to       officer at DBS Bank, said: “This has given us     and scalable infrastructure for mobile
        create innovative and personalised experiences    an edge – enabling us to operate with fintech-    payments in the country, providing
        for its customers. The platform has already       like agility and nimbleness, and also platform-   benefits in efficiency and speed after
        been adopted by 50 companies, including           like inclusiveness. This will be transformative   integration to mobile payments globally.
        McDonald’s, MSIG, PropertyGuru and                in ways not imagined previously, both for the        EMQ co-founder and CEO Max Liu
        several startups.                                 customer and the bank.” <                         commented: “Indonesia is Southeast Asia’s
                                                                                                            largest economy and is one of the top

        American Express adds Samsung                                                                       destinations for Chinese tourists, who
                                                                                                            hold significant buying power with diverse
                                                                                                            payment needs.

        Pay support in Canada                                                                                  “To address this, mobile payment
                                                                                                            providers such as QFPay are expanding
                                                          Samsung Galaxy Apps Store, for purchases          with different international merchants,
                                                          made at American Express accepting                which in turn require a cross-border
                                                          merchants.                                        platform for real-time merchant
                                                             “The addition of Samsung Pay marks             settlement.
                                                          another example of how American Express              “Our partnership with QFPay is a great
                                                          Canada is furthering its digital-first            validation that our extensive settlement
                                                          strategy,” the company said in a press note.      network provides a critical gateway that
                                                             American Express’s intelligent security        connects businesses. We are pleased
                                                          systems and fraud-protection guarantee            to partner and support QFPay with its
                                                          will approve the transactions with PIN,           expansion across Asia.”
                                                          fingerprint or iris.                                 QFPay co-founder and president Patrick
                                                             American Express Canada’s vice-                Ngan said: “This is an exciting milestone
                                                          president of consumer cards, Megan                in our partnership with EMQ as we
                                                          McKee, said: “We know our cardmembers             continue our strategic expansion across
                                                          love the speed and convenience of paying          Asia. Our integration with EMQ’s scalable
                                                          for purchases with a tap of their mobile          API platform has empowered us with a
                                                          device.                                           faster, more cost-effective way to deliver
                                                             “That’s why we’re thrilled to add              payments to our merchants and suppliers
                                                          Samsung Pay to our digital payment                in Indonesia.
                                                          portfolio. Now our cardmembers have even             “By leveraging our experiences in
                                                          greater flexibility and choice in how they        serving over one million merchants, we
                                                          choose to pay.”                                   are confident in continuing to bring secure
        American Express has expanded its mobile             Samsung Electronics Canada’s COO and           mobile payment services and solutions to
        wallet portfolio with the addition of             executive vice-president, Paul Brannen,           worldwide merchants. We look forward
        Samsung Pay to Canadian cardholders.              added: “We’re excited to partner with             to further expanding our partnership with
           The newly added service will be available      American Express to help bring Samsung            EMQ across Asia,” Ngan added.
        for eligible Canadian consumer, small             Pay to more Canadian consumers.                      EMQ is currently operational in Hong
        business and corporate cards issued by               “Not only will this enhance our digital        Kong, Taiwan, Indonesia, Vietnam and the
        Amex Bank of Canada. It supports all the          wallet, but it will also empower Amex             Philippines. It plans to expand into other
        latest Samsung Galaxy mobile devices.             cardmembers with a seamless mobile                markets initially in Asia and then globally,
           Eligible cardholders can add American          payment solution that is designed for             covering North America, Europe and the
        Express cards to Samsung Pay via the              simplicity, security and convenience.” <          Middle East. <

                                                                                                     www.electronicpaymentsinternational.com | 7

EPI December 366.indd 7                                                                                                                             09/11/2017 17:31:32
News | Digest

              Indian banks to bring digital                                                                Interac supports
              payment solutions under BHIM                                                                 Samsung Pay
              Public and private Indian banks are set          The mobile app was launched by Prime
              to bring digital payment solutions under      Minister Narendra Modi in December 2016        Interac Association/Acxsys has introduced
              the Bharat Interface for Money (BHIM)         as a government-promoted UPI application       Samsung Pay as a mobile payment option
              to encourage the adoption of Unified          to promote digital as a direct competitor      for Interac Debit card holders in Canada.
              Payments Interface (UPI)-driven digital       to bank-led UPI apps such as Axis Pay,            The payment option is being promoted
              payment applications.                         SBI Pay, as well as non-bank UPI players       as providing convenience, security and
                 Banks will show BHIM as a prefix to UPI    such as the Flipkart-owned PhonePe and         privacy of contactless transactions to debit
              applications to remove confusion among        Google’s payment application, Tez.             card customers issued by participating
              customers.                                       The bank-led UPI apps will be rebranded     financial institutions for supported
                 The National Payments Corporation of       and renamed Bhim SBI Pay, Bhim Axis Pay        Samsung devices.
              India, which developed the mobile app, has    and Bhim RBL Pay.                                 Consumers with Samsung devices and
              already instructed banks to display prefix       A bank representative who is directly       debit cards issued by ATB Financial, CIBC
              BHIM prominently at all major merchant        aware of the development said: “The UPI        and Scotiabank can now use Interac Debit
              checkout locations.                           front end of the bank apps will be changed     on Samsung Pay to pay for purchases at
                 The move aims to further the               to include the name BHIM. Although this        merchant locations in Canada wherever
              promotion of UPI as a one-stop solution       will be a nomenclature change, eventually,     Interac Flash payments are accepted.
              for smartphone-based small-value retail       everything will become part of the larger         When cardholders add Interac Debit
              transactions.                                 BHIM family.” <                                on Samsung Pay to their device, a
                                                                                                           virtual account number is created that is

              US Bank unveils two digital
                                                                                                           different from the physical card number.
                                                                                                           All Samsung Pay transactions will be
                                                                                                           processed through the Interac Token

              payment solutions                                                                            Service Provider, which generates a
                                                                                                           sequence of numbers valid for a single
                                                                                                           transaction only.
                                                            mobile number or email address. The bank          Interac Association and Acxsys
                                                            uses the Zelle Network and its messaging       Corporation president and CEO Mark
                                                            capabilities to enable clients to send money   O’Connell said: “Interac Debit continues
                                                            to any payee with a US bank account,           to be the most-used payment method in
                                                            either immediately or the next day.            Canada, and by making it available through
                                                               Supplier Prefer Pay offers multiple         Samsung Pay, we’re ensuring that even
                                                            payment options and allows the enrolment       more Canadians will be able to use it to
                                                            and payment of suppliers. It processes         make mobile payments directly from their
                                                            vendor payments and provides detailed          bank account.
                                                            payment-related remittance information to         “This is part of our ongoing commitment
                                                            the vendor.                                    to offer Canadians a broad range of fast
                                                               US Bank executive vice-president            and secure payment options, including the
                                                            and chief innovation officer Dominic           convenience of paying with their mobile
                                                            Venturo said: “Organisations are looking       device,” O’Connell added.
                                                            for payment solutions that solve real-life        Samsung COO and executive vice-
                                                            challenges. With Disbursements via Zelle       president Paul Brannen commented:
                                                            and Supplier Prefer Pay we make payables       “We’re happy to expand our Samsung
                                                            more secure and efficient for business         Pay offering to Interac Debit customers
              US Bank has rolled out two new digital        clients by eliminating the upfront effort      throughout Canada and offer them a
              payment solutions, Disbursements via          required to obtain the payees’ banking         seamless mobile payment solution that is
              Zelle and Supplier Prefer Pay, which enable   information.”                                  simple, safe and convenient.”
              corporate and commercial banking clients         US Bank executive vice-president and           Interac branded products and services
              to shift from paper to electronic payments.   head of global treasury management Rich        are currently offered by Interac Association
                 The payment solutions reduce the           Erario said: “US Bank continues to be a        and Acxsys, which together operate a
              time and risk involved in the process of      leader in financial services innovation.       debit system in Canada. In 1996, the
              soliciting, storing and maintaining banking   These solutions are examples of how US         original architects of the Interac network
              information for business and individual       Bank is innovating using new payment           created Acxsys to develop new business
              payees.                                       technology to provide clients with effective   partnerships and new services and
                 Disbursements via Zelle allow companies    ways of optimising working capital and         take advantage of opportunities in the
              to transfer funds to individuals using a      reducing overall processing costs.” <          marketplace on a competitive basis. <

   8 | December 2017 | Electronic Payments International

EPI December 366.indd 8                                                                                                                        09/11/2017 17:31:38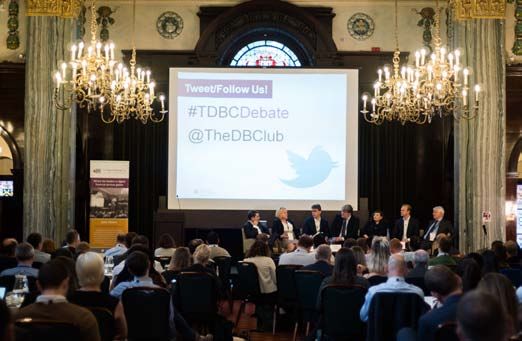
feature | dbc debate

                                                                                                                  consumers about the benefits of open banking
                                                                                                                  and sharing data in a responsible way.

        will open banking                                                                                            “Unless we do this, the customer interface
                                                                                                                  will be hijacked by the social media

        breathe new life
                                                                                                                  companies. If we do this as an industry
                                                                                                                  correctly then we will continue to own the
                                                                                                                  interface. If we do not, it may go to Google,
                                                                                                                  Facebook and the rest.”

        into the industry?
                                                                                                                     Roberto Ferrari, chief digital and
                                                                                                                  innovation officer at Mediobanca group, said:
                                                                                                                  “Open banking will force banks to use the
                                                                                                                  data they have to its full potential.”
                                                                                                                     In agreement with Ferrari was TSB Bank’s
                                                                                                                  digital innovation and transformation director,
        With the deadline for PDS2 just around the corner, banks                                                  Pol Navarro, who argued: “Open banking and
        and fintechs must be prepared for the challenges it brings as                                             the introduction of PSD2 is pushing banks to
                                                                                                                  become more oriented towards the customer.
        well as the opportunities that come with it. Briony Richter                                               Customers seek good experiences from their
        reports from the latest Digital Banking Club debate                                                       banks.”
                                                                                                                     Asked if TSB is approaching this from
                                                                                                                  the mindset of an incumbent or challenger,

         W
                     ill open banking really               there is a little reservation. Is it really going to   Navarro said: “We are a challenger. We at
                     be transformational? The              live up to its promises? Do consumers really           TSB are making sure that we can take full
                     latest Digital Banking Club           understand it and will they embrace it? It is          advantage of the data we receive.”
        debate of 2017, powered by Intelligent             quite a confusing time for a lot of people, and           Jenkins argued that data is important, but
        Environments, discussed just that.                 it needs to be carried out carefully.                  customers must always come first. “Data is
          Hosted at the formidable Law Society in              “If customers allow it, licensed AISPs             the fuel, but you have to think carefully about
        London, the debate featured an outstanding         [Account Information Service Providers] and            the customer experience and what their needs
        panel to debate the challenges and                 PISPs [Payment Initiation Service Providers]           are. We need that creativeness coming into
        opportunities posed by the implementation of       will enjoy unprecedented access to a platform          the industry to give our customers something
        open banking.                                      on which they can develop entirely new kinds           of value. Often, customers are a little anxious
                                                           of products, services and experiences.”                about open banking.
        Why is it a good time to be discussing                 Anne Boden, CEO of Starling Bank and                  “We need to ask ourselves, how are we going
        open banking?                                      the 2017 Digital Banking Club Power 50                 to get customers to trust us with their data as
        Simon Cadbury, director of strategy and            Personality of the Year, added: “It could              much as they trust us with their money?
        innovation at Intelligent Environments, began      completely change retail banking forever                  “We have to answer this together. We have
        the debate by expressing his thoughts on the       – if it happens. There is a huge amount of             to think about putting the customer first.
        introduction of open banking.                      opportunity out there but implementing it in           Some big banks may naturally want to hold
           He said: “It is the topic on everyone’s lips.   traditional banks could prove difficult.               onto their customer base, but collaboration
        The most interesting thing for me is that              “The opportunities that PSD2 will open             is the way forward. If we do it securely with
        every article I read and everyone I speak to is    up are great; they are good for consumers,             APIs then it really could be phenomenal. ”
        incredibly positive about open banking.            but those changes actually attack the heart of            The panel were all agreed that open banking
           “I agree that it is a very exciting time, but   banking as it is at the moment.”                       has great potential – if harnessed with the
        actually when you scratch beneath the surface          Hilda Jenkins, digital experience and              right tools.
                                                           engagement director at Barclays, argued that
                                                           it is the customer that should be the priority.
                                                           “The way we go about it has to put the
                                                           customer at the centre of everything. The big
                                                           banks, the fintechs are all looking to come in
                                                           and create new ways to excite our customers.
                                                           If we do that then it can only be a good thing
                                                           for all of us.
                                                               “At Barclays we put the trust of our
                                                           customers first. If data is shared securely and
                                                           open banking is approached in a mature way
                                                           by all, then it could work.”
                                                               Boden emphasised this point: “Customers
                                                           should come first and they should own their
                                Hilda Jenkins, Barclays    data. It is up to the industry to educate                             Roberto Ferrari, Mediobanca

                                                                                                          www.electronicpaymentsinternational.com | 9

EPI December 366.indd 9                                                                                                                                      09/11/2017 17:31:40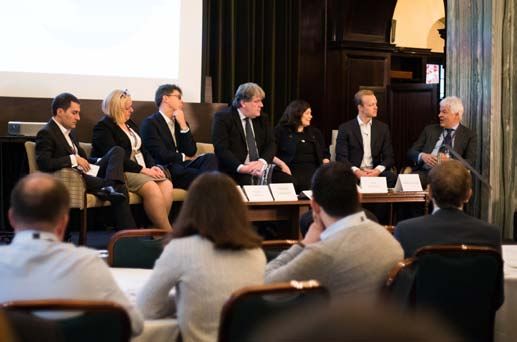
feature | dbc debate

              Will open banking live up to expectations?            “Traditional banks are in the driving seat,      to create different types of data. With these
              On the topic of whether open banking is more       but if they hesitate, technology heavyweights       partnerships we can marry the data gained
              exciting in business than in other sectors, Will   like Google, Amazon, Facebook and Apple are         from them with the data we already hold.”
              Beeson, head of operations and innovation          well placed to take advantage of PSD2.”                Cadbury said: “I hope the challenges are
              at Civilised Bank, stated: “It is very exciting.      Navarro stated: “In the long run it will         overcome and there is success, but I do fear
              There is much broader competition. Banks are       really change the banking industry. If you give     that the big brands have an advantage at this
              doing it because of the changing expectations      good, trustworthy customer service then the         time.”
              from customers. Also, if you look across           customers will continue to come again.”                Boden added: “The big banks will be
              the industry you are seeing fewer and fewer           PSD2 follows on from PSD, and could              pushed to be more creative and make more
              standalone banks wanting to own 100% of            essentially revolutionise the banking and           investments in things that make the customer
              customer services.                                 payments industry, affecting everything from        happy. New entrants will drive innovation
                  “It will be much faster to deliver with        the way we pay online to the information            and creativity, and hopefully everyone will get
              collaboration, and there will be more              that can be seen when making a payment.             a better deal if it works. We must, however,
              comprehensive services for customers.”             Adapting to these new regulations will              educate our customers in what all this will
                  Boden reiterated the need for collaboration,   need significant levels of investment and           mean for them.”
              saying: “We envisage a world where people          commitment from the banking industry.                  Navarro believed that it will be the
              like us will provide the business current             Boden talked about the differences that          customers that will benefit the most from
              account, and then customers can use APIs to        consumers will all see with PSD2. “With PSD         open banking. Ferrari agreed, but emphasised
              get access to other services. We can provide       we didn’t have all these new players providing      that it is essential to have the right architecture
              an alternative and different value chain to the    people with specialised services. PSD2 is going     from the top to the bottom of the bank.
              traditional banks.”                                to do that. It has the infrastructure to join up       Beeson said the winners will not necessarily
                  Customer expectations are at the heart         new services to old services. It is going to link   be specific companies or individuals, but those
              of the debate; they are the main driver for        the incumbent and traditional banks in new          who are prepared.
              implementing the changes needed.                   and interesting ways.”                                 He stated: “Regardless of bank or non-
                  Ferrari argued that the expectations of           For consumers who hold more than                 bank, incumbent or new entrant, the winners
              customers are clear: They want top service         one bank account, the changes will allow            will be those that have efficient, scalable, open
              from their banks. Ferrari stated: “Banks are       businesses and providers to show all their          architecture. The losers will be the ones that
              data companies, therefore money and banking        account information in one place. Of course,        do not. There are so many factors that are
              is about data.                                     along with these changes come much stronger         changing and there will be pressure to make
                  “There are very high expectations from         security checks to ensure safe customer             changes.”
              customers. You can see this from the rapid         payment.                                               A question from the floor – again the DBC
              uptake in mobile banking globally. In the end                                                          debate played to a full house – referenced
              it is what you give to them.”                      Who will be the winners and losers?                 seven-day switching and why, as customers,
                  As well as customer support, open banking      With high expectations for all players across       we should switch our accounts for, potentially,
              will also be beneficial to banks and fintechs.     the board, the panel were asked who will be         another average experience. What unique
              Cadbury emphasised how the business banker         the ones that stand up to the challenges and        experience do the panel have to offer?
              has more to benefit from in the short term,        overcome the hurdles.                                  Beeson began by stating that Civilised
              but must look to the future in order to secure       Jenkins stated: “This is the time to be in        Bank’s unique experience would be “delivering
              customer loyalty.                                  banking. These new laws are exciting for            a face-to-face human interface that would be
                  “The open banking component of PSD2            us and our customers. Of course the big             the single point of contact for all of the bank’s
              is nothing less than an invitation to rethink      banks will embrace it. We want to keep our          resources”.
              banking. The walled gardens that banks have        customers and keep them satisfied.                     Boden added that when customers come
              built around their customers’ data will start to     “We need to innovate and take hold of the         to Starling Bank it is because they want that
              crumble. The customer loyalty that banks have      opportunities opening up. Barclays has been         unique experience, and the mobile app it
              spent fortunes to build could be challenged.       opening up to partner with small players            provides does just that.

   10 | December 2017 | Electronic Payments International

EPI December 366.indd 10                                                                                                                                      09/11/2017 17:31:42
feature | dbc debate
and seeing other banks, retailers or tech
companies eat their lunch.
“Equally, there is a risk of overestimating
the impact of PSD2 and wasting resources on
it, to the detriment of some other left-field
advance such as machine learning.”
Cadbury also highlighted that customers
might not want PSD2. “Some customers like
to compartmentalise their financial interests,
particularly their debts.
“For some this is a matter of security or an
insurance against fraud, for others it’s simply
IE’s Jerry Mulle with Anne Boden because they don’t want their bank to have Jerry Mulle with Will Beeson
a full picture of their financial lives. Services
“We built all the functions into the mobile built on the back of PSD2 will have to all fits together. If open banking can help in
app. We did get an incredible number of overcome this to succeed.” a way that is safe, secure, and does not abuse
people switching over in the first couple of Carrying on the importance of educating data, then I think it could be a very powerful
weeks. People want something different and consumers, Boden stated: “I believe it comes thing.”
unique. I believe the seven-day switch works. down to education again. Using methods that Speaking about the opportunities of
“By providing the right infrastructure, are sophisticated will help customers connect GDPR, Jenkins said: “It is a great opportunity
delivering interesting products and a number with their data and systems. – how we leverage the trust in our customer
of relevant partners, we can gain new “We must educate people that it is safer base and use the enhancement of privacy
customers and keep the loyalty of our existing to have all their information stored in one laws that GDPR is bringing. It is important
ones,” Boden noted. place, with trusted institutions, and use those to approach it responsibly and expose it to
services to log on to other providers.” customers in a way that they can enjoy.”
Risks and hurdles Ferrari agreed that it is important to let Cadbury concluded: “Open banking is a
Open banking does not come without customers know how their data is being used, revolutionary concept in financial services,
conduct risks. In particular, many customers and from where it is being accessed. “We need but not in the technology sector. Open APIs
are very concerned about their security and to be much more transparent. The technology are the driving force behind the Internet of
data privacy. to prevent fraud and hacking will become Things and an essential feature of almost all
Jenkins discussed the importance of much more relevant, and we need to be successful online platforms – from Twitter and
guiding consumers through the process of prepared for that.” Expedia to Amazon and Uber.
open banking. “We want to embrace open Navarro also emphasised that an important “As banking goes digital, an API-driven
banking in the right way, building APIs and part of it is down to communication. future is as inevitable as the internet-driven
encouraging customers not to share their log “Security in banks has been good, and it is present that precedes it.
in details. Barclays has just launched a major all about the evolution of technology. What “It is the opinion of Intelligent
campaign around being digitally safe, and that we do need to do is communicate to our Environments that PSD2 could sustain
is to educate consumers that come into our customers that we are secure. We have not entirely new business models, but that
bank on the right way to engage in this digital done that well, and so we must sell it better.” regulation needs ultimately to go further –
world. encompassing all account types and financial
“What has to be understood is that there Killer features data – to make open banking the revolution it
are different types of customer, and we have to A question from the audience asked, what will could be.”
provide for everyone across the demographics. be the killer feature that attracts customers? The panel all agreed that open banking
There are a lot of older customers who are Boden believed it will not come from is incredibly exciting and innovative. There
more vulnerable, and a lot of young people the banks. She said: “I don’t think that the are hurdles to overcome, but with the right
and millennials that are more savvy but do killer feature will come from the industry amount of collaboration, security and
not necessarily think about it on a day-to-day or incumbents. That killer feature will come creativity, open banking can be something to
basis, so a bank has to be about protecting all from people who build applications upon our look forward to as the next step in banking
of our customers.” infrastructure. Banks cannot fail: If a project is and payments.
Cadbury said that open banking does come started it must finish successfully. Following the Digital Banking Club debate,
with risks and, when speaking to clients about “With open infrastructure, with the Power 50 winners were invited onto the
open banking, the advice given is to start processes and procedures to vet people and the stage to receive their awards, presented by
off small and build from there; that way the chance to use APIs with hundreds of people Jerry Mulle, sales and marketing director at
customer will not be giving away more data innovating, there will be breakthroughs. Those Intelligent Environments.
than is necessary. breakthroughs will come from someone using Categories for the awards were: Personality
On the risks, he stated: “Because of its the possibility of putting data together to of the Year, Digital Financial Services Power
open-endedness, open banking comes with create good.” 50, Digital Financial Services Rising Stars,
substantial risks. There is a risk of banks Cadbury said: “I’m very excited, potentially, Digital Innovation in Collections, and Digital
failing to embrace the opportunities of PSD2 to see all my money in one place and where it Innovation in Vehicle Finance. <
www.electronicpaymentsinternational.com | 11
EPI December 366.indd 11 09/11/2017 17:31:44feature | digital ID
australia post
develops national
digital ID Scheme
Australia Post has launched a smartphone-based national
digital ID scheme. However, until it gains a significant
number of partners, particularly in the banking sector, the
idea may see limited adoption. Robin Arnfield reports
I
n August 2017, government-owned number of users, aims to provide secure ways Post’s data to increase the ability to verify
Australia Post announced Digital iD, for Australians to identify themselves when those individuals is a huge step forward.”
a free service allowing Australians to using digital government services. Users will “CUA is looking to begin a pilot within
verify their identity online and in person be able to prove themselves by having an the coming weeks, trialling Digital iD on
when accessing government and business accredited organisation vouch for them such its online and mobile application forms
services. as a government agency, or in the future, their for two savings accounts: the CUA eSaver
Australia Post says the service allows people bank, the DTA says. Boost and eSaver Reward accounts,” a CUA
to verify their ID once, so they can then easily The DTA expects to have digital ID services spokesperson tells EPI.
prove who they are online and in person available for a broader group of users to test “The pilot is likely to run for around 12
through the Digital iD app. This removes on a wider number of government services in weeks, so CUA can collect feedback on
the need for people to repeatedly use several the first half of 2018. the Digital iD experience and identify any
forms of ID to prove who they are, or have potential refinements or improvements.
numerous passwords to access products and PARTNERS Following the pilot, CUA will consider
services, it says. potentially expanding Digital iD to other
Australia Post’s research has found that The first organisations to sign up for Digital products. This may include verification for
existing time-consuming ID verification iD are job outsourcing site Airtasker, other transactional and saving accounts, term
processes cost the Australian economy up to Australia’s largest credit union, CUA, deposits, credit cards or personal loans. CUA
A$11bn ($8.4bn) a year, Andrew Walduck, Travelex Australia, and the Queensland Police may also explore the use of Digital iD to
Australia Post’s executive general manager, Service. Consumers can use Digital iD when allow members to identify themselves over the
trusted e-commerce services, said. registering online for Australia Post services phone or in a branch.
In May 2017, Australia Post said that such as MyPost Parcel Collect and Mail “At this stage, CUA hasn’t explored whether
it was partnering with Australia’s Federal Redirection. to utilise Digital iD for logging into digital
Government to ensure that Digital iD can Airtasker will use Digital iD to give its users services, such as online or mobile banking.
be used to access the government’s digital an identity ‘badge’ to prove who they are, However, this may be an area for further
services. strengthening trust in its service. consideration following the Digital iD pilot
“Australia Post will work with the CUA will initially use the technology to and the upcoming launch of CUA’s new
Government’s Digital Transformation Agency verify new members applying for CUA eSaver mobile banking app.”
(DTA) to integrate Digital iD into the Reward or eSaver Boost savings accounts Travelex will use Digital iD as part of its
Commonwealth of Australia’s Digital Identity online or via smartphone, enabling more KYC checks, while the Queensland Police
Framework, a set of standards, processes people to complete the process digitally Service will incorporate the technology into
and partnerships guiding the government’s without visiting physical branches. its forthcoming national police clearance
formation of a federated system of ID “We see [Digital iD] as a tool to help us certificates process.
providers,” it said. support members through life events – like Travelex plans to integrate Digital iD
“The partnership between Australia Post moving house – with a better way to have within its online currency ordering systems,
and the DTA will focus on developing a their identity verified,” says CUA chief digital providing KYC for online orders at Travelex.
proof of concept to help government agencies officer Sue Coulter. com.au where customers do not visit a
enhance how they provide access to services “Changing addresses is one of the most Travelex store, Travelex online country
online and over the counter.” common reasons that people are unsuccessful manager James Vatiliotis says.
The DTA’s Govpass project, which is in in verifying their identity as part of an online “We’re currently rapidly developing our
beta development and testing with a limited application. So being able to tap into Australia solution for Digital iD, and hope trials will
12 | December 2017 | Electronic Payments International
EPI December 366.indd 12 09/11/2017 17:31:47feature | digital ID
start before the New Year and a full-scale allow a national program to be built? on partnerships that SecureKey has established
rollout early next year,” he says. “Digital iD “The organisations currently signed up for for SecureKey Concierge, an authentication
will really enhance our fulfilment offering Digital iD will use it for a mix of unrelated service enabling Canadian consumers to log
and allow us to offer a home delivery solution tasks,” Halverson continues. “There are no into multiple Canadian government services
similar to Travelex’s offerings in UK, US and banks or insurance companies and no other using their bank ID. All major Canadian
Japan. Digital iD also starts a new fulfilment top 200 companies. The key issue for banks banks participate in SecureKey Concierge.
journey as we look to automated fulfilment. is whether Digital iD will replace existing “We’re currently undergoing market
“What this looks like is still being explored, forms of ID and/or credit checks: this is most trials of the new digital network and are
however. But with Digital iD there are some unlikely. A better model is what Estonia has aiming for commercial launch in early
exciting possibilities to make our customers’ done with digital citizenship and digital ID 2018,” says SecureKey’s Boysen. “We’ll have
lives easier. For example, we’re exploring using all being driven by the Estonian Government. banks, government departments and telcos
Digital iD to provide a second level of KYC However, this government-issued digital ID participating as digital ID providers in our
above our current KYC checks.” model suffers if you have to scale it in larger Canadian network.”
To sign up for Digital iD, consumers populations.”
download the associated app to their Android “Without the involvement of Australia’s DIACC
smartphone or iPhone and enter their big banks, Digital iD won’t get large numbers
personal data from their passport or driver’s of users,” says Andre Boysen, chief identity The Digital ID and Authentication Council
licence. The Digital iD system compares this officer at Toronto-based SecureKey, which of Canada (DIACC) is a non-profit coalition
data with the information kept on the ID is working with Canada’s banks to build a of public and private sector organisations
document issuer’s database to verify the user’s nationwide digital ID scheme in Canada. committed to developing a Canadian
identity. “From the consumer perspective, Digital iD digital ID and authentication framework.
Australia Post says that when someone uses has limited usage potential. Without multiple A standards-setting body, the DIACC’s
Digital iD, a verified token showing that the partners, people won’t want to sign up for it. members include representatives from federal
customer is who they say they are is passed to What’s the use of a credential I can and provincial government as well as
the relevant organisation. Only information only use at one organisation? private sector firms.
authorised by the customer – such as name, I might as well get the In February 2017, the
address and date of birth – is passed on. Users’ credential direct from that DIACC and SecureKey
identity data is stored within an encrypted organisation. Consumers were awarded a grant
system located in Australia. want to not have to do of up to $800,000 to
“Data is encrypted and stored with two digital ID verification at develop a Cloud Identity
keys, both of which are needed to unlock the every service.” Ecosystem. The DIACC
user’s personal data,” Australia Post says. “One The Reserve Bank of said it will work with
key is held by Australia Post and the other Australia’s Payments Systems SecureKey to develop the
is on the user’s secure device. Both keys are Board’s August 2017 meeting digital security framework
required to unlock the user’s data; neither the discussed “the potential for a based on SecureKey’s technology
user nor Australia Post can access the private framework for trusted digital identity architecture.
data without the other.” to make online interactions more convenient The grant is the result of collaboration
Australia Post has created a developer centre and secure, including the potential to reverse between DIACC and the Command Control
providing a sandbox environment where the rise in fraud rates on card transactions”, and Interoperability Center for Advanced
developers can test Digital iD on behalf of the RBA said in a statement. Data Analytics, a research centre funded by
organisations interested in using the system. “Board members encouraged the payments the US Department of Homeland Security
“The sandbox environment allows industry to work collaboratively on digital Science and Technology Directorate.
technology teams to perform all the operations identity and noted the importance of In the US SecureKey is setting up a
available in the production environment engagement between banks and government consortium of US banks, government
using fictitious identities and verifications,” it on this issue.” departments and telcos to build a federated
says. “This means technology teams can fully By contrast with Australia Post, Canada digital ID network. SecureKey’s long-term
test the end-to-end process of verifying an is further down the road to building a goal is to link digital ID networks in different
identity.” nationwide digital ID network. In October countries that use its platform.
2016, SecureKey raised C$27m ($21m) in “The problem with national digital ID
COMMENTS growth capital to fund the commercial rollout schemes is that they aren’t interoperable with
of a nationwide federated digital identity each other,” Boysen says. “Our vision is to
“The key issue is whether consumers trust network in Canada. The country’s largest establish national digital ID schemes using
Australian Post,” Grant Halverson, CEO of banks, BMO Bank of Montreal, Scotiabank, our technology in two or three countries,
Australian payments consultancy McLean CIBC, Desjardins, RBC Royal Bank of and then use this as the catalyst for a global
Roche, says. Canada, and TD, participated in the funding. interoperable digital ID system.
“Will consumers be proactive in registering In October 2017, SecureKey said Quebec- “This global platform will be cross-border
and will they remember they have an Australia based National Bank of Canada would but will respect the fact that individual
Post digital ID when they need it? Will participate in its new digital ID network along countries require their citizens’ ID data to
Australia Post build enough critical mass to with the other big banks. This platform builds reside in-country rather than offshore.” <
www.electronicpaymentsinternational.com | 13
EPI December 366.indd 13 09/11/2017 17:31:49feature | fiserv
Payment hubs were a major industry theme
the three things around 10 years ago, but as the API provided
an alternative to large payment hub
set to change
implementation, discussions on international
payment hubs have emerged. Is this going to
be the next big payments theme?
TL: While payment hubs emerged as an area
payments forever
of focus among larger institutions nearly a
decade ago, the capability of payment hubs are
even more applicable to medium and smaller
financial institutions today. Banks of any size
can benefit from fewer systems than are in
use to support the payment needs of today.
Payments is a quickly changing sector; with cryptocurrencies, We have several medium-sized bank clients
the Internet of Things and APIs, a lot is happening. Patrick that have embarked on a payment platform
Brusnahan spoke to experts from Fiserv to see how payments journey this year, including the recently
announced Hellenic Bank.
will develop in the coming years. What is set to make a I disagree that APIs are an alternative
permanent impact, and what will be a damp squib? to payment hubs. APIs are fundamentally
different. APIs can expose the underlying
EPI: On 22 September, JPMorgan CEO Jamie Deva Annamalai, director, innovation payment application in a new way, but if
Dimon strongly criticised bitcoin and digital and client engagement, digital banking: the application is not capable of processing
currencies once again. Is there any potential We are seeing bank customers making more multiple transaction types you will still need
or value in virtual currencies? recurring and subscription-based payments. multiple applications.
Marc West, chief technology officer: It is too In addition to regular payments for services This is back to the old spaghetti of siloed
early in the digital currency evolution to make such as utilities – electricity, cable, gas, water systems and is a Band-Aid approach that
a clear call on how they can be of value in the – consumers are signing up for subscription- simply increases costs and delays innovation.
traditional banking market. based services that require recurring payments. In addition, exposing APIs to the wider world
The combination of regulatory These services are starting to proliferate in is difficult with legacy systems, so we see a
requirements, central bank needs and everyday life – Netflix, Spotify, YouTube Red, number of our customer looking at doing this
consumer demand are key drivers of potential Amazon Prime and Hulu are examples. The with the underlying capability of a modern
use. Said simply, while there is a likely fit for subscription model is moving beyond content payments platform.
purpose, the demand-driven use cases are not consumption to other areas like shopping –
at the level to compel action right now. such as Bombfell, Trunk Club, Birch Box. One area of focus for payment innovation is
An average customer is also starting to the Internet of Things. What type of horizon
Many banks are engaged in proof of concept, prefer services that make the payment step do you foresee for this?
pilots and some early rollout. Do your client ‘disappear’. Uber and Amazon Go do this very DA: The IoT represents a relatively new way
banks see value in blockchain and if so, in effectively, and we expect this payment format of how people will experience payments via
which areas? will continue to spread, driven by consumers’ interaction with physical objects around
MW: We see realistic use cases in identity desire for convenience and time savings. them. We are seeing an influx of connected
management, data sharing and lending. Pilots Trevor LaFleche, vice-president, product devices, and it is only a matter of time before
are evolving from exploration to simplification marketing and analyst relations, billing these become a staple in the financial services
of complex processes. and payments group: The advent of real- industry. Aite group projects that the IoT will
time payments in the P2P and B2B space is grow to around 30 billion devices by 2020
Would a distributed ledger be suitable fundamentally changing the way people pay. and more than a 100 billion by 2050. As
at central bank level as a clearing Initiatives in Europe, the US and Asia are more value-added services become part of the
infrastructure? focused on the transmission of ‘good funds’ in IoT, the ability to pay for those services will
MW: With the right regulatory and central real time, which is a preferred target state over become an increasingly integral part of the
bank environment and involvement, existing methods. ecosystem.
distributed ledger technologies can enhance As a result of the move toward real time, In the next decade we will start seeing IoT-
country clearing functions. banks are being forced to evaluate payment, enabled usage-based payments permeating
However, it is clear that high-value market- channels and even core banking capabilities our everyday lives, be it our connected car
driven use cases, created by the combination to ensure the proper support is in place. In paying for gas at the pump or our refrigerator
of regulatory requirements, central bank needs addition, moving good funds in real time ordering a carton of milk. In order to thrive,
and consumer demand noted above, will be means fraud, risk and liquidity need to be those offering payment services need to
critical to creating a mass opportunity. evaluated in real time. All these changes are evaluate and understand how their customers
needed to match the increasing consumer want to interact with this type of technology,
How do you see client banks’ customer bases expectations, and are not a trivial project for a and more importantly how to ensure the
changing their payment usage and needs? financial institution. security of payments made via the IoT. <
14 | December 2017 | Electronic Payments International
EPI December 366.indd 14 09/11/2017 17:31:50You can also read


