Profile of heating and cooling demand in 2015 - D 3.1 2017 This project has received funding from the European Union's Horizon 2020 research and ...
←
→
Page content transcription
If your browser does not render page correctly, please read the page content below
Profile of heating and
     cooling demand in 2015

                                D 3.1

                                 2017

                     This project has received funding from the European
                     Union's Horizon 2020 research and innovation
                     programme under grant agreement No. 695989.

www.heatroadmap.eu                                                @HeatRoadmapEU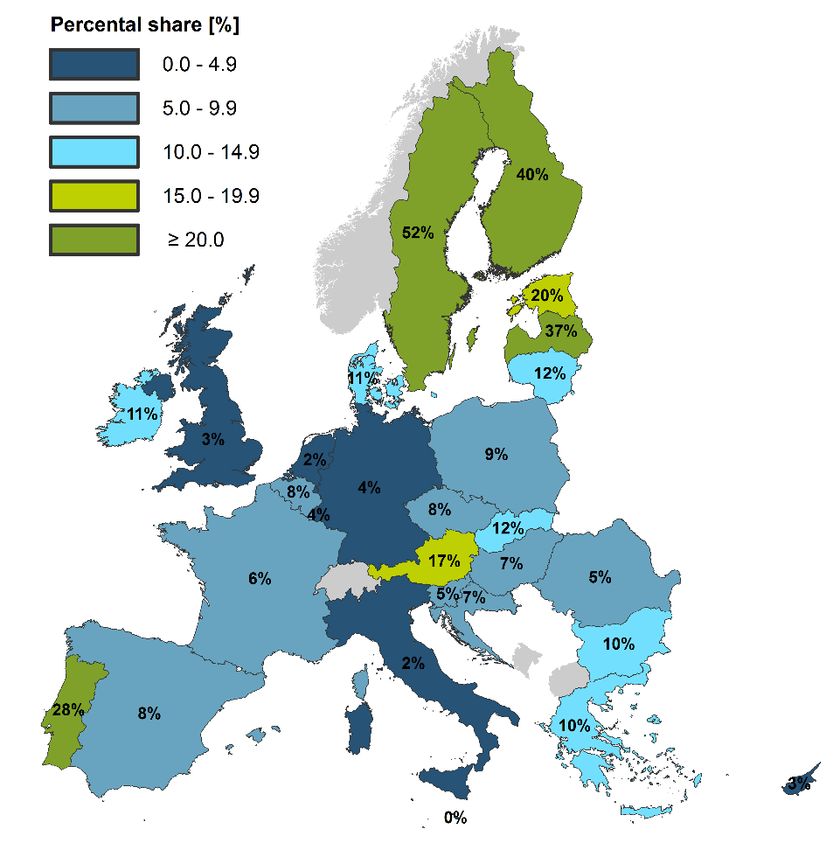
Authors:    Tobias Fleiter, Rainer Elsland, Matthias Rehfeldt, Jan Steinbach (Fraunhofer ISI)
            Ulrich Reiter, Giacomo Catenazzi, Martin Jakob (TEP Energy GmbH)
            Cathelijne Rutten, Robert Harmsen (University Utrecht)
            Florian Dittmann, Philippe Rivière, Pascal Stabat (ARMINES)

Contact:    Tobias Fleiter
            Fraunhofer Institute for Systems and Innovation Research
            Breslauer Str. 48
            76139 Karlsruhe
            Germany

            E-mail: Tobias.Fleiter@isi.fhg.de
            Heat Roadmap Europe website: www.heatroadmap.eu

Deliverable No.          D 3.1: Report
                         © 2017

                            This project has received funding from the European Union's Horizon 2020
                            research and innovation programme under grant agreement No. 695989. The
                            sole responsibility for the content of this document lies with the authors. It
                            does not necessarily reflect the opinion of the funding authorities. The funding
                            authorities are not responsible for any use that may be made of the
                            information contained therein.

2
www.heatroadmap.e                                                                  @HeatRoadmapEU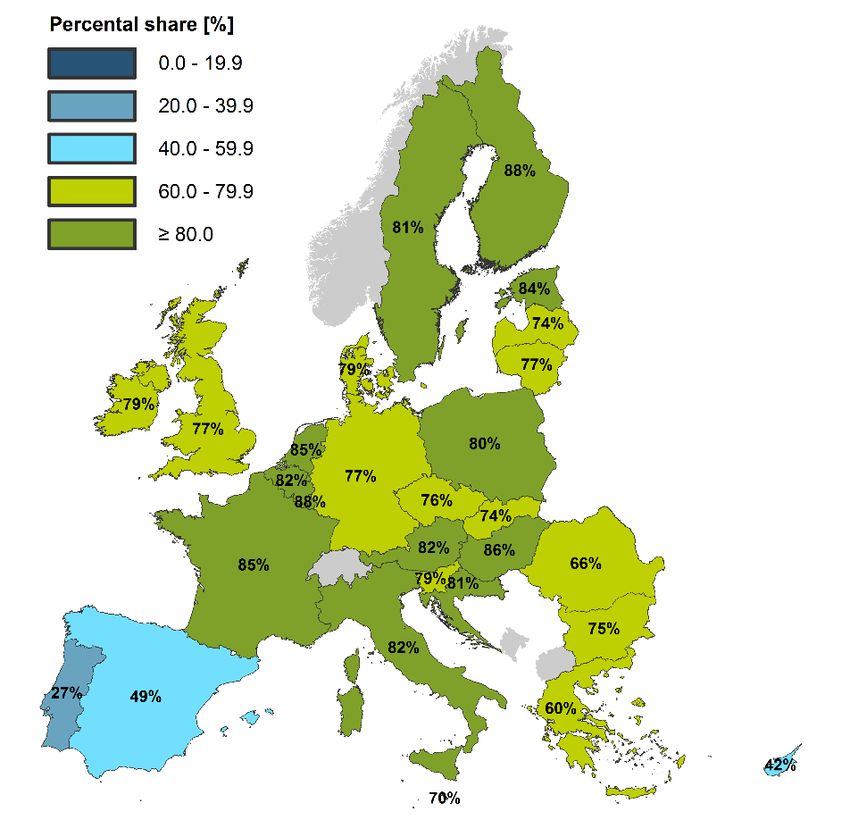
3
www.heatroadmap.e   @HeatRoadmapEU
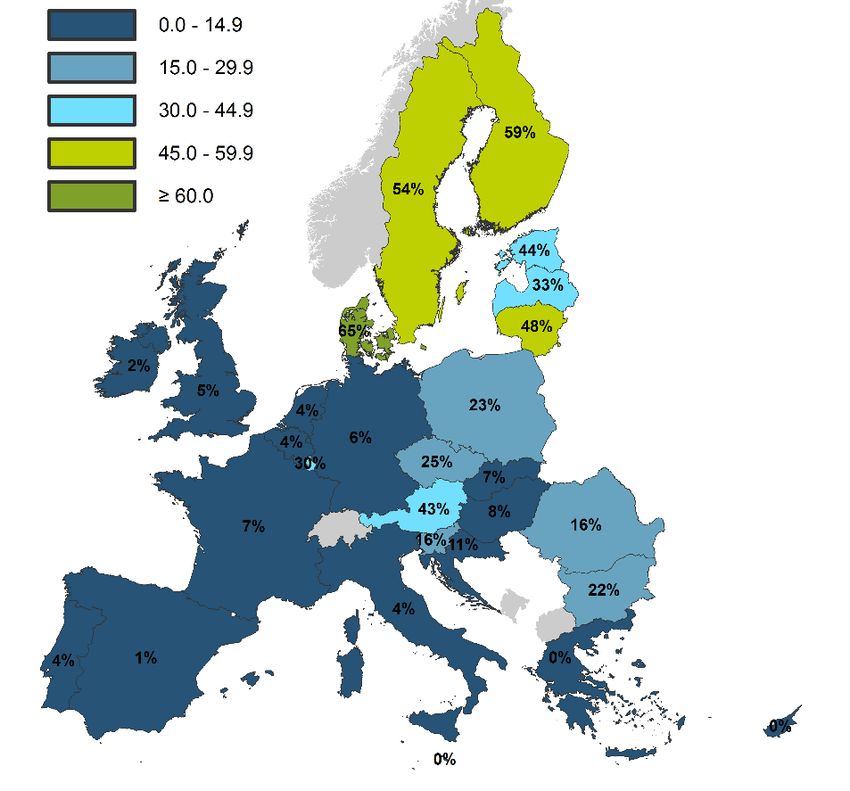
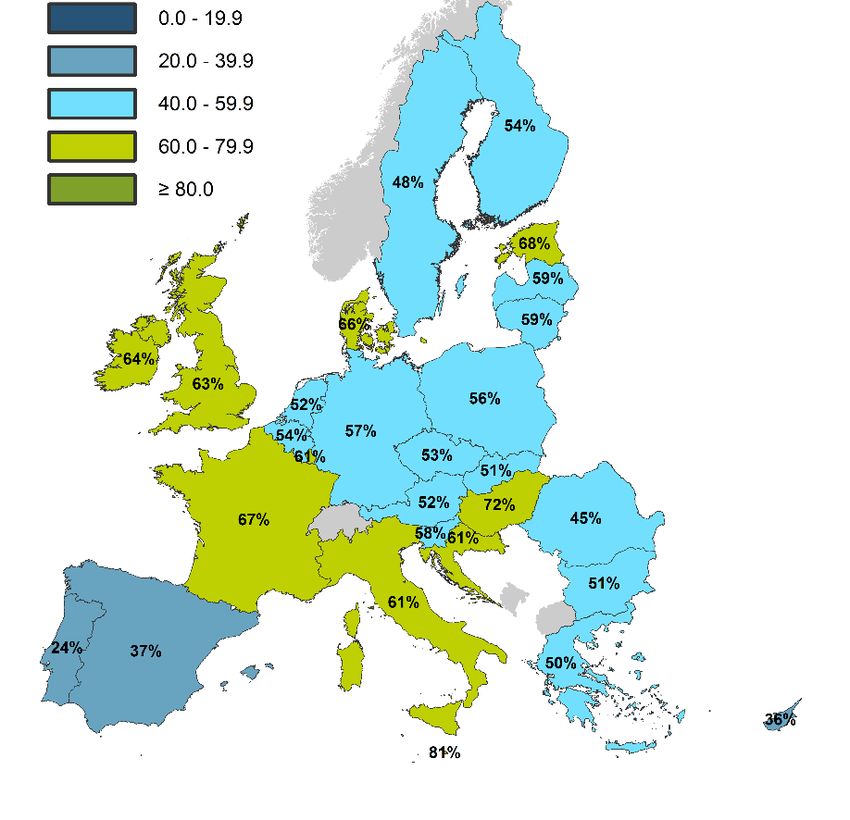
Table of Contents
 1.          Introduction ..........................................................................................3
 2.          Method, definitions and data sources ........................................................6
      2.1.        Method ...........................................................................................6
      2.2.        Definitions ......................................................................................9
      2.3.        Data sources ................................................................................. 13
 3.          Summary of main results ...................................................................... 14
 4.          References ......................................................................................... 16

                                                                                                                   1
www.heatroadmap.eu                                                                          @HeatRoadmapEU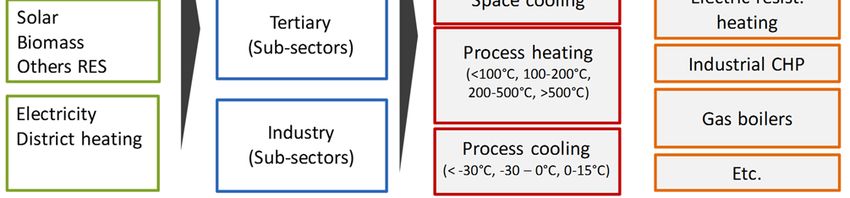
2 www.heatroadmap.eu @HeatRoadmapEU
1. Introduction
In Europe, there is a clear long-term objective to decarbonise the energy system, but
it is currently unclear how this will be achieved in the heating and cooling sector. The
Heat Roadmap Europe (HRE) project will enable new policies and prepare the ground
for new investments by creating more certainty regarding the changes that are
required. Heat Roadmap Europe is co-funded by the European Union, brings together
24 academic, industrial, governmental and civil society partners, and runs from 2016-
2019.

The overall objective of the HRE project is to provide new capacity and skills for lead
users in the heating and cooling sector including policymakers, industry, and
researchers at local, national, and EU levels by developing the data, tools, and
methodologies necessary to quantify the impact of implementing more energy efficiency
measures on both the demand and supply sides of the sector.

This WP3 report presents a breakdown of both the demand and supply of heating and
cooling energy for the year 2015 and thus provides the starting point for the scenario
analyses up until 2050.

Conventional energy balances (both national and Eurostat) generally provide the final
energy demand split by sector (residential, industry, tertiary and transport), energy
carrier and also by sub-sector for industry. They do not usually provide information on
end-uses such as heating, cooling, mechanical energy or useful energy (i.e. the heat
that is used by the consumer, e.g. for heating a room). A recent review found that
several EU countries provide end-use balances for the residential sector and some for
the tertiary sector, but only three countries do so for the industry sector (United
Kingdom, Germany and Austria) (Fraunhofer ISI et al. 2016). However, the method and
definitions used in the various countries deviate from one another and it is not possible
to derive a consistent EU-wide end-use energy balance simply by combining national
data (Fraunhofer ISI et al. 2016).

As a consequence, the energy demand for heating and cooling (H/C) cannot be derived
from the currently existing official energy balances in a consistent way for all EU
countries. Neither is it possible to calculate the share of renewable energies in H/C
without simplification as done, for example, in the SHARES project1, which excludes all
electricity consumption from H/C energy use. This approach does not provide accurate
results in many countries.

Therefore, this deliverable aims to profile the energy demand for H/C by calculating
energy balances for all 28 EU countries that include H/C. However, the focus of the
analysis and input-data quality checks is on the 14 EU countries with the highest H/C
demand as in the other HRE deliverables. The remaining 14 countries were added so

1
    http://ec.europa.eu/eurostat/de/web/energy/data/shares

                                                                                       3
www.heatroadmap.eu                                                    @HeatRoadmapEU
that figures could be presented for the entire EU28. The balances are based on the
same method applied across countries, which should make them comparable and
consistent. The approach used combines empirical data, e.g. market shares, industrial
production or technology stock with bottom-up model simulation to derive energy
demands for 2015. The bottom-up model FORECAST2 is used for this purpose.

2015 was chosen as the start year for scenario development in the HRE4 project so the
H/C profile is also developed for 2015. This poses a few challenges related to data
availability. At the time of calculating the 2015 profiles, there was no final energy
demand balance available from Eurostat, which is ideally used for calibration. Other
input data are also only available for earlier years (e.g. industrial production statistics).
As a consequence, we calculate the 2015 heating and cooling profiles based on model
runs that begin in 2012.

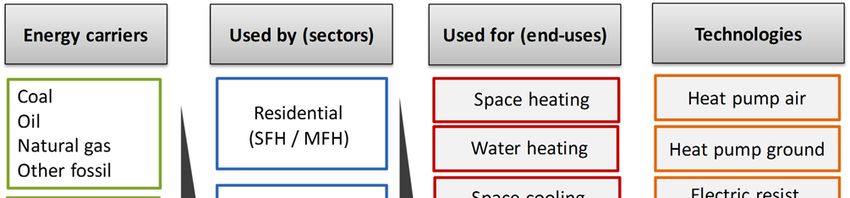
SFH = Single-family house; MFH = Multi-family house, CHP = combined heat and power, RES= Renewable energy sources

Figure 1: Overview of disaggregation of H/C profiles by country (based on Fraunhofer ISI et
al. 2016)

The H/C profiles comprise all the elements also included in the Eurostat final energy
balances (e.g. energy carriers and sectors). They are then broken down by sub-sector,
end-use technology and even by temperature level for the industry sector to provide a
complete picture of energy demand for H/C in the various market segments.

Figure 1 provides an overview of the different dimensions considered. Two examples
are given here of how the resulting H/C profiles can be used: to obtain the final energy
demand for space heating in multi-family houses in Belgium that is provided by air-

2
    http://www.forecast-model.eu/

4     www.heatroadmap.eu                                                                 @HeatRoadmapEU
source heat pumps; and to show the coal used to provide process heat in the iron and
steel sector in Italy in the temperature range above 500°C.
The profiles include final energy demand as well as useful energy demand. We define
useful energy demand as the heat provided by the combined system of a boiler plus
storage.
In the following, the definitions and data sources are described, before an overview of
the main results is provided. The annex gives a more detailed analysis of the H/C
profiles in each sector (industry, residential and tertiary).
5
www.heatroadmap.eu @HeatRoadmapEU2. Method, definitions and data sources
2.1. Method
The approach used combines empirical data with bottom-up modelling of energy
demand. The empirical data are taken from official national statistics, surveys as well
as various statistics provided e.g. by industrial organisations. An overview of the main
data sources is provided in section 0. For the bottom-up modelling, we use the energy
demand model FORECAST. A separate bottom-up model based on sales data is used
only for space cooling as described below.
2.1.1. Deriving end-use energy balances using the bottom-up
model FORECAST
The FORECAST model comprises three individual modules; each represents one sector
in line with the Eurostat (or national) energy balances: industry, services/tertiary and
residential. While all the sector modules follow a similar bottom-up methodology, they
also consider the particularities of each sector like technology structure, actor
heterogeneity and data availability. Energy demand is calculated based on technology
structure and technology characteristics as well as economic drivers and prices.
In the short term, the most important determinants of energy demand are ambient
temperature (affecting mainly space heating) and economic activity (affecting mainly
industrial process H/C demand). While the FORECAST model includes a detailed
simulation of technological change based on vintage stock models, these effects are
more important in the longer term (e.g. towards 2030 and beyond) and less so in the
short term.
FORECAST takes ambient temperature into account using the annual average
heating/cooling degree days (HDDs/CDDs) as shown in Table 4. Industrial activity is
reflected using the annual value added by sub-sector and the physical production per
year for major energy-intensive bulk products (e.g. tonnes of oxygen steel produced).
2015 production data were not available for most of the around 60 products considered
and forecasts were made based on past time series. Activities in the services sector are
driven by the number of employees and the sub-sector-specific energy demand per
employee and floor area.
As an example, Figure 2 shows how end-use energy balances are derived in FORECAST-
Industry based on bottom-up data by process and end-use. This approach combines
activity data such as production and employment with specific energy demand by
process/end-use.
6 www.heatroadmap.eu @HeatRoadmapEUProduction [t/a] Employment [Pers./a]
- by process - by sub-sector and building type
Processes (H/C) Space cooling Space heating
SEC FEDc,p, Floor areaC,S,B m²/Person
SEC
Share H/C FEDc,p,H/C [kWh/m²] SEC [kWh/m²]
FEDC,S,B,A FEDC,S,B,H
Share cooled
Share Temp FEDc,p,H/C,T FEDC,S,B,H
Share EC
(Eurostat) FEDc,p,H/C,T
Bottom-up / top-down matching
FED: Final energy demand Bottom-up FEDC,EC,E,T,S FED C,S,EC,T,E
SEC: Specific energy demand
C: Country
P: Process
H/C: Heating/Cooling FED (Gap)C,S,EC FED (Gap) C,S,EC,T,H
T: Temperature
S: Sub-Sector
B: Building type
E: End-use
A: Air conditioning / cooling FED (Eurostat)C,S,EC Share Temp (gap)
Source: Fraunhofer ISI et al. (2016)
Figure 2: Schematic representation of an end-use balance model calculation for the
industry sector (FORECAST-Industry)
Note that the calculation of H/C profiles is largely based on earlier work summarized in
Fraunhofer ISI et al. (2016). We also refer to this publication for a more detailed
description of the methodology by sector. However, we extend the H/C profile here by
including individual technologies such as heat pumps or industrial CHP units and
information on the technology stock such as the number of units installed in certain
market segments.
2.1.2. Space cooling
Space cooling demand and supply are calculated using a bottom-up model developed
by Armines. The demand is then split into sub-sectors according to the cooling shares
calculated by the FORECAST model (Aebischer et al. 2007). This approach is used to
update the cooling demand figures and is described in the following (for a more detailed
description of the approach and the input data, we refer to the separate HRE deliverable
on space cooling3).
Total space cooling demand and electricity consumption under standard conditions are
estimated using equipment sales. These include all vapour compression technologies
3
D3.2: Cooling technology datasheets and accompanying report "Dittmann, Perret-Gentil,
Riviere, Paardekooper, Connolly (2017): "Space Cooling in Europe: Technology Data and
Demand Modelling, Mines ParisTech – ARMINES, Paris"
7
www.heatroadmap.eu @HeatRoadmapEUavailable on the market, such as air-to-air split and VRF systems, ducted and rooftop
installations, air-cooled and water-cooled chillers as well as portable and window units.
The following steps apply to each sector in each country and each technology. Figure 3
shows the flow of information in detail. The total nominal cooling power installed is
estimated by calculating the 2015 stock from the number of units sold over the
preceding 24 years, the average power of the units sold and the average lifetime of the
technology. Dividing the installed power by the average power installed per unit of
indoor floor area (equipment sizing) yields the total cooled floor area. To estimate the
total space cooling supplied in the base year, the cooled floor area is multiplied by the
cooling energy demand per floor area (specific demand). The average SEER (seasonal
energy efficiency ratio) of units installed can be derived by combining the average SEER
of units sold with the stock model. Total electricity consumption under standard
conditions was then obtained by dividing the total cooling supply by the average SEER.
Actual electricity consumption is in fact higher due to suboptimal installation (over-
sizing), maintenance and usage practices. However, there is no statistically significant
information available to enable accurate corrections to the standard efficiencies.
EFFICIENCY TECHNOLOGYSTOCK
Units sold/y 1992-2015 (24y) by
SEER of units sold of ranges of cooling power
Eco-design studies Technology ( each year )
Certification data Units sold in sector by Repartition of units sold
ranges of cooling power over sector s
EU Regulation
Total (seasonal) electric Distribution of units sold
Total cooling power sold
power of units sold within cooling power ranges
Total (seasonal) electric
Lifetime of technology
power of units installed
SEER of units Total cooling power installed
installed 2011-2015
INSTALLATION BUILDINGSTOCK
Total ar ea Building type
Manufacturers Sizing ( cooling power/area) of building distribution of
Installation manuals for building types types sector
Hour ly weather data Building type
(one year) demand models Total area cooled Comparison with
other models/data
DC SPECIFIC Specific demand
Total cooling Comparison with
DEMAND MODEL (cooling
other models/data
energy/area) supply
by building type
BUILDINGDEMAND
Total electricity Comparison with
consumption other models/data
Figure 3: Overview of method for space cooling demand estimation
8 www.heatroadmap.eu @HeatRoadmapEU2.2. Definitions
The following summarises the main definitions used for the H/C profiles.
Final energy, delivered heat and useful energy
We define final energy in line with Eurostat as the energy input to the heating unit at
the final consumer. Like Eurostat, we also exclude ambient heat used in heat pumps.
Only the electricity or gas consumption of heat pumps is included in the final energy.
The definition of useful energy is less standardized. Different studies use different
definitions. We define useful energy as the energy distributed to the end-user, e.g. the
heat to a room provided by a radiator. Thus, useful energy takes into account potential
losses from local distribution, e.g. in the pipes in a building. Fraunhofer ISI et al. (2016)
use a similar definition for useful energy. However, our results are not based on useful
energy but on delivered energy instead. This is defined at the conversion step from final
energy to useful energy (see Figure 4). We define delivered energy as the heat or cold
produced by the combined system of an onsite boiler and storage before it enters the
distribution system. Possible losses in the distribution system (e.g. within a building)
are not taken into account for delivered energy.
Local distribution Transformation sector
Heat storage Heating & network
system
Losses
Losses
Losses
Losses
Heat or cold distributed Heat or cold produced by Energy input to
to end‐use boiler + storage boiler or plant
= Useful energy = Delivered energy = Final energy
Figure 4: Definition of final, delivered and useful energy
Technologies and energy carriers
A major extension of this report compared to Fraunhofer ISI et al. (2016) is the inclusion
of technology information. In order to keep the amount of data to a manageable level,
we use one combined dimension to represent energy carriers and technologies. While
9
www.heatroadmap.eu @HeatRoadmapEUsome energy carriers are well defined by particular technologies (e.g. gas is mainly used
in gas boilers), others are not (e.g. electricity). In the latter case, we split electricity
use into individual technologies including air-source and ground-source heat pumps,
direct electric resistance heating and compression cooling. Table 1 provides a complete
overview.
Table 1: Definition of technologies/ energy carriers
Definition / comment
Technology/ Energy carrier (final
energy)
Total Sum of all energy technologies/energy carriers
Gas includes all gas technologies not listed separately below,
still mainly individual boilers
Oil see gas
Coal see gas
Electric heating Direct electric heating (resistance heating also for night
storage)
District heating DH substations
Biomass Includes all biomass/biofuels/biogas technologies not
listed separately below
Solar thermal Only solar thermal.
Heat pumps total (electric) Include only electricity in final energy demand; ambient
heat not included; gas heat pumps not included
Heat pumps air‐source (electric) See heat pumps total; only heat pumps using air as heat
source
Heat pumps ground‐source (electric) See heat pumps total; only heat pumps using the ground
as heat source
Others (RES) Mainly RES waste and deep geothermal
Others (fossil) Mainly fuels used in industry including waste, stack gas,
etc.
Compression cooling (electric) Aggregates all cooling technologies
Sectors and sub-sectors
In terms of sectors, we follow the Eurostat energy balance definition by including
industry, tertiary/services and residential. For industry sub-sectors, we aggregate the
Eurostat energy balances slightly in order to have fewer very small sub-sectors. This
aggregation leads to a total of 8 sub-sectors (see Table 2). For the tertiary sector, we
also include 8 sub-sectors (see Table 3). Note that Eurostat does not provide
information for sub-sectors in the tertiary sector.
10 www.heatroadmap.eu @HeatRoadmapEUTable 2: Definition of sub-sectors in industry
Sub‐sectors NACE 2.0 Divisions
Iron and steel 24.1, 24.2, 24.3, 24.51, 24.52
Non‐ferrous metals 24,4, 24.53, 24.54
Paper, pulp and printing 17, 18
Non‐metallic mineral products 23
Chemical industry 20
Food, drink and tobacco 10, 11, 12
Engineering and other metal 25, 26, 27, 28, 29, 30
Other non‐classified 13, 14, 15, 16, etc
Table 3: Definition of sub-sectors in services
Economic subsector NACE (2.0) Description
Trade G Wholesale and retail trade
Hotel and restaurant I
Hotels and restaurants, camping sites, mountain refuges, bars,
canteens, catering
Traffic and data H, J Transport (railway, road, water, air), storage and
transmission communication, cargo handling, post, telecommunications,
Finance K Finance and insurance
Health Q
Health and social work, hospital activities, social work activities
with accommodation
Education P Primary and secondary education, higher education
Public administration O Public administration and defence, compulsory and social
security
Other services L,M,N,R,S Other services (waste, sport, social services) + real estate and
other services
Heating degree days (HDDs)
Heating degree days are used to correct space heating demand to the respective climate
conditions of 2015. HDDs are taken from Eurostat as shown in Table 4. For most
countries, 2015 has lower HDD values than the average annual values from 2010 to
2015. This means the demand for space heating was lower because 2015 was a
relatively warm year.
11
www.heatroadmap.eu @HeatRoadmapEUTable 4: Heating degree days (HDDs) used (source: Eurostat) Country 2010 2011 2012 2013 2014 2015 Average 2010‐2015 EU‐27/28 3,473 3,119 3,420 3,218 2,809 2,904 3,157 Austria 3,704 3,404 3,554 3,640 3,125 3,318 3,457 Belgium 3,174 2,399 2,772 3,024 2,315 2,633 2,719 Bulgaria 2,596 2,796 2,611 2,414 2,371 2,374 2,527 Croatia n.a. n.a. n.a. 2,301 1,895 2,256 n.a. Cyprus 442 832 826 701 556 750 685 Czech Republic 3,832 3,234 3,399 3,512 2,918 3,090 3,331 Denmark 3,971 3,150 3,423 3,402 2,855 3,114 3,319 Estonia 4,818 4,083 4,579 4,152 4,142 3,791 4,261 Finland 6,058 5,251 5,857 5,278 5,242 5,031 5,453 France 2,707 2,053 2,441 2,636 2,085 2,257 2,363 Germany 3,611 2,868 3,126 3,288 2,661 2,908 3,077 Greece 1,343 1,790 1,655 1,451 1,393 1,578 1,535 Hungary 2,936 2,815 2,771 2,687 2,286 2,597 2,682 Ireland 3,125 2,754 2,858 2,835 2,631 2,913 2,853 Italy 1,992 1,861 1,968 1,933 1,632 1,810 1,866 Latvia 4,622 3,940 4,320 4,037 3,948 3,658 4,088 Lithuania 4,409 3,768 4,082 3,872 3,727 3,524 3,897 Luxembourg 3,358 2,624 2,917 3,229 2,500 2,853 2,913 Malta 385 549 662 460 374 544 496 Netherlands 3,300 2,512 2,814 3,010 2,285 2,625 2,758 Poland 3,881 3,317 3,552 3,505 3,095 3,113 3,410 Portugal 1,290 1,087 1,348 1,340 1,147 1,080 1,215 Romania 2,988 3,173 3,090 2,863 2,729 2,786 2,938 Slovak Republic 3,467 3,248 3,299 3,241 2,718 3,057 3,172 Slovenia 3,041 2,818 2,832 2,867 2,342 2,700 2,767 Spain 1,913 1,562 1,871 1,910 1,570 1,612 1,740 Sweden 5,874 4,927 5,504 5,186 4,887 4,910 5,214 United Kingdom 3,403 2,846 3,183 3,179 2,740 3,017 3,061 12 www.heatroadmap.eu @HeatRoadmapEU
2.3.           Data sources
The following table provides an overview of the main data sources used.

Table 5: Selected data sources used

 Sector        Sub‐area                 Data sources used

               Dwelling stock, living   Enerdata (2016b), Enerdata (2016c), Eurostat (2016)
               area
 Residential
 sector
               Technology and           Enerdata (2016b), Enerdata, TU Vienna, Fraunhofer ISI et al.
               energy‐related data      (2016), Fraunhofer ISI, Fraunhofer ISE, IREES et al. (2016)

                                        EUROSTAT (number of employees), EU Building observatory, BPIE,
               Building and             Odyssee database (general), FhG‐ISE survey data (district heat),
 Tertiary
 sector        technology data          various EuP preparatory studies, IREES and ARMINES (cooling
                                        technologies)

                                        Prodcom, UNFCCC, Eurostat, industrial organisations (VDP,
               Industrial production    Cembureau, World Steel Association, Glassglobal) US geological
 Industry                               survey
 sector
                                        PLATTs database, Eurostat CHP statistics, numerous individual
               Technology data
                                        studies for individual sub‐sectors, e.g. Fleiter et al. (2011)

               Renewable energy         Eurostat energy balances, EHPA market reports, Observ´ER market
               technologies             reports

               Final and useful         Eurostat and national end‐use energy balances such as DUKES for
               energy demand            the UK.

                                        Space cooling sales: BSRIA WMI Market studies, Eurovent Market
                                        intelligence

 Cross‐                                 Specific demand (Service sector): District cooling deliveries
 cutting                                (Werner, 2015)
                                        Specific demand (residential sector): Dynamic building demand
               Space cooling            modelling (Rivière et al., 2008)
                                        Standard SEER values of sales: EU studies (Adnot et al., 1999),
                                        (Adnot et al., 2003), (Rivière et al., 2009), (Rivière et al., 2012),
                                        current Eurovent Certification product directory, public
                                        information and regulatory information from air conditioner labels
                                        and MEPS (EC, 2002), (EU, 2011), (EU, 2012) and (EU, 2016);

                                                                                                           13
www.heatroadmap.eu                                                                     @HeatRoadmapEU
3. Summary of main results
The resulting heating and cooling profiles allow a very detailed insight into the pattern
of H/C demand and supply by country, end-use, sector, sub-sector, energy carrier and
temperature level.
A few selected main results are presented here. A more detailed analysis of the results
is given in the annex to this report and allows deeper insights into the individual sectors.
Heating and Space heating
Non-H/C cooling 27%
50% 50% Process
heating
16%
Hot water
4%
Space Process
cooling cooling Other heating
1% 1% 1%
Other heating = cooking in residential buildings
Figure 5: Heating and cooling demand in 2015 in the EU28 by end-use compared to total final
energy (FED) demand
Further key results are:
• With a final energy demand (FED) of 6350 TWh in 2015, H&C is very important
and accounts for ~50% of EU28 FED
• Space heating (53% of FED for H/C) is the most important individual end-use
followed by process heating (32% of FED for H/C)
• Cooling accounts for ~2% of total FED for H&C and has low shares in most
countries, but the potential to grow strongly in the future
• Space heating is important in almost every country, while space cooling is
only relevant in southern countries.
14 www.heatroadmap.eu @HeatRoadmapEU0%
1% 0%
Gas
4% Oil
8%
Biomass
Electricity
9%
42% District heating
Coal
12%
Others (fossil)
Solar thermal
12% Heat pumps
12% Others (RES)
Figure 6: H&C final energy by energy carrier in 2015 (EU28)
The energy carrier mix for H/C shows the following pattern:
• Fossil fuels account for >65% in EU28 FED
• Electricity and district heating account for 21% (mainly based on fossil fuels)
• Renewable energy sources (RES) account for about 13%
• Gas is the most dominant fuel in EU28 (422%) and in most countries
• Of the available RES, only biomass is used substantially (12%); solar thermal,
geothermal and heat pumps are still marginal in almost every country
• However, the composition of energy carriers for H&C supply is very diverse
across countries.
15
www.heatroadmap.eu @HeatRoadmapEU3000
Space heating
Space cooling
2500
Process heating
Process cooling
Final energy [TWh]
2000
Hot water
Other heating
1500
1000
500
0
Industry Residential Tertiary
Other heating = cooking in residential buildings
Figure 7: H&C FED by sector and end-use (EU28, 2015)
Key results by sector:
• With about 2850 TWh, the residential sector has the highest FED for H/C
followed by industry (2390 TWh) and the tertiary sector (1120 TWh)
• Process heat accounts for about 80% of H/C FED in the industry sector
• Industrial process heat >200°C accounts for ~50% of industrial H&C FED, and
poses a challenge when switching to RES
• The end-use and energy carrier structure in industry vary strongly by sub-
sector
• In residential space heating, SFHs are twice as important as MFHs as an EU28
average
• In the tertiary sector, all sub-sectors are dominated by space heating
• Space cooling is much more important in the tertiary sector than in the
residential sector.
4. References
16 www.heatroadmap.eu @HeatRoadmapEUAdnot et al. (1999) Energy efficiency of room air-conditioners. Paris: Ecole des Mines
de Paris (coord. J. Adnot) et al, for DGTREN, the Commission of the European
Communities, SAVE contract DGXVII4.103/D/97.026, May.
Adnot et al. (2003): Efficiency and Certification of Central Air Conditioners (EECCAC).
Paris: Ecole des Mines de Paris (coord. J. Adnot) et al, for DGTREN, the
Commission of the European Communities, SAVE contract, April.
Aebischer B., Jakob M., Catenazzi The late G., Henderson (2007). Impact of climate
change on thermal comfort, heating and cooling energy demand in Europe.
Proceedings eceee Summer Study 2007, Colle sur Loup, France, June (ISBN 978-
91-633-0899-4).Enerdata (2016a): Odyssee-Mure database, Grenoble, France.
Enerdata (2016b): Stock of single and multifamily dwellings (permanently occupied),
Grenoble, France.
Enerdata (2016c): Living area of dwellings, Grenoble, France.
Enerdata, TU Vienna, Fraunhofer ISI, BPIE, Sofena, Seven 7, National Consumer
Research Centre, Öko-Institut, Efficiency Research Group, CENER: ENTRANZE -
Policies to ENforce the TRAnsition to Nearly Zero Energy buildings in the EU-27,
Grenoble, France.
Eurostat (2016): Number of private households by household composition,
Luxembourg.
EU (2011): COMMISSION DELEGATED REGULATION (EU) No 626/2011 of 4 May 2011
supplementing Directive 2010/30/EU of the European Parliament and of the
Council with regard to energy labelling of air conditioners, OJ L 178, 6.7.2011, p.
1–72.
EU (2012): Commission Regulation (EU) No 206/2012 of 6 March 2012 implementing
Directive 2009/125/EC of the European Parliament and of the Council with regard
to ecodesign requirements for air conditioners and comfort fans, OJ L 72,
10.3.2012, p. 7–27.
EU (2016): Commission Regulation (EU) 2016/2281 of 30 November 2016
implementing Directive 2009/125/EC of the European Parliament and of the
Council establishing a framework for the setting of ecodesign requirements for
energy-related products, with regard to ecodesign requirements for air heating
products, cooling products, high temperature process chillers and fan coil units,
OJ L 346, 20.12.2016, p. 1–50.
Fleiter, Tobias; Schlomann, Barbara; Hirzel, Simon; Arens, Marlene; Hassan, Ali;
Idrissova, Farikha et al. (Hg.) (2011): Where are the promising energy-efficient
technologies? A comprehensive analysis of the German energy-intensive
industries: eceee summer study 2011, June 6-11, Presqu’ile de Giens, France.
17
www.heatroadmap.eu @HeatRoadmapEUFraunhofer ISI; Fraunhofer ISE; IREES; Observ’ER; TU Wien; TEP Energy (2016):
Mapping and analyses of the current and future (2020 - 2030) heating/cooling
fuel deployment (fossil/renewables). Karlsruhe, Freiburg, Paris, Wien, Zürich.
Rivière et al. (2008): Preparatory Study on the Environmental Performance of
Residential Room Conditioning Appliances (Airco and Ventilation), Armines, Paris,
France, 2008.
Werner (2015): Sven Werner, European space cooling demands, Energy, Volume 110,
1 September 2016, Pages 148-156, ISSN 0360-5442.
18 www.heatroadmap.eu @HeatRoadmapEUProfile of heating and cooling
demand in 2015
D3.1 - Detailed results annex
This project has received funding from the
European Union's Horizon 2020 research www.heatroadmap.eu
and innovation programme under grant @HeatRoadmapEU
agreement No. 695989.Contents • Overview • Industry sector • Residential sector • Tertiary sector • Cooling • Conclusions This project has received funding from the European Union's Horizon 2020 research www.heatroadmap.eu and innovation programme under grant @HeatRoadmapEU agreement No. 695989.
OVERVIEW

  This project has received funding from the
  European Union's Horizon 2020 research       www.heatroadmap.eu
  and innovation programme under grant           @HeatRoadmapEU
  agreement No. 695989.
Total final energy demand (FED) in 2015
                 (EU28)
               High relevance: H&C about 50% of FED!

                                Heating and                 Space heating
     Non-H/C                      cooling                       27%
      50%                          50%          Process
                                                heating
                                                  16%

                                                                     Hot water
                                                                       4%
                                                Space     Process
                                                cooling   cooling    Other heating
                                                  1%        1%            1%

   This project has received funding from the
   European Union's Horizon 2020 research                                   www.heatroadmap.eu
   and innovation programme under grant                                       @HeatRoadmapEU
   agreement No. 695989.
H&C FED by end-use in 2015 (EU28)
Process Space cooling
Other heating
cooling 1% 2015:
3%
3%
Hot water Process
High relevance
8% heating
32% of space and
process heating;
Lower relevance
of cooling
Space
heating
53%
This project has received funding from the
European Union's Horizon 2020 research www.heatroadmap.eu
and innovation programme under grant @HeatRoadmapEU
agreement No. 695989.H&C FED by end-use and country (EU28,
2015)
100%
Space cooling
90%
Process cooling
80%
Other heating
70%
Process heating
60%
Hot water
50%
Space heating
40%
30% • Space heating and
20% process heating
10% important in all
0% countries
• Cooling important
in southern
countries
This project has received funding from the
European Union's Horizon 2020 research www.heatroadmap.eu
and innovation programme under grant @HeatRoadmapEU
agreement No. 695989.Share of space heating in total FED for H&C
Space heating is
also relevant in
southern
countries!
This project has received funding from the
European Union's Horizon 2020 research www.heatroadmap.eu
and innovation programme under grant @HeatRoadmapEU
agreement No. 695989.H&C FED by energy carrier in 2015 (EU28)
0%
1% 0%
Gas 2015 shares FED:
8%
4% Oil
Biomass
• Fossil: 66%
9%
Electricity • RES: 13%
42% District heating
Coal
• El+DH: 21%
12%
Others (fossil)
Solar thermal
12% Heat pumps
12% Others (RES)
This project has received funding from the
European Union's Horizon 2020 research www.heatroadmap.eu
and innovation programme under grant @HeatRoadmapEU
agreement No. 695989.H&C FED by energy carrier and country
(EU28, 2015)
100%
90%
1600
Others (RES) • Energy carrier
1400 Solar thermal mix very
80%
1200
Heat pumps
country specific
Biomass
•
Total final energy [TWh]
70%
Electricity Gas important
1000
60%
District heating in most
50% 800 Others (fossil) countries (less
40%
600
Oil in SE and FI)
30%
400
Coal
Gas
• Solar and heat
20% Total pumps still
10%
200 marginal
0% 0
almost
United…
Slovak…
everywhere
France
Poland
Sweden
Finland
Austria
Greece
Malta
Netherlands
Denmark
Spain
Italy
Portugal
Ireland
Croatia
Lithuania
Luxembourg
Czech Republic
Cyprus
Latvia
Germany
Romania
Bulgaria
Slovenia
Estonia
Belgium
Hungary
This project has received funding from the
European Union's Horizon 2020 research www.heatroadmap.eu
and innovation programme under grant @HeatRoadmapEU
agreement No. 695989.H&C FED by energy carrier (2015, EU28)
4000
End‐uses use energy
Solar thermal carriers differently:
3500 Others (RES) • Gas is important
3000
Others (fossil) in both process
Final energy [TWh]
Oil and space
2500 Heat pumps heating
2000 Gas • Coal is important
Electricity
in process
1500 heating
1000
District heating
Coal
• Biomass and
district heating
Biomass more in space
500
heating
0
Process Process Hot water Other Space Space
heating cooling heating heating cooling
This project has received funding from the
European Union's Horizon 2020 research www.heatroadmap.eu
and innovation programme under grant @HeatRoadmapEU
agreement No. 695989.H&C FED by sector and end-use (EU28,
2015)
3000
Space heating
End‐uses by sector:
Space cooling • Industry: >80%
2500
Process heating
for process heat
Process cooling
• Residential:
>75% for space
Final energy [TWh]
2000
Hot water
heating
Other heating
1500 • Tertiary: highest
share of cooling
1000
compared to
other sectors
(~10%)
500
0
Industry Residential Tertiary
This project has received funding from the
European Union's Horizon 2020 research www.heatroadmap.eu
and innovation programme under grant @HeatRoadmapEU
agreement No. 695989.H&C FED by sector and energy carrier
(EU28, 2015)
100% Solar thermal Energy carrier mix
Others (RES)
varies by sector:
90%
80%
• Industry:
Others (fossil) highest share of
70%
Oil
coal and other
60%
fossil
50%
Heat pumps
(electric)
• Residential:
Gas highest share of
40% biomass
30% Electricity
• Tertiary:
20% District heating highest share of
electricity and
10% Coal gas
0%
Industry Residential Tertiary Biomass
This project has received funding from the
European Union's Horizon 2020 research www.heatroadmap.eu
and innovation programme under grant @HeatRoadmapEU
agreement No. 695989.INDUSTRY SECTOR This project has received funding from the European Union's Horizon 2020 research www.heatroadmap.eu and innovation programme under grant @HeatRoadmapEU agreement No. 695989.
Industry FED for H&C by end-use
            (EU28, 2015)
  1%    1%
   1%        2%
                                      Process heating 500 °C      decarbonization)!
                          21%         Space heating

                                      Space cooling

                                      Process cooling
Industry sector by temperature and sub-
sector (EU28, 2015)
Very diverse structure in sub‐sectors!
600
Process cooling 0-15 °C
500
Final energy [TWh]
Process cooling -30-0 °C
400 Process cooling 500 °C
Process heating 200-500 °C
0
Process heating 100-200 °C
Process heatingIndustry FED H&C by energy carrier
(EU28, 2015)
1% 0%
Gas most important
9%
11% Biomass energy carrier, but
Coal
also high shares of
8% District heating
17% coal.
Electricity
Gas
Oil
8% Others (fossil)
Others (RES)
39% 7% Solar thermal
This project has received funding from the
European Union's Horizon 2020 research www.heatroadmap.eu
and innovation programme under grant @HeatRoadmapEU
agreement No. 695989.Industry FED H&C by energy carrier and
sub-sector (EU28, 2015)
600
Distribution of
Final Energy [TWh]
500 Solar thermal
400 Others (RES) energy carriers varies
300 Others (fossil) by sub‐sector:
200 Oil
100 Gas ‐ high share of
0 Electricity biomass in pulp &
District heating
Coal
paper
Biomass ‐ high share of coal
in iron & steel
Achsentitel
‐ other fossil fuels
(e.g. waste) high
shares in non‐
metallic minerals
(mainly cement)
This project has received funding from the
European Union's Horizon 2020 research www.heatroadmap.eu
and innovation programme under grant @HeatRoadmapEU
agreement No. 695989.Industry FED by end-use and energy carrier
(EU28, 2015)
Patterns:
1200
1000
Solar thermal
• Coal for high
Final energy [TWh]
Others (RES)
800
Others (fossil) temperatures
600
400
Oil
Gas
• Biomass for
200
Electricity steam
0
• DH for low
District heating
Coal
Biomass temperatures
This project has received funding from the
European Union's Horizon 2020 research www.heatroadmap.eu
and innovation programme under grant @HeatRoadmapEU
agreement No. 695989.Industry: FED for H&C by country and
energy carrier (EU28, 2015)
100% 600
Solar thermal
90% Huge
Others (RES)
80%
500
diversity
Others (fossil)
70%
400
across
Oil
Final energy [TWh]
60% countries!
Gas
50% 300
Electricity
40%
200 District heating
30%
Coal
20%
100
Biomass
10%
Total
0% 0
Denmark
France
Poland
Finland
Sweden
Austria
Greece
Malta
Netherlands
Czech Republic
Spain
Ireland
Croatia
Italy
Portugal
Cyprus
Lithuania
Luxembourg
Slovak Republic
Romania
Slovenia
Latvia
Estonia
Germany
United Kingdom
Belgium
Hungary
Bulgaria
This project has received funding from the
European Union's Horizon 2020 research www.heatroadmap.eu
and innovation programme under grant @HeatRoadmapEU
agreement No. 695989.Share of biomass in industry FED
High share of biomass in
Nordic countries
This project has received funding from the
European Union's Horizon 2020 research www.heatroadmap.eu
and innovation programme under grant @HeatRoadmapEU
agreement No. 695989.Industry: FED for H&C by country and end-
use (EU28, 2015)
100% 600
Process cooling 0-15 °C
90%
500 Process cooling -30-0 °C
80%
Process cooling 500 °C
200 Process heating 200-500 °C
30%
20% Process heating 100-200 °C
100
10% Process heating 100°C!
This project has received funding from the
European Union's Horizon 2020 research www.heatroadmap.eu
and innovation programme under grant @HeatRoadmapEU
agreement No. 695989.Industry: Energy carriers and end-uses
(EU28, 2015)
• Italy Broad mix of
industries • Sweden
Large pulp & paper
industry
120 60
Solar Solar thermal
thermal 50
Final energy [TWh]
100
Final energy [TWh]
Others Others (RES)
(RES)40
80 Others Others (fossil)
(fossil)30
60 Oil Oil
20
40 Gas Gas
10
20 Electricity Electricity
0 District heating
0 District
heating Coal
Coal
Biomass
Biomass
This project has received funding from the
European Union's Horizon 2020 research www.heatroadmap.eu
and innovation programme under grant @HeatRoadmapEU
agreement No. 695989.Industry process heat
Industry process heat
Industry process heat
RESIDENTIAL SECTOR

  This project has received funding from the
  European Union's Horizon 2020 research       www.heatroadmap.eu
  and innovation programme under grant           @HeatRoadmapEU
  agreement No. 695989.
Residential sector: FED for H&C by end-use
               (EU28, 2015)
                     1%                                          At almost 80%, space
                          7%                     Other heating
             15%                                                 heating most
                                                 Space heating
                                                                 important

                                                 Hot water

                                                 Space cooling

                           77%

    This project has received funding from the
    European Union's Horizon 2020 research                                      www.heatroadmap.eu
    and innovation programme under grant                                          @HeatRoadmapEU
    agreement No. 695989.
Residential sector: FED for H&C by end-use
and country (EU28, 2015)
100%
90%
Space cooling
Other heating
Space heating
80%
70% Hot water dominant almost
60% Space heating
50% everywhere
40%
30% Cooling significant
20%
10% only in southern
0%
countries
France
Poland
Austria
Malta
Netherlands
Finland
Sweden
Denmark
Greece
Italy
Spain
Ireland
Croatia
Slovak Republic
Lithuania
Portugal
Luxembourg
Cyprus
Czech Republic
Germany
Bulgaria
Latvia
Slovenia
Estonia
United Kingdom
Belgium
Romania
Hungary
Hot water
relatively similar
* Other heating = cooking across countries
This project has received funding from the
European Union's Horizon 2020 research www.heatroadmap.eu
and innovation programme under grant @HeatRoadmapEU
agreement No. 695989.Space heating as share of residential
sector’s FED for H&C
Space heating is
also relevant in
southern
countries!
This project has received funding from the
European Union's Horizon 2020 research www.heatroadmap.eu
and innovation programme under grant @HeatRoadmapEU
agreement No. 695989.Residential sector: FED for H&C by energy
carrier (EU28, 2015)
1% 1% • Natural gas most
Gas
4% important: >40%
•
9% Biomass
Biomass second
Oil
highest share: 16%
Electricity
12% 43%
District heating
• Heat pumps and
solar thermal still
Coal
14%
marginal (Residential sector: FED for H&C by energy
carrier and country (EU28, 2015)
100% 700
90%
600
Solar thermal Huge
80%
500
Oil diversity
70%
FED H&C [TWh]
60%
Heat pumps across
400
50% Gas countries
40% 300
Electricity
30% 200
20% District heating
100
10% Coal
0% 0
Biomass
Swede n
Por tug al
Hunga ry
Spa in
Ger ma ny
Sloven ia
Malta
Netherland s
Cze ch Repub lic
Latvia
Lithuan ia
Luxembou rg
United Kingdo m
France
Pola nd
Austria
Cyp rus
Croatia
Esto nia
Belg ium
Bulg aria
Romania
Denmark
Slovak Re public
Ireland
Italy
Finland
Gre ece
Total
This project has received funding from the
European Union's Horizon 2020 research www.heatroadmap.eu
and innovation programme under grant @HeatRoadmapEU
agreement No. 695989.Residential sector: FED for H&C by
single/multi-family house in 2015 (EU28)
1600
SFH twice as
1400
1200 Solar thermal
relevant as
Final energy [TWh]
1000 Oil multi‐family
Heat pumps
800
Gas houses
600 Electricity
400 District heating
Coal
200
Biomass
0
Other Space Hot water Space Hot water Space
heating cooling SFH heating MFH heating
SFH MFH
This project has received funding from the
European Union's Horizon 2020 research www.heatroadmap.eu
and innovation programme under grant @HeatRoadmapEU
agreement No. 695989.Share of SFH in total space heating
demand (2015)
Importance of SFH
varies heavily by
member state!
This project has received funding from the
European Union's Horizon 2020 research www.heatroadmap.eu
and innovation programme under grant @HeatRoadmapEU
agreement No. 695989.TERTIARY SECTOR This project has received funding from the European Union's Horizon 2020 research www.heatroadmap.eu and innovation programme under grant @HeatRoadmapEU agreement No. 695989.
Tertiary sector: FED for H&C by end-use
              (EU28, 2015)
                                                                 Space
               8%     5%
                             6%
                                               Process heating   heating most
                                  4%           Process cooling   important
                                               Space cooling

                                               Space heating

                                               Hot water

            77%

  This project has received funding from the
  European Union's Horizon 2020 research                                www.heatroadmap.eu
  and innovation programme under grant                                    @HeatRoadmapEU
  agreement No. 695989.
Tertiary sector: FED for H&C by sub-sector
and end-use in 2015 (EU28)
300
Process heating
250
Final energy [TWh]
Process cooling
200
Space cooling
150 Space heating
100 Hot water
50
0 Wholesale and
retail most
important sub‐
sector, but all
relevant.
This project has received funding from the
European Union's Horizon 2020 research www.heatroadmap.eu
and innovation programme under grant @HeatRoadmapEU
agreement No. 695989.Tertiary sector: FED for H&C by end-use
and country (EU28, 2015)
100% 350
Process heating
90%
300
Final energy for H&C [TWh]
80% Process cooling
70% 250
Space cooling
60%
200
Space heating
50%
150 Hot water
40%
30% 100 Total heating and
20% cooling
50
10%
0% 0
Space heating important
in all countries
Southern countries have
substantial share of
space cooling
This project has received funding from the
European Union's Horizon 2020 research www.heatroadmap.eu
and innovation programme under grant @HeatRoadmapEU
agreement No. 695989.Tertiary sector: FED for H&C by energy
carrier (EU28, 2015)
1% 0%
2% 1% 0%
Gas
Natural gas
5% Electricity dominant at >45%
Oil
10%
District heating
46% Biomass
16%
Solar thermal Share of electricity
Coal
Heat pumps
driven by cooling
19%
Others (fossil)
and process
Others (RES)
heating
This project has received funding from the
European Union's Horizon 2020 research www.heatroadmap.eu
and innovation programme under grant @HeatRoadmapEU
agreement No. 695989.Tertiary sector: FED for H&C by energy
carrier and country (EU28, 2015)
100% Solar thermal Huge
90%
80%
Heat pumps diversity
70% Biomass
60% District heating
across
50%
Electricity countries
40%
30% Coal
20% Oil
10%
Gas
0%
France
Poland
Sweden
Austria
Finland
Denmark
Greece
Malta
Netherlands
Italy
Spain
Ireland
Croatia
Lithuania
Luxembourg
Cyprus
Portugal
Czech Republic
Slovak Republic
Germany
Hungary
Romania
Bulgaria
Latvia
Slovenia
Estonia
United Kingdom
Belgium
This project has received funding from the
European Union's Horizon 2020 research www.heatroadmap.eu
and innovation programme under grant @HeatRoadmapEU
agreement No. 695989.Share of district heating in tertiary sector’s
FED for H&C
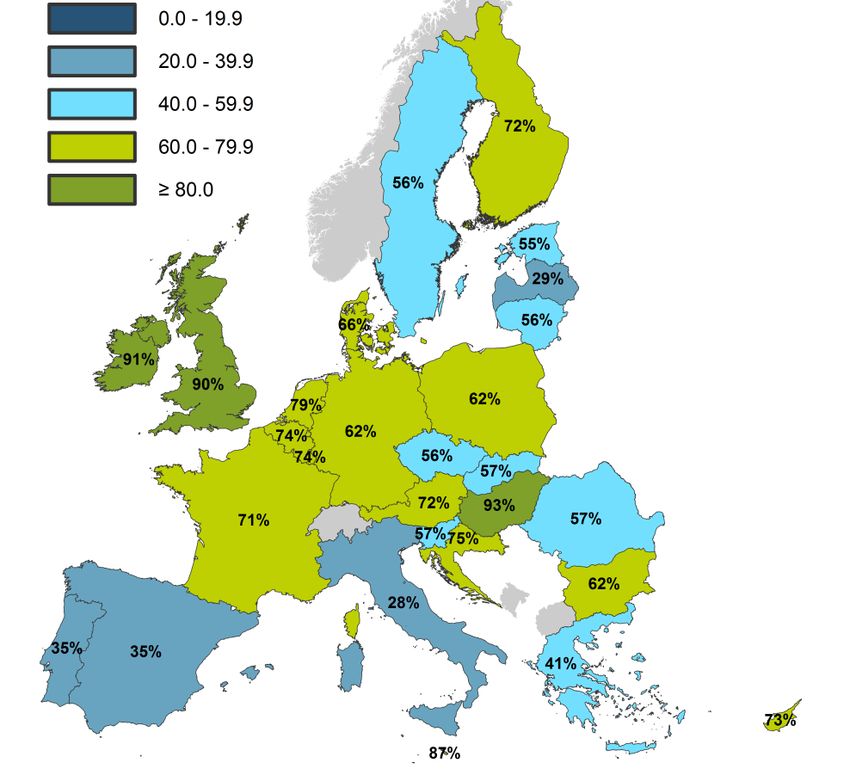
• Very high shares in Nordic
countries
• Average shares in most
eastern countries
• Low shares in individual
countries such as UK,
Ireland, Spain, Portugal,
Italy
This project has received funding from the
European Union's Horizon 2020 research www.heatroadmap.eu
and innovation programme under grant @HeatRoadmapEU
agreement No. 695989.COOLING This project has received funding from the European Union's Horizon 2020 research www.heatroadmap.eu and innovation programme under grant @HeatRoadmapEU agreement No. 695989.
FED for cooling by end-use and country
                (2015)
            40                                   •       Space cooling relevant in southern
            35                                           countries and marginal in northern
            30                                           countries
            25
                                                 •       Process cooling more evenly
 TWh/year

            20
                                                         distributed across climate regions
            15
            10
             5
             0
                          Greece
                           France

                             Malta
                           Poland

                           Austria
                     Netherlands

                          Finland
                         Sweden

                        Denmark
                              Italy
                             Spain

                          Cyprus

                          Croatia

                    Luxembourg

                           Ireland
                         Portugal

                 Slovak Republic

                        Lithuania
                 Czech Republic
                       Germany

                         Belgium
                        Romania
                         Bulgaria

                        Hungary

                        Slovenia

                            Latvia
                          Estonia
                 United Kingdom

                                            Process cooling    Space cooling

            This project has received funding from the
            European Union's Horizon 2020 research                                www.heatroadmap.eu
            and innovation programme under grant                                    @HeatRoadmapEU
            agreement No. 695989.
Share of total cooled floor area by country
100,0%
• Southern countries
90,0% have higher shares
•
80,0%
70,0% Service sector has
60,0%
50,0%
higher shares than
40,0% residential sector
•
30,0%
20,0% Residential buildings
10,0%
0,0%
in northern
European countries
have negligible
shares
Residential sector Tertiary sector
• Huge future growth
in demand expected
This project has received funding from the
European Union's Horizon 2020 research www.heatroadmap.eu
and innovation programme under grant @HeatRoadmapEU
agreement No. 695989.MAIN CONCLUSIONS This project has received funding from the European Union's Horizon 2020 research www.heatroadmap.eu and innovation programme under grant @HeatRoadmapEU agreement No. 695989.
Main conclusions 2015

•   H&C is very important with ~50% of EU28 FED
•   Very diverse composition of energy carriers for H&C supply
    across countries. Still:
     •   Gas is the most dominant fuel in EU28 and in most countries for
         H&C.
     •   Fossil fuels account for >65% in EU28 FED for H&C
     •   Of RES, only biomass is used substantially; solar thermal,
         geothermal and heat pumps are still marginal in almost every
         country

     This project has received funding from the
     European Union's Horizon 2020 research                       www.heatroadmap.eu
     and innovation programme under grant                           @HeatRoadmapEU
     agreement No. 695989.
Main conclusions 2015
• Space heating and process heating most relevant end-uses.
• Space heating: SFH twice as important as MFHs as an EU28 average
• Process heating: Process heat >200°C accounts for ~50% of industrial
H&C FED, and represents a challenge when switching to RES
• Cooling accounts for ~2% of total FED for H&C and currently has low
shares in most countries but the potential to grow strongly in future
This project has received funding from the
European Union's Horizon 2020 research www.heatroadmap.eu
and innovation programme under grant @HeatRoadmapEU
agreement No. 695989.ABBREVIATIONS This project has received funding from the European Union's Horizon 2020 research www.heatroadmap.eu and innovation programme under grant @HeatRoadmapEU agreement No. 695989.
Abbreviations

•   FED: Final energy demand
•   CHP: Combined heat and power
•   HRE: Heat Roadmap Europe
•   ICG: Internal combustion engine
•   EU: European Union
•   SFH: Single-family houses
•   MFH: Multi-family houses
     This project has received funding from the
     European Union's Horizon 2020 research       www.heatroadmap.eu
     and innovation programme under grant           @HeatRoadmapEU
     agreement No. 695989.
You can also read


