Welcome to Harvest Financial Services
           presentation on
Getting Your Retirement Strategy Right

           12th May 2016
←
→
Page content transcription
If your browser does not render page correctly, please read the page content below
Welcome to Harvest Financial Services
presentation on
Getting Your Retirement Strategy Right
12th May 2016
Who are Harvest Financial Services?

•   23 years in business
•   50+ highly qualified staff
•   Circa €1 billion under administration
•   Highly regulated
     - MiFID/Pension Trustees/QFM
•   Fee-based business model
•   Pensions, investments and financial planning
Today’s Topics

•   Why Pensions are important.
•   Background to pensions and how to maximise the
    opportunities – Emer Kirk
•   Investment Options and the need for exposure to
    real assets – Terry Devitt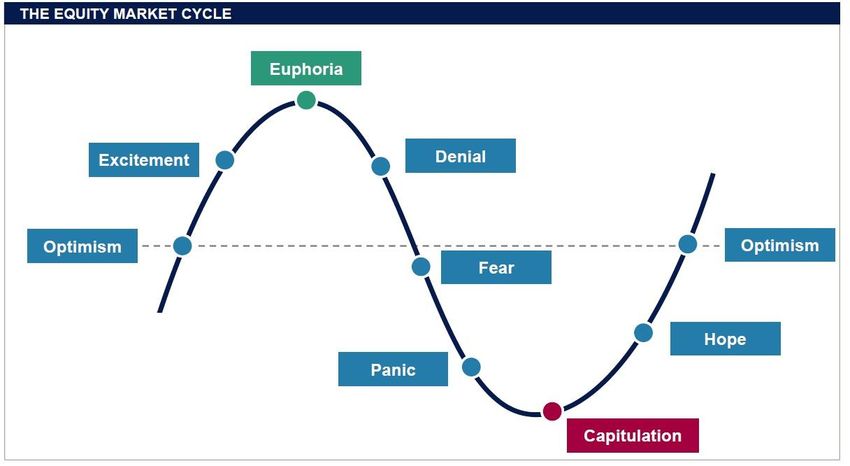
The need for Retirement Planning
     was never more critical

• Mortality improvements
   – DB – employer took risk
   – DC – now its down to us as individuals
• Age 60 or 65 target retirement date mindset – but
  we have no idea what we can expect
• State Pension - we can’t assume it will be sustained
  at anywhere near current levels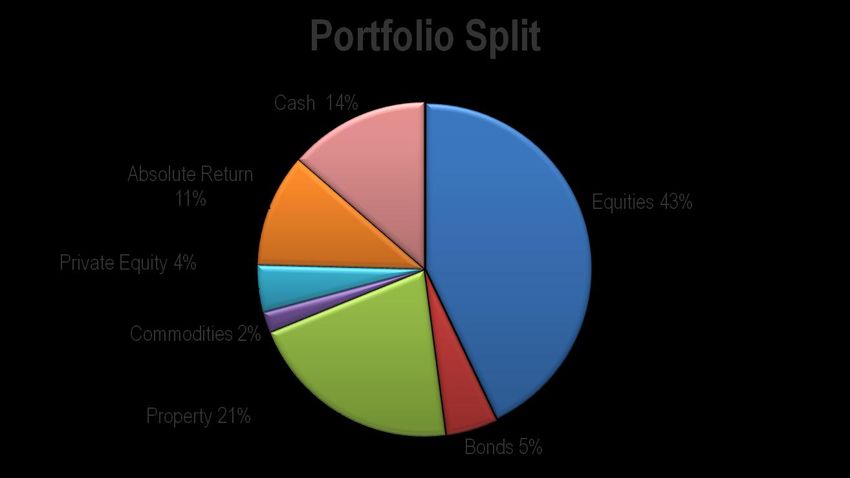
The Bad News
               We’re living longer….

CSO: Census 2011
How much is enough?
            Only YOU can answer this

•   What income will you need in retirement?
•   Will you carry debt in to retirement?
•   Will your kids be independent?
•   Will your parents need assistance?

• How are you going to fund it???
Emer Kirk
Getting Your Retirement Strategy Right
What I hope to cover today

•   Planning for retirement – how to fund it?
•   Tax reliefs still available
•   Different pension structures
•   Protecting your plan
How are you going to fund it?

                                     Savings &
                                     Investments
                                                       Inheritance

                                  Personal

   Value of Business

                       Business
                                                              Private Pension
          Income
                                             Pension          State Pension
Personal Wealth • Income from investments, e.g. will investment property provide rental income in retirement • Inheritances • Savings • Capital value of investments
Business Wealth

• Will your business have any value at retirement?
• Can it be sold?
• What is it’s real value?
• Do you intent to pass the business on to children?
  (PWC 2014 Irish Family Business Survey)
• Will Retirement Relief be available?
• Can you de-risk by taking cash out of the business
  tax efficiently throughout your working life?
Retirement Relief

• EUR 750,000 tax free if over 55 and under 66
• EUR500,000 if over 66
• Nothing tax free if significantly over limits e.g. sell
  for EUR2m – no retirement relief
• Family company (generally 25% minimum)
• Must be full time working director for 5 years
• Available to spouses individually
Tax Efficient Cash Extraction
                 a.k.a. Pensions
• Take value from business for own/family’s benefit
• Corporation tax deduction
• Income tax relief on personal contribution
• Funds are invested in tax exempt investment vehicle,
  no income tax or CGT
• Portion paid tax free at drawdown
• Passes to spouse/children tax efficiently on your
  demise
• With some restrictions, you can decide where to
  invest the funds
The Different Types of Pensions • Traditional pension – insurance company, managed funds • Self Directed Pension – insurance company, more investment choice • Self Administered Pension – held in trust, open architecture, wide investment choice
Why Self Administered?

•   Control
•   Flexibility
•   Security
•   Transparency
Self Administered Pensions –
            Some Investment Options
•   Investment funds – equities, bonds, multi asset
•   Deposits
•   Individual shares
•   Property
    – Direct property
    – Development Partnerships
    – Property Funds, e.g. IPUT, REITS
Tax Efficiency
Draw from Company now Contribute to Pension
Gross amount €100,000 €100,000
Income tax, USC, PRSI €52,000 €0
Net amount for investment €48,000 €100,000
Invest for 20 years @ 4% €105,174 €219,112
Net return (ignore CGT) €105,174
25% tax free lump sum €54,778
Balance @ 52% €85,454
Net return €133,659
Return on Gross Amount 105% 134%Pensions – What you need to know! • Most appropriate pension structure for you • Tax reliefs available, both corporation & income tax • Gross roll up on investment returns • Tax efficient lump sum at retirement • Passes to estate/beneficiaries on death • Standard Fund Threshold of €2M – per person (spouse’s pension?) • Costs…. All the costs! • Where it is invested and the impact of investment returns on your retirement income (pre & post retirement)
Need to protect the plan!

• What happens to your income if you cannot work?
• What happens to your family’s income if you die?
• What happens to your business if one of your
  partners cannot work?
• What happens to your business if one of your
  partners dies?

• Need to look at protecting both family and the key
  individuals in your business that can impact on your
  plan!
How do Harvest help?

• Indentify needs and objectives
• Prioritise these needs and objectives
• Work with your advisors (e.g. solicitor, accountant,
  tax advisor)
• Put your financial plan in place – pension,
  protection, investment advice
• Review regularly
Terry Devitt

The Need for Risk
So What is Happening in the World?

 •   Interest rates at all time lows
 •   Inflation largely absent
 •   Debt levels at all time highs
 •   Equity markets volatile
 •   Growth difficult to come by
The Geopolitical Landscape

  BREXIT…..                The Rise and Rise of Donald…..

Does QE actually work….?   All eyes on China……
25 yr Performance of Major Asset
             Classes
Getting Comfortable with the Risk in
your Portfolio
• Growth cannot happen without Risk
• Most important Ingredients are Time
and Diversification
• Learn to Ignore Market FluctuationsCash Fund vs. Equity Fund
The Equity Market Cycle
FTSE 100 over 30 years
“Avoid trying to predict the markets. Remember We
have two classes of forecasters: Those who don't
know …and those who don't know they don't know”

     J K Galbraith
The Passive vs Active Debate • Passive investing has exploded over the past decade • Relative costs and performance main drivers of this trend • But passive investing not the answer to all investment challenges
Passive vs Active 1
European Equities
Summary of investment Process
                Geopolitics                                                   Age

                                                        Attitude to Risk                           Projections and
                                    Market                                                         Review
Economics       Market              Valuations
                                                                           Risk Profile

             Conditions                                                        of
                                                                            Investor

                                             Suggested
                                                 Portfolio

            Research and Analysis                                              Monitoring and Review
                                            Recommended
                                                  Funds List
Harvest’s Risk Rating of
InvestmentsFive Investment Pillars • Time Horizon • Asset Allocation/Diversification • Differentiate between Cyclical and Permanent Losses • 80:20 Rule • Income
1. Time Horizon

• Exposure to Risk Assets (Equities, Property)
  requires a time horizon of five years minimum

• This allows for market cycles to run their course
And We All have More Time than we Think …
                   Centenarians in Ireland
     300

     250

     200

     150
                                             Centenarians in Ireland

     100

     50                                       Source: Human
                                              Mortality database
                                              (HMD)

       0
           1994

           2004
           1950
           1952
           1954
           1956
           1958
           1960
           1962
           1964
           1966
           1968
           1970
           1972
           1974
           1976
           1978
           1980
           1982
           1984
           1986
           1988
           1990
           1992

           1996
           1998
           2000
           2002

           2006
           2008
           2010
2. Asset Allocation and Diversification • Important to achieve appropriate balance between the major asset classes • Market timing is a very difficult thing to get right so at times of uncertainty phased investment is advisable
Balanced Asset Allocation
3. Cyclical and Permanent Losses
                          Portfolio Losses

                                         Permanent
          Cyclical
                                  • Single Stocks
 • Diversified Equities
                                  • Geared Property
 • Ungeared Property
                                  • Debt of any Kind

                                  • Private Equity
4. Follow the 80:20 Rule • Ensure at least 80% of your portfolio is diversified, liquid and does not involve gearing • The corollary is that a maximum of 20% of the portfolio should run the risk of permanent loss
5. Income

• Build in an income focus to a portion of
  your portfolio
• Income a real measure of value
• Compensation during volatile times
• Currently not difficult to beat Income
  from cash
‘The biggest risk is not taking any risk.
The only strategy that is guaranteed to
fail is not taking any risks.’

Mark Zuckerberg
Conclusion

•Important to have a plan
•Maximise tax reliefs available
•Invest for long term growth
•Plan early to maximise opportunities
•Need for advice never more critical
The information contained herein is based on Harvest Financial Services Limited's
understanding of current Revenue practice as at May 2016 and may change in the
future.

The material is not intended to provide advice and is provided for general information
purposes only.

  •
Please note that the provision of certain products and services do not require licensing,
authorisation, or registration with the Central Bank of Ireland and, as a result, are not
covered by the Central Bank's requirements designed to protect consumers or by a
statutory compensation scheme.

Warnings: The value of your investment may go down as well as up. You may get back
less than you invest. Past performance is not a reliable guide to future performance. If
you invest in a pension product you will not have any access to your money until your
retirement. These figures are estimates only. They are not a reliable guide to the future
performance of these investments. Returns may be affected by changes in currency
exchange rates.
Thank You
                                   Terry Devitt
                           tdevitt@harvestfinancial.ie

                                   Emer Kirk
                            ekirk@harvestfinancial.ie

Harvest Financial Services Limited is regulated by the Central Bank of Ireland.
You can also read


