RETAIL PROPERTY MARKET - FRANCE - Knight Frank
←
→
Page content transcription
If your browser does not render page correctly, please read the page content below
Q2 2018

 R E TA I L

     RETAIL PROPERTY
         MARKET

              FRANCE
FRENCH RETAIL PROPERTY MARKET
OVERVIEW

             • Household consumption will remain sluggish in 2018 due to increases in purchase power being worn away by the increase in inflation.
               However, French spending should accelerate during the second half of the year and maintain a steady pace in 2019 and 2020 due to the
Economy

               continued improvement in the job market, wage gains and more favourable tax measures.
             • Following a record level in 2017, tourist numbers continue to increase in 2018 in the Greater Paris Region, with a 7% increase year-on-year
               in the number of hotel arrivals during the 1st quarter, related to the dynamism of the international clientele (+ 16.5 %, compared to + 0.2 % for
               the French).

             • This is a time for multi-faceted approaches, merging and commercial innovation. Shop-in-shops, pop-up stores, showrooms and single-brand
               stores, brand associations…. terms and formats are not lacking, revealing a deeply changed commercial landscape, notably as a result
Brands

               of the joint development of physical and virtual worlds.
             • This joint development, illustrated by the digitalisation of points of sale and the incursion of “pure-players” in the field of physical retail, also
               continues to manifest itself as an increase in alliances between traditional retailers and internet players (Monoprix/Sarenza,
               André/Spartoo, Carrefour/Google, etc.).

             • Brand difficulties and their profitability requirements continue to punctuate the retail property market through an increase in disposals,
               whatever the asset class. The lasting nature of the increase in vacancy rates is, however, a function of the intrinsic quality of each asset,
               retail zone or retail pitch.
Rental

             • Restaurants, food, sport, beauty and decoration account for a significant proportion of openings and thus partially offset the slow down in
               fashion. This diversity of players, and new concepts that they are the source of, notably contribute to the dynamism of the very heart of Paris,
               as well as the renewal of the retail offer in large regional cities.

             • 1.6 billion billion euros were invested in the retail market in France during the 1st half of 2018, an increase of 23% year-on-year. The
Investment

               increase, however, is misleading as it is due to the completion of one exceptional deal: the acquisition by Hines, for BVK, of the future Apple
               Store on the Champs-Élysées for almost 600 million euros, which greatly inflated investment volumes on high streets (65%).
             • Retail parks take second place, ahead of shopping centres. In this market sector, which only accounted for 14% of French retail investment
               volumes, yields saw new upward pressure, indicative of investors’ wait-and-see attitude

                                                                                                                                                                       2
Economic
 context
FRENCH RETAIL PROPERTY MARKET
ECONOMIC CONTEXT

Temporary slowdown                                                                                                                    On the right track
French economic indicators                                                                                                     Change in unemployment rate
Annual growth as a %, unless otherwise indicated                                                                                               % of active population

                                                                                       12
  Indicator                                2016       2017   2018f   2019f

  GDP                                      1,1        2,3    1,8     1,7
                                                                                       10

  Inflation                                0,3        1,2    2,0     1,5                                                                                              8.9

                                                                                        8                                                                             8.0
  Household consumption                    2,0        1,1    1,1     1,6

  Household income¹                        1,8        1,4    1,2     2,0
                                                                                        6

                                                                                                                                                Metropolitan France
  Unemployment (whole of France)           10,1       9,4    9,1     8,8                                                                        Ile-de-France

                                                                                        4
                                                                                            12341234123412341234123412341234123412341
¹Household real gross disposable income.
                                                                                            2008   2009   2010   2011   2012   2013   2014   2015   2016   20172018

Source: Banque de France, Macroeconomic projections                                                                                                  Source: INSEE

• As with most other advanced economies, French GDP growth has clearly slowed down since the start of 2018, with growth limited to 0.3 % as at
  Q2 following growth of 0.2 % in Q1. However, activity should strengthen in coming months as a result of expected increases in company
  investment and household consumption.
• In spite of a lower level than in 2017, the upturn in employment remains on the right track. Following the creation of 333,000 private sector jobs
  last year, more than 160,000 will be created in 2018, contributing to the progressive fall in unemployment. The unemployment rate should soon drop
  below 9%, a level that in spite of everything remains clearly above that of the European average (7 % at the end of May 2018, within the EU28).                           4
FRENCH RETAIL PROPERTY MARKET
ECONOMIC CONTEXT

Rebound expected…in 2019                                                                                              Decreasing morale
Household consumption                                                                                                         Household opinion
In France, % of annual change in volume                                                                             Summary indicator – CVS-CJO data

                                                                              130

                                                                              120
                                 2.00%

                                                                              110
                                                            1.60%

                                                                     1.60%
                        1.40%

                                                                              100
                                          1.10%

                                                   1.10%
               0.80%

                                                                              90
      0.60%

                                                                              80

                                                                                    mars-00

                                                                                    mars-07

                                                                                    mars-14
                                                                                      oct-00

                                                                                     juin-05

                                                                                      oct-07

                                                                                     juin-12

                                                                                      oct-14
                                                                                     mai-01

                                                                                      avr-04

                                                                                    janv-06

                                                                                     mai-08

                                                                                      avr-11

                                                                                    janv-13

                                                                                     mai-15

                                                                                      avr-18
                                                                                     déc-01

                                                                                     févr-03

                                                                                     nov-04

                                                                                     déc-08

                                                                                     févr-10

                                                                                     nov-11

                                                                                     déc-15

                                                                                     févr-17
                                                                                      juil-02

                                                                                    sept-03

                                                                                      juil-09

                                                                                    sept-10

                                                                                      juil-16

                                                                                    sept-17
                                                                                    août-06

                                                                                    août-13
     2013     2014     2015     2016     2017     2018f    2019f    2020f

Source: Banque de France, Macroeconomic projections                                                                                  Source: INSEE

• Having slowed down in 2017, household consumption will remain sluggish in 2018 due to the increases in purchase power being worn away by
  the increase in inflation (+ 2.0 % in 2018, following + 1.2 % in 2017).
• Nevertheless, French spending should increase during the second half of the year and will probably maintain a steady pace in 2019 and 2020 due
  to the continued improvement in the job market, wage gains and more favourable tax measures (suppression of council tax, decrease in employee
  contributions).                                                                                                                                      5
FRENCH RETAIL PROPERTY MARKET
  ECONOMIC CONTEXT

     THE WINNERS…

                  Organic products
                           +17% in value in 2017
                         +250 new shops in 2017
                                                                                   Sports goods
                                                                                   +4% in value in 2017
                                                                                   +9 - 10% for the “women’s” category
         Garden centres
                +4% in value in 2017

                                                                        Beauty products
                                                                        +3% in value in 2017
                                  Bazaars                               Online perfume sales: +27% in 2017
                  +19.3% in value in 2017
                 335 shops (+115 in 2017)

                                                                                                      …AND LOSERS

                                                         Hypermarkets            Shoes
      Market share / all products: 29.3% in 2017 (32.6% in 2012)                 -4.4% in value in 2017
Market share / non-food products: 12.8% in 2017 (17.7% in 2012)                  -12% of shops > 400 m² between 2012 and 2017

                                     Clothing / Textile                          Books
                                                                                 -0.8% in value in 2017
                                        -13% in 10 years
                                                                                 E-books: +9% in 2017
  - 2.8% in 2018 at end of May, following +0.6% in 2017

                                                                                       Toys
                                                                                       -3.8% in value in 2017
     Sources: INSEE* / Union Sport & Cycle / IFM / NPD
     *Large specialist retailer figures/Annual change                                  Share of online sales: 24.9%
                                                                                                                            6
FRENCH RETAIL PROPERTY MARKET
ECONOMIC CONTEXT

Towards new peaks                                                                                                 Foreigners driving growth
Change in number of hotel arrivals                                                                                  Change in number of hotel arrivals
In the Greater Paris Region, as at 1st quarter each year                                                                          In the Greater Paris Region

400000
               ▲ 14%
350000
                                                                                                                                    Foreign tourists
300000                          ▲ 15%
                                                                                                                                                +16.5%
250000                                                                                                                              Q1 2018 / Q1 2017

200000                                      ▲ 31%
                                                            ▲ 5%
150000
                                                                          ▲ 21%
100000
                                                                                        ▲ 17%
                                                                                                                                     French tourists
50000
                                                                                                                                                   +0.2%
     0                                                                                                                              Q1 2018 / Q1 2017
         United States      UK          Germany         China          Japan         Russia

                         2016    2017   2018

Source: Paris Tourist Office / Red box: annual growth between Q1 2017 and Q1 2018.                                                 Source: Paris Tourist Office

• Following a record level in 2017, tourist numbers continue to increase in 2018 in the Greater Paris Region, with a 7% increase year-on-year in
  the number of hotel stays during the 1st quarter, related to the dynamism of the international clientele (+16.5%, compared to +0.2% for the French).
• Almost all nationalities show an increase, to varying degrees depending on the continent. For once, Europe saw the greatest increase year-on-
  year (+19%), partly related to the rebound in arrivals of the Germans and Spaniards, and the return of the British. The increase in Asians is more
  modest (+10.8%) due to the slowdown in growth of Chinese arrivals.                                                                                              7
FRENCH RETAIL PROPERTY MARKET
ECONOMIC CONTEXT

Strong growth in Paris…                                                                                                        …and the regions
Rate of Sunday openings in international tourist zones                                     Rate of Sunday openings in international tourist zones
In Paris, according to activity sector as a %                                                                                       In regions, by town as a %

         Food                              Luxury            Other                          City                       End of January       End of December
                                                                                                                           2017                   2017

                                                                                            Antibes                         12%                   15%

                                                                                            Cagnes-sur-Mer                  26%                   45%
                                                 11%                   27%
                                                       31%       16%
                                                                                            Cannes                          10%                   49%
                  43%
                                                                                            Deauville                       70%                   75%
                      63%
                                                                                            Dijon                          ˂10%                   51%

                                                                                            La Baule                        49%                   56%

                                                                                            Nice                            32%                   36%

                                                                                            Saint-Laurent-du-Var            37%                  ˃80%
    Before the measure         End of Septembre 2017

Source: French Ministry of Economy and Finance                                                                     Source: French Ministry of Economy and Finance

• Almost three years after the adoption of the Macron Law, a new assessment made by the Ministry of the Economy confirms the increase in Sunday
  openings of shops in Paris, going from an average of 17.4% before the measure to 30.4% in September 2017.
• The analysis is the same outside of Paris, where 44% of shops located in international tourist zones opened on a Sunday at the end of 2017,
  compared to 25% at the start of the year.
                                                                                                                                                                    8
Brand strategies &
  retail formats

FRENCH RETAIL PROPERTY MARKET
BRAND STRATEGIES & RETAIL FORMATS

Increase of 14% expected in 2018                                                                                                          A general increase
E-commerce sales                                                                                                            E-commerce market shares per sector
In France                                                                                                                           In France, estimations in 2017 as a %

100                                                                                               50%

 90
                                                                                                        Cultural products     High-tech                      Clothing
              34%

 80                                                                                               40%
       33%

 70
                     28%

                            25%

                                   24%

 60                                                                                               30%
                                          22%

                                                 19%

                                                                                                                                                                    13%
 50                                                                                                                                  23%

                                                                             15%
                                                                      14%
                                                        14%

                                                                                    14%

                                                                                           14%
 40                                                                                               20%                 45%
                                                               12%

 30

 20                                                                                               10%
              15.6

                     20.0

                            25.0

                                   31.0

                                          37.7

                                                 45.0

                                                        51.1

                                                               57.5

                                                                      64.9

                                                                             72.0

                                                                                    81.7

                                                                                           93.2
 10
       11.6

  0                                                                                               0%
      2006 2007 2008 2009 2010 2011 2012 2013 2014 2015 2016 2017 2018f

                       Sales (€ billion)                       Annual growth (%)

Source: Fevad                                                                                                                             Sources: Fevad / GFK / IFM / Nielsen

• Internet sales increased by 14% in 2017 to reach almost 82 billion euros. Mobile devices accounted for 21% of this total (+50% year-on-year),
  compared to barely 2% five years ago.
• In 2018, online sales should reach more than 93 billion euros, putting France in second place in Europe, behind the United Kingdom (178 billion)
  and equal with Germany, but well ahead of other large European countries such as Italy and Spain (28 billion each).
                                                                                                                                                                            10
FRENCH RETAIL PROPERTY MARKET
BRAND STRATEGIES & RETAIL FORMATS
An ongoing revolution
Number of new concepts per year Highly sought-after formats The joint development
All sectors, in France of physical and virtual worlds
POP-UP
STORES
292
253
248
236
SHOP-IN-
SHOPS
2014 2015 2016 2017 SINGLE-
BRAND
STORES
Source: La Correspondance de l’Enseigne
• This is a time for multi-faceted approaches, merging and commercial innovation. Shop-in-shops, pop-up stores, showrooms and single-brand
stores, brand associations…. terms and formats are not lacking, revealing a deeply changed commercial.
• The joint development of physical and virtual worlds, illustrated by the digitalisation of points of sale and the incursion of “pure-players” in the field
of physical retail (AMPM, Birchbox, etc.), also continues to manifest itself as an increase in alliances between traditional retailers and internet
players (Monoprix/Sarenza, André/Spartoo, Carrefour/Google, etc.). 11FRENCH RETAIL PROPERTY MARKET
BRAND STRATEGIES & RETAIL FORMATS
Type of location
Expansion projects that combine formats Out-of-town
Examples of developing brands Shopping centres
In France, by activity
High street
Sources: Knight Frank, press and brands
FASHION / SPORTSWEAR RESTAURANT FOOD DISCOUNT / BAZAARS OTHERS
Calzedonia Au Bureau Ange Action Adopt’
Chaussea Beef House Bio C Bon Centrakor Amazing Jewelry
Décathlon Bistro Régent Biocoop Easy Cash Basic Fit
Intersport Burger King Day by Day Gifi Cultura
JD Sport Five Guys Grand Frais Hema Darty
Kiabi La Pizza de Nico Kusmi Tea La Foir’Fouille Fnac
Primark O’Tacos La Vie Claire Maxi Bazar La Redoute
Superdry Pitaya Marie Blachère Noz Orchestra
Takko Steak n’ Shake Naturalia Stokomani Parfois
Uniqlo Vapiano NaturéO Tiger Rituals
Women’secret Yogurt Factory Nespresso Zeeman Sostrene Grene
12The rental market High streets
FRENCH RETAIL PROPERTY MARKET
HIGH STREETS | PARIS

Continued dynamism
Trends in the Parisian high streets retail market

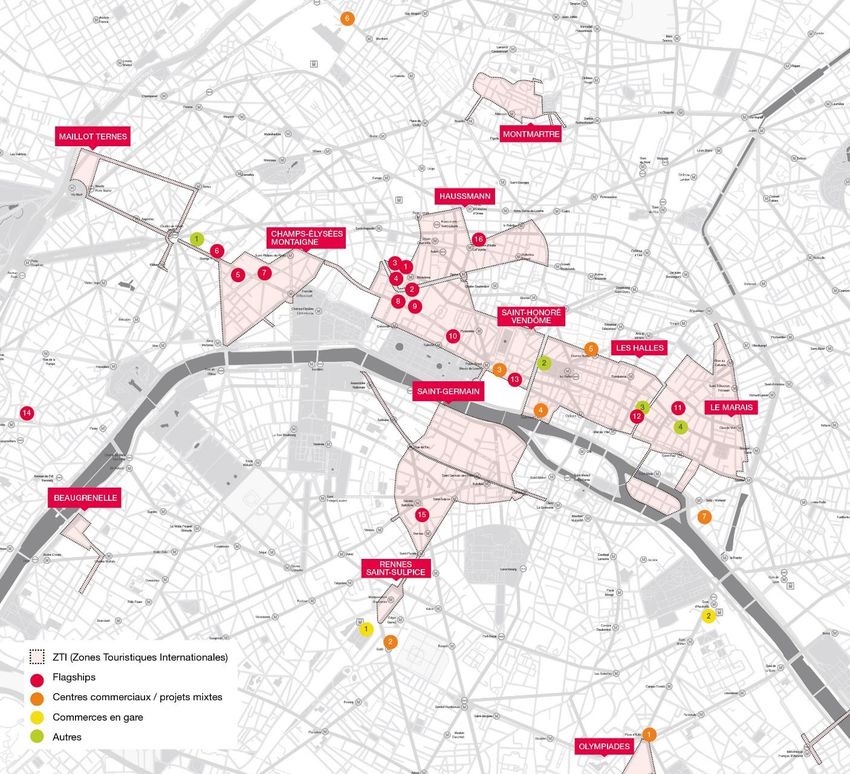
• Hotel arrivals increased by 7.4% year-on-year in the Paris region. The          Rossignol has just taken over the Basler shop at 21 boulevard des
  increase is 16.5% for foreign visitors. This dynamism benefits the              Capucines.
  retail market, particularly within international tourist zones (ITZ).
                                                                                • The analysis of the different Parisian retail sectors does not really show
  Moreover, the ITZs concentrate most new flagship projects, as well as
                                                                                  any new trends. Rue Saint-Honoré remains one of the most lively
  most operations to create or renovate luxury hotels in the capital.
                                                                                  streets, with the advancing works to future large flagship stores
• The busiest streets are still the main targets of international brands          (Chanel, Graff, Saint Laurent, etc.), new openings (Akillis, Isabel Marant,
  looking to optimise their communications and offer their clients a              Moschino, Herno, Hervé Chapelier, Marni, Serge Lutens, etc.) and
  more qualitative and updated shopping experience, like H&M with                 recent deals (Balmain).
  their flagship store at 1-3 rue La Fayette over almost 5,000 m². Whilst
                                                                                • On the Champs-Élysées, certain or potential refurbishment projects
  retailer movements are less numerous than a few years ago, the mass
                                                                                  remain numerous and continue to drive the avenue, which is more and
  fashion giants continue to play an important role in this, especially given
                                                                                  more dedicated to flagship stores. These changes, in light of recent
  that the disposals they undertake to streamline their network help to
                                                                                  and ongoing transactions, will likely intensify the avenue's
  drive the market (Balmain instead of Zara at 374 rue Saint-Honoré).
                                                                                  upmarket move.
• Several other types of player are active: luxury brands and fashion
                                                                                • Dormant for some time, the Left Bank seems to be making a
  designers, the food and restaurant sectors, sport, cosmetics and
                                                                                  comeback. Brands (Tumi, Salomon), recent players (Five Guys) and
  decoration account for a significant share of openings. Such a range of
                                                                                  new concepts (From Future, Décathlon City) are all active there; the start
  players and concepts conveys the effervescence and upmarket move
                                                                                  of an increase in activity that has been seen in the mid and upmarket
  of the capital’s very heart.
                                                                                  sectors, but which has not yet been seen in the luxury sector, in spite of
• This effervescence is also indicative of tests undertaken by brands to          the reopening of Lutétia Hotel.
  adapt their models to new consumer expectations and to take advantage
                                                                                • The effervescence of the Parisian market is not expressing itself by a
  of changes in buying patterns (Leroy-Merlin at Madeleine and in the
                                                                                  generalised increase in prices. Rental values remain generally stable
  Batignolles area, the new AMPM flagship store on rue Étienne Marcel,
                                                                                  in the capital. Whilst these could still increase on a limited number of
  etc.).
                                                                                  streets, they are suffering from downward pressure on some good
• Furthermore, the trend for brands to undertake their own distribution           streets due to brand’s profitability requirements and high prices that
  is increasing in the cosmetics, luggage and sport sectors. After                have been reached in recent years.
  Fusalp in the Marais and Salomon on boulevard Saint-Germain,
                                                                                                                                                          14
FRENCH RETAIL PROPERTY MARKET
HIGH STREETS | PARIS
Examples of recent transactions in Paris
Source: Knight Frank
Retailer Address District Total area ZA rent
(m²) (€/m²)
IKEA 23 boulevard de la Madeleine Paris 1 6,000 Confidential
AMPM 49 rue Etienne Marcel Paris 1 564 1,700
HEMA 3 rue du Havre Paris 9 316 2,400
Future IKEA store, 23 bd de la Madeleine, Paris 1
ROSSIGNOL 21 boulevard des Capucines Paris 2 300 2,940
TUMI 17 rue du Vieux Colombier Paris 6 240 2,670
BAP 16 boulevard des Capucines Paris 9 220 3,250
DYPTIQUE 56 rue de Passy Paris 16 220 3,370
SALOMON 129 boulevard Saint-Germain Paris 6 211 2,770
HUGO BOSS 118 rue Vieille du Temple Paris 3 168 2,350 Salomon, 129 bd Saint-Germain, Paris 6
TUMI 63 Avenue des Champs-Élysées Paris 8 165 15,970
FOOTPATROL (JD SPORT) 45 rue du Temple Paris 4 110 1,160
SERGE LUTENS 324 rue Saint-Honoré Paris 1 87 10,000
L’OCCITANE 144 rue de Rennes Paris 6 86 3,060
DUPONT ST 10 rue de la Paix Paris 2 50 6,200 Foot Patrol, 45 rue du Temple, Paris 4
15
Note: rounded valuesFRENCH RETAIL PROPERTY MARKET
HIGH STREETS | PARIS
Record in sight Alignment of the planets
Worldwide sale of luxury items An array of favourable factors
300 50%
Boom in
250
40% online
sales
30% Rise in
200 tourism
Increase in spending
13%
10%
12%
from Chinese consumers
6 - 8%
11%
20%
150
7%
4%
3%
3%
10%
0% Success of
-2%
-2%
100 beauty and
-8%
0% accessories
50 276 - 281 -10% Local
consumption
159
170
167
153
173
192
212
218
224
251
250
260
0 -20% Millenials
2006 2007 2008 2009 2010 2011 2012 2013 2014 2015 2016 2017 2018f
Sales (€ billion) Annual growth (%)
Source: Bain & Company Sources: Bain & Company / Knight Frank
• After a slowdown in 2016 and then an increase last year, luxury sales should once more gain strength in 2018. The increase for this year will
thus be comprised between 6 and 8%, driven by the dynamism of sales in Asia (between 9 and 11%).
• The luxury industry is benefitting from an array of structural and temporary favourable factors, ensuring durable growth in the long-term. Among
these factors are the continued rise in international tourism (worldwide increase in arrivals of 3.3% per year between 2010 and 2030), as well as
the growing adjustment of luxury brands to new consumption methods (digitalisation, expectations of millenials, etc).
16FRENCH RETAIL PROPERTY MARKET
HIGH STREETS | PARIS
Recovery still to be confirmed
Focus on the luxury Paris market
Breakdown of openings per street
Change in number of luxury shop openings
Share as a %, out of total openings in Paris
In Paris
2018 Rue Saint-Honoré
52
50
Avenue Montaigne
39 23% 24%
37
24% 22% Vendôme / Paix
28
Faubourg Saint-Honoré
4% 2012-2017
8% 12%
7% Sèvres / Saint-Germain
13%
10% 12% George V / François 1er
11% 11%
5% 11% Champs-Elysées
Annual average 2015 2016 2017 2018* 5%
2012-2017
Autres
¹Survey undertaken at the end of June 2018.
Source: Knight Frank Source: Knight Frank
• More than thirty definite and potential openings are expected over 2018, equating to an increase of more than 30% already compared to
openings that took place in 2017.
• Three streets have confirmed their dynamism: rue Saint-Honoré, avenue Montaigne and the Place Vendôme / Rue de la Paix area concentrate
nearly 50% of openings in 2018, a share equivalent to that of the last five years. Whilst the Champs-Élysées has seen their share increase,
thereby confirming its upmarket move, others are less dynamic, for example rue du Faubourg Saint-Honoré and the Left Bank. 17FRENCH RETAIL PROPERTY MARKET
HIGH STREETS | PARIS
A larger supply of high-end accomodations
Luxury hotels in Paris: recent and future openings
Source: Knight Frank
18FRENCH RETAIL PROPERTY MARKET
HIGH STREETS | PARIS
Few changes…
Prime rental values, in Paris, in €/sq m/year Zone A*
Changes in prime rental values
Street or retail area District Rent Rent Trend Between 2006 and 2018, on some Parisian
as at Q2 2017 as at Q2 2018 streets, in €/sq m/year Zone A*
25,000
Avenue des Champs-Élysées Paris 8 20,000 20,000
20,000
Avenue Montaigne Paris 8 15,000 15,000
15,000
Rue du Faubourg Saint-Honoré Paris 8 15,000 15,000
10,000
Rue Saint-Honoré Paris 1 12,000 12,000 5,000
-
Boulevard Haussmann Paris 8 / 9 6,000 6,000
Q2 2018
2006
2007
2008
2009
2010
2011
2012
2013
2014
2015
2016
2017
Sèvres / Saint-Germain Paris 6 / 7 6,000 6,000
Champs-Elysees
Marais Paris 3 / 4 5,000 5,000 Avenue Montaigne
Rue Saint-Honoré
Rue des Francs-Bourgeois
Capucines / Madeleine Paris 1 / 2 / 8 / 9 4,000 4,000
Source: Knight Frank
Rue de Rivoli Paris 1 / 4 3,500 4,000
Rue de Passy Paris 16 2,500 3,000
*Rental value: decapitalised rent + assignment (leasehold/business) 19FRENCH RETAIL PROPERTY MARKET
HIGH STREETS | PARIS
Change is in the air
Examples of recent and upcoming projects
In Paris, between 2017 and 2021
Source: Knight Frank
20FRENCH RETAIL PROPERTY MARKET
HIGH STREETS | REGIONS
Supply undergoing strong renewal
Trends in the high streets retail market in the regions
• A record number of new companies in Lyon, an unemployment rate at thus continue to spread, following the inspiring examples of some large
its lowest level since 2008 in Nantes, the number of overnight stays at European cities, such as “Time Out Market” in Lisbon and “Foodhallen”
its highest level for 15 years on the Côte d’Azur, a strong increase in in Amsterdam.
the number of foreign visitors in Bordeaux… For several months,
• Large refurbishment projects remain numerous. They constitute
macro-economic indicators have been green in the largest regional
both new establishment solutions for brands, as well as an important
cities, supporting the dynamism of their retail property markets.
opportunity for large cities to regenerate and strengthen their retail offer.
• This vigour first and foremost benefits the best retail pitches, where Following the Grand Hôtel Dieu, inaugurated at the end of April in Lyon,
several flagship stores have recently opened or are expected, for recent news was dominated by the progress of the mixed-use
example Primark in Toulouse and Strasbourg, Uniqlo in Rennes, “Iconic” project in Nice and the call for proposals undertaken within
Toulouse and Nantes, and Zara in Vieux Lille. Certain large mass- the scope of the transformation of the Palais du Commerce in
market brands are also continuing to move their pawns into smaller Rennes.
towns, for example the recent opening of H&M in Vannes and the
• Finally, certain projects related to the vacating of large areas seen in
future opening of a Swedish brand by 2019 in Agen.
recent years in town centres are being implemented, for example, the
• Like in Paris, mass-market fashion brands are also helping to animate upcoming launch of the marketing of the former Galeries Lafayette
the market through their transfers. JD Sports has thus just taken two building in Marseille, and the CDAC authorisation that has been
former H&M shops on rue de la République in Lyon and avenue Jean obtained for the creation of 5,000 m² of retail in Bordeaux’s former
Médecin in Nice. Other sectors, other than sport, are also Virgin Megastore.
supporting activity in regional retail streets, such as beauty (L’Oréal
• The stabilising of prime rental values seen in 2017 has been
in Lyon, Rituals in Rouen, etc.), decoration (AMPM in Lille, Sarah
confirmed since the start of 2018. Lyon and Bordeaux show the highest
Lavoine in Bordeaux, etc.), and the urban format of brands who are
rental values (€ 2,500 /sq m/year, sometimes more, for the best
more typically found in out-of-town locations (Truffaut in Toulouse,
locations). Nice completes the podium. Other regional capitals, such as
Boulanger “Le Comptoir” in Rouen, H&H in Lyon, etc.).
Strasbourg and Toulouse, follow with rental values of between €2,000
• The restaurant sector also remains very active, like the new and 2,200 /sq m/year, levels that have been seen for several years
openings of successful brands (Big Mamma in Lille, after Five Guys and now.
Big Fernand) and the growth in “food hall” projects (“Halle Bocca” in
Bordeaux, the former “Halles Alstom” in Nantes, etc.). These formats
21FRENCH RETAIL PROPERTY MARKET
HIGH STREETS | REGIONS
Significant arrivals
Examples of openings and recent projects in the regions
Source: Knight Frank LILLE
Zara / Zara Home
ROUEN AMPM
Rituals Boggi
Tiger Big Mamma
Boulanger
RENNES
Uniqlo
Nespresso AMIENS
Mauboussin STRASBOURG
Courir Primark
Hugo Boss
VANNES
Starbucks
H&M
Samsonite
NANTES LYON
Uniqlo JD Sports
COS L’Oréal
Superdry Ba&sh GRENOBLE
Bensimon / Home Kujten Hema
BORDEAUX
Former Virgin Megastore
Lalique NICE
Sarah Lavoine JD Sports
Balibaris Sœur
Cities in the Top 10 French AGEN
urban areas H&M
CANNES
Sneakers Specialist
TOULOUSE AIX / MARSEILLE Akris
Other cities Primark Five Guys Dolce & Gabbana
Uniqlo Philipp Plein Oysho
Truffaut Scotch & Soda Seafolly
22FRENCH RETAIL PROPERTY MARKET
HIGH STREETS | REGIONS
Stabilising of rental values
In the regions, end Q2 2018, in €/sq m/year Zone A*
Source: Knight Frank
Lyon 2,200 / 2,500
Bordeaux 2,200 / 2,400
Nice 2,200 / 2,400
Lille 1,800 / 2,000
Toulouse 1,800 / 2,000
Strasbourg 1,800 / 2,000
Marseille 1,500 / 1,700
Nantes 1,400 / 1,600
€0 € 500 € 1,000 € 1,500 € 2,000 € 2,500 € 3,000
*Rental value: decapitalised rent + assignment (leasehold/business)
23The rental market Retail complexes
FRENCH RETAIL PROPERTY MARKET
SHOPPING CENTRES

Opening up
Market trends in the French shopping centre market

• Several new centres opened during the 1st half of            diversity also enables the loss of impetus of          TOP 10 of the largest French
  2018 (“Le Prado” in Marseille, “B’Est” in Lorraine,          certain traditional players in the shopping centre     shopping centres
  “Grand Hôtel Dieu” in Lyon). However, the                    market to be compensated. As such, fashion             Area in thousands of m²
  dominant trend remains that of a slowdown of                 continues with arbitrations, assigning certain shops
  new creations to the benefit of improvements to              whilst at the same time opening large flagship
  existing centres, as recently demonstrated by the            stores.                                                      Vélizy 2                     106
  launch of some significant extension and/or
                                                             • This trend first and foremost benefits the most         Mondeville 2                      108
  renovation projects (“Les Trois Fontaines” in Cergy,
                                                               visited regional shopping centres, which remain the
  “Créteil Soleil”, “Italik” in Paris, etc.).
                                                               main target of international brands and the                 Rosny 2                        112
• Whilst the different types of centres (retail galleries,     most upmarket players. Among the most
  regional centres, city-centre shopping centres) are          significant movements, Galeries Lafayette has          Grand Littoral                       119
  not all impacted in the same way, all operators are          just made the opening of a new shop in
                                                                                                                             Parly 2                       123
  making an effort to renew the supply.                        Beaugrenelle official, following the recent opening
                                                               of shops in Prado in Marseille and in the Carré         Créteil Soleil
• Shopping centres have thus entered a new era,                                                                                                             125
                                                               Sénart extension.
  that of an opening up of centres that was
                                                                                                                      Carré Sénart                          130
  needed by a model weakened by the rise in e-               • The latest changes in the shopping centre market
  commerce, new consumer expectations and the                  also show the desire to open shopping centres           La Part-Dieu                             132
  requirements of brands looking to reduce their               up to their surroundings: through the
  costs and increase their arbitrations.                       development of hybrid concepts (“Open Sky”) but        Les 4 Temps                               139
                                                               also by developing activities without a direct
• This opening up is expressed through a wider                                                                          Belle Epine                             141
                                                               connection to the retail function (coworking areas,
  variety of supply, with the welcoming of new
                                                               medical centres, etc.).
  brands from the high street or out-of-town
  locations, the more frequent resorting to kiosks and       • Finally, emphasis is placed on the digital,
  temporary boutiques, and a growing share of sport,           notably with the aim of providing a seamless               Centres located in the Paris region
  leisure and restaurant brands. In reply to the               shopping experience.
  changes in buying behaviour, this wider range of                                                                    Source: LSA
                                                                                                                                                                      25
FRENCH RETAIL PROPERTY MARKET
SHOPPING CENTRES
A busy 1st half of 2018
Examples of significant shopping centre openings and projects
Source: Knight Frank
2018
Share of shopping centre creations
Centre Town Type Area (m²)
in France
B’Est Farebersviller (57) Creation 55,000 As a % of the total volume of openings
Le Prado Marseille (13) Creation 23,000 2018
Leclerc Baleone Sarrola-Carcopino (2A) Creation 18,000
Grand Hôtel Dieu Lyon (69) Creation 17,000
La Lézarde Montivilliers (76) Extension 15,000
38% 40%
Shop’In Houssen Colmar (68) Extension 5,200
2017
Note: pink box= projects already opened
2019
Centre Town Type Area (m²)
Lillenium Lille (59) Creation 56,000
Open Sky Plaisir (78) Redevelopment 37,000
Creations
Cap 3000 Saint-Laurent-du-Var (06) Extension 32,500
Vélizy 2 Vélizy-Villacoublay (78) Extension 19,970
Italik Paris (75013) Extension 7,000 Sources: Knight Frank, CNCC
Les Berges de l’Ourcq Les Pavillons-sous-Bois (93) Creation 6,800 26FRENCH RETAIL PROPERTY MARKET
RETAIL PARKS
Practicality, proximity, profitability…and quality
Trends in the French retail park market
• Following 480,000 m² in 2017, almost 200,000 m² discount stores continue to expand and take Year-on-year change in T/O of
specialist retail
has already been opened since the start of 2018, advantage of, notably, transfers undertaken by
Accumulation January-May 2018
including some large, regional projects (“Les other brands. Stokomani and Centrakor recently
Océanides” near Bordeaux, “Cap Saran” near took over several Fly shops. Furthermore, Gifi is
Orléans, “Frunshopping” in south Nancy etc.). about to take over Besson Chaussures, having
Several complexes ˃ 10,000 m² will open in the 2nd bought Tati a few months ago. Town centre Out-of-town
0
half of the year, including “PAC de Chalezeule”
• That being said, out-of-town locations are not
-3.5
-3.2
-2.2
-2.6
-1.9
-4
close to Besançon and “L’Aren’Park” in Cergy. -0.5
retail’s poor sibling. Fashion, for example, is more
-1
• In 2019, some large scale projects are expected, present than previously, with a wider range of
such as “Steel” in Saint-Étienne and the “Puisoz” formats and levels. This is also the case with sport -1.5
site in Vénissieux, near Lyon. which, at the same time as the expansion of the -2
usual suspects (Intersport) or tests undertaken by
• Contrasting with the slowdown in developments of -2.5
new brands (JD Sports), is seeing the number of
new shopping centres, the pace of creation of retail -3
gym implantations multiplying (Basic Fit, Fitness
parks remains sustained. Size and flexibility of the -3.5
Park, etc.); a success that is indicative of the
premises, ease of access and parking, occupancy
growing position more generally given to -4
costs noticeably lower than those of other retail
leisure, whose new concepts continue to -4.5
formats: the model meets the practicality and
expand, for example, the “B’Fun” space that
proximity requirements of the ever increasing
recently opened in Farébersviller to complete the City centre including:
number of suburban consumers, as well as the
offer in the “B’Est” shopping cetre. Shops in shopping centres
profitability logic of brands.
High street shops
• Finally, food and restaurant brands are also more
• The good value for money of out-of-town formats,
present, driven by the boom in franchising and the Out of town including :
and their success with consumers, explains the
desire of brands to create dedicated hubs which Shops in shopping centres
broadening demand of a growing number of brands.
have a wider and more qualitative offer. Large & medium size units
Low cost brands admittedly continue to make up the
DNA of the retail park market. Bazaars and
Source: Procos
27FRENCH RETAIL PROPERTY MARKET
RETAIL PARKS
A sustained pace of development
Examples of significant retail park openings and projects
Source: Knight Frank
2018
Centre Town Type Area (m²) Share of retail park creations in France
As a %, out of the total volume of
Les Promenades de Brétigny Brétigny-sur-Orge (91) Creation 49,000 openings
La Sucrerie Abbeville (80) Creation 30,000
2018
Cap Saran Saran (45) Creation 29,200
Frunshopping Nancy Sud Saint-Nicolas-de-Port (54) Creation 23,000
Les Océanides La Teste-de-Buch (33) Creation 22,000
Aren’Park Cergy-Pontoise (95) Creation 20,000
2017
Note: pink box= projects already opened
2019
81%
73%
Centre Town Type Area (m²)
Steel Saint-Étienne (42) Creation 70,000
Puisoz Vénissieux (69) Creation 50,000
Creations
Wood Shop Cesson (77) Redevelopment 42,000
Eden 2 Servon (77) Creation 35,000
Shopping Promenade Arles (13) Creation 19,000 Sources: Knight Frank, CNCC
Frunshopping Fourmies Fourmies (59) Creation 13,000 28FRENCH RETAIL PROPERTY MARKET
DESIGNER OUTLETS
More and more sought after
Trends in the French designer outlet market
• With a stock totalling more than 500,000 m² that is • In spite of the specific features of this distribution Gross lettable area worldwide
mainly located in the north of the country, designer format, France still has a relatively significant For 1,000 inhabitants, in m²
outlets only account for a limited share of the development potential, in certain regions with
retail market in France. little current stock in particular, and owing to the
success of the format with consumers.
• In recent years, projects have continued to multiply. Germany 1
As such, almost 150,000 m² have opened since • Furthermore, a growing number of brands are
the start of the 2010s, including approximately expanding their presence within designer outlet Poland 2.5
35,000 m² in 2017 with the extension of Romans- centres, such as department stores (Galeries
sur-Isère and the opening of two new centres: Lafayette), and several brands of accessible luxury
France 4.1
“Honfleur Normandy Outlet” and “McArthurGlen (The Kooples, the SMCP group, Zadig & Voltaire,
Provence” in Miramas close to Marseille. etc.). Others are opening their first shop, for
example, Rituals in ”Villefontaine”. Spain 4.4
• The 1st half of 2018 saw the opening of “The
Village” in Villefontaine, near Lyon. With an area • Indeed, designer outlets have reinvented Italy 7.6
of 25,000 m², this new designer outlet, developed themselves and now better fit the needs of
by Compagnie de Phalsbourg, has some 80 consumers and brands. They thus offer a more
Portugal 7.8
brands including Galeries Lafayette who have thought out buying environment and architecture,
almost 1,500 m². as well as more diversified and more upmarket
concepts, very different to the first factory outlet UK 13.9
• The pace of development of new designer outlet
centres of the 1980s.
centres shouldn’t weaken. As such, almost
USA 20.8
180,000 m² could potentially be completed by
2021. Some will supplement stock in regions that
already have some (the Greater Paris Region with
“City Outlets Paris” in Romainville). Others will be Source: Neinver/ICSC
the 1st opening, for example “Viaduc Village” in La
Cavalerie, in Aveyron.
29FRENCH RETAIL PROPERTY MARKET
DESIGNER OUTLETS
Some projects…and a lot of uncertainty
Examples of significant designer outlet openings and projects
Source: Knight Frank
Opening Centre Town Type Area (m²)
2011 Nailloux Outlet Village Nailloux (31) Creation 24,800
Change in openings in France
In m², total volume per year*
2012 The Style Outlets Roppenheim (67) Creation 27,300
2013 One Nation Paris Les-Clayes-sous-Bois (78) Creation 24,000
70000
2015 Marques Avenue A13 Aubergenville (78) Redevelopment 13,700
60000
2017 Honfleur Normandy Outlet Honfleur Creation 12,700
50000
2017 McArthurGlen Provence Miramas Creation 25,000
40000
Opening Centre Town Type Area (m²)
30000
2018 The Village Villefontaine (38) Creation 25,000
20000
2019 Viaduc Village (Phase 1) La Cavalerie (12) Creation 7,500
2019 L’Escale Hautmont (59) Creation 19,900 10000
2019 City Outlets Paris Romainville (93) Creation 20,000 0
2011
2012
2013
2014
2015
2016
2017
2018
2019
2020
2021
2020 Village des Alpes Châtillon-en-Michaille (01) Creation 16,000
2021 Village de marques Coutras (33) Creation 13,000
Source: Knight Frank
2021 Village de marques Sorigny (37) Creation 20,000 *Definite and potential projects
Note: pink box= projects already opened 30The investment market
FRENCH RETAIL PROPERTY MARKET
INVESTMENT MARKET
H1 2018 H1 2017 TREND
Retail investment volume in France €1.6 billion €1.3 billion
Share of retail* 14% 16%
Number of transactions > €100 million 4 3
Share of Ile-de-France** 53% 52%
Share of foreign investors** 55% 30%
Prime yield | High streets 2.75% 2.75%
Prime yield | Shopping centres 4.25% 3.75%
Prime yield | Retail parks 5.00% 4.75%
Source: Knight Frank
* On total investment in France,all asset types – excluding non divisible portfolios.
** On total retail investment in France.
32FRENCH RETAIL PROPERTY MARKET
INVESTMENT MARKET
A deceptive increase
Change in retail investment volumes
In France
Source: Knight Frank
€ 30,000 35%
30%
€ 25,000
25%
€ 20,000
20%
€ 15,000
+23%
14%
15%
€ 10,000 In one year
10%
€ 5,000
5%
€ 1,560
€0 0%
2007 2008 2009 2010 2011 2012 2013 2014 2015 2016 2017 1S
2018
Investment volume in France Retail investment volume in France Retail share (%)
• Almost 1.6 billion euros were invested in the French retail market during the 1st half of 2018, equating to 14% of total corporate real estate
volume, and an increase of 23% year-on-year. This increase is deceptive because it is due to one exceptional deal undertaken by Hines, for
BVK, of the future Apple Store on the Champs-Elysées for almost 600 million euros.
• Retail activity remains limited by the imbalance between available supply and investor demand, whose selective nature has increased and is
now widespread across all asset classes.
33FRENCH RETAIL PROPERTY MARKET
INVESTMENT MARKET
Paris accounts for almost half of volume
Geographic breakdown of retail investment volumes
In France
Source: Knight Frank TOP 3 | Deals in H1 2018*
Regions Paris / IDF
H1 2018
114 Champs-El.
Grand Vitrolles
3%
9%
24%
277 Saint-Honoré
Paris
Ste-Catherine
Promenade
47% Ile-de-France (excl. Inner Paris)
44% 2017
Regions
13%
Non-divisible portfolios
54%
St-Priest Retail Park
Lutèce portfolio
6%
Source: Knight Frank
*Excl. Non-divisible portfolios
• The sale to Hines, for BVK, of the future Apple Store on the Champs-Élysées inflated the share of investment volume in the capital since the start
of 2018. Furthermore, Paris concentrates almost a third of the total number of deals recorded in France.
• Following an already slow start to the year, investment volumes in the regions were relatively low during the 2nd quarter and, with the
exception of part of the Promenade Saint-Catherine, were mainly for the sale of retail parks and brand portfolios.
34FRENCH RETAIL PROPERTY MARKET
INVESTMENT MARKET
High streets increase their domination
Breakdown of retail investment volumes by asset type
In France
Source: Knight Frank
100%
15%
90%
80% 37%
20%
70%
60%
50% 27%
40%
65%
30%
65%
20% 36% Share of high street retail in H1
2018 investment volume in
10% France
0%
2010 2011 2012 2013 2014 2015 2016 2017 1S 2018
High streets Retail warehousing Shopping centres
• Inflated by the sale of 114 Champs-Elysées, high street investment volumes accounted for 65% of retail investment volumes. Other
significant deals were mainly for Parisian assets. In the regions, the 1st half of 2018 saw the transfer of part of “Promenade Sainte-Catherine” in
Bordeaux by Redevco within the scope of the start of the Urban Retail Ventures fund formed with PGGM. Other large sales are expected, such as
that of “65 Croisette” in Cannes, for which a sale commitment has just been signed.
• Retail parks take second place due to some sales of individual assets of more than 20 million euros, but also due to the sale of brand portfolios.
The shopping centre market, on the other hand, remains subdued. 35FRENCH RETAIL PROPERTY MARKET
INVESTMENT MARKET
Examples of significant retail investment deals in H1 2018
Source: Knight Frank
Address Type City Seller Purchaser Price
Apple Store | 114 Champs-Élysées HS Paris 8 EPI Hines (BVK)
Grand Vitrolles SC Vitrolles Klépierre / CNP Carmila
Promenade Sainte-Catherine* HS Bordeaux Redevco PGGM
& Other Stories | 277 rue St-Honoré HS Paris 8 Private Private
Lutèce portfolio | 46 assets HS Paris Generali Groupe Madar Apple Store, Paris Champs-Élysées
Retail Park RW Saint-Priest - ImocomPartners
Ermenegildo Zegna | 50 rue du Fbg St-Honoré HS Paris 8 - BMO Rep
H&M, Desigual | 45-55 rue St-Jean HS Nancy Vastned UBS
Hypermarché Géant SC Pessac Groupe Casino Tristan Capital Partners
Jardiland portfolio RW France Covivio Inter Gestion
Les Grands Philambins RW Chasseneuil-du-Poitou - ImocomPartners
Léon de Bruxelles portfolio RW France AEW Ciloger Sofidy Retail Park, Saint-Priest
ZAC Benoît Hure HS Bagnolet Vinci immo Heracles
Portfolio | 8 assets HS France Family Office F&A Asset Management
Les Portes de Gayant RW Flers-en-Escrebieux Marne & Finance Midi 2i / Duval
ZAC de la Haie Passart RW Brie-Comte-Robert - Perial
Place des Fêtes HS Paris 19 Duval Private
26 rue de Rivoli / 19 rue du Roi de Sicile HS Paris 4 - Fiducial
JD Sports | 29 rue Saint Ferréol HS Marseille Vastned Voisin
45-55 rue Saint-Jean, Nancy
*Transfer of part of “Promenade Sainte-Catherine” in Bordeaux by Redevco within the scope of the start of the Urban Retail Ventures fund formed with PGGM.
< €20M €20-50M €50-100M > €100M Note: HS high street, RW retail warehousing, SC shopping centre
36FRENCH RETAIL PROPERTY MARKET
INVESTMENT MARKET
French investors declining Insurers / Mutual funds in the lead
Retail investment volumes by nationality Retail investment volumes by investor type
In France, as at 1st half 2018 In France, as at 1st half 2018
Source: Knight Frank Source: Knight Frank
4% 1%
3% 12%
4% Insurers / Mutual funds
France
SCPI / OPCI
12% 39%
Eurozone
Property investment
45% companies
Europe (outside Eurozone) Funds
North America Private investors / Family
12% Office
44%
Others Others
24%
• French investors only accounted for 45% of retail investment volume, a share that is clearly down compared to the 1st quarter (71 %) due to a
limited number of deals and the acquisition of 114 avenue des Champs-Elysées on behalf of the German BVK fund.
• This same deal explains the increase in volumes invested by insurers/mutual funds, which accounted for the largest share of activity (39%),
ahead of SCPI / OPCIs (24%) and property companies (12%).
37FRENCH RETAIL PROPERTY MARKET
INVESTMENT MARKET
New upward pressure
Prime retail yields
In France, as a %
Source: Knight Frank
10.00
9.00
8.00
7.00
6.00
5.00 5.00
4.25 High street
4.00
Regional shopping centres
3.00 Retail parks
2.75
2.00
2000
2001
2002
2003
2004
2005
2006
2007
2008
2009
2010
2011
2012
2013
2014
2015
2016
2017
2018
Q2
• With the exception of the best ground floor retail locations (2.75%), yields in the retail market saw new upward pressure, bearing witness to the
increased prudence of investors with regard to off-prime and secondary locations, and even prime locations that do not offer all guarantees with
regard to return.
38Antoine Grignon
Partner | Head of Retail Capital Markets & Leasing
+33 (0)1 43 16 88 70
+33 (0)6 73 86 11 02
antoine.grignon@fr.knightfrank.com
Antoine Salmon
Partner | Head of Retail Leasing
+33 (0)1 43 16 88 64 Contacts
+33 (0)6 09 17 81 76
antoine.salmon@fr.knightfrank.com
Vianney d’Ersu David Bourla
Partner | Retail Leasing Partner | Chief Economist & Head of Research
+33 (0)1 43 16 56 04 +33 (0)1 43 16 55 75
+33 (0)6 75 26 03 96 +33 (0)7 84 07 94 96
vianney.dersu@fr.knightfrank.com david.bourla@fr.knightfrank.com
39You can also read


