ENERGY NEWS Decarbonising Australia's Energy System - aie.org.au - Australian Institute ...
←
→
Page content transcription
If your browser does not render page correctly, please read the page content below
vol 38 | Quarter 1 2020

ENERGY
news
Decarbonising
Australia’s
Energy
System

official journal of the
australian institute of energy                aie.org.au
                                 Q1 2020 | ENERGYNEWS |1
contents
Energy
News                                       6                       14
International Standard Serial Number,
National Library of Australia:
                                           BloombergNEF            Hydrogen's
ISSN 1445-2227                             forecasts               potential
Print Post Approved No:
PP 100000796
REGISTERED OFFICE AND
POSTAL ADDRESS
Australian Institute of Energy
PO Box 576,
Crows Nest NSW 1585
Tel: +61 2 9431 8694 or
1800 629 945
aie@aie.org.au
www.aie.org.au
ABN 95 001 509 173                        20                       22
                                          Decarbonising            Siemens Energy
EDITORIAL                                 mining                   Transition Radar
ENERGYNEWS is published by the
Australian Institute of Energy (AIE)
and is provided to all members
as part of their membership
subscription. Non-members may
obtain copies of this journal by
contacting the AIE Secretariat or the
Editor: editor@aie.org.au
Articles from AIE members and non-
members on energy matters, letters
to the editor, personal notes and

                                           25                      28
photographs of those involved in the
energy sector are welcomed.
Publication of articles submitted is
at the sole and absolute discretion of
                                           Q&A with                Rooftop solar
the Australian Institute of Energy. The    Jessica Shaw MLA        potential
editor reserves the right to amend
and reduce the length of articles as
required and takes full responsibility
for any accidental errors.
Statements made in the journal do
not necessarily reflect the views of
the Institute. Unless otherwise stated,   Regular Features
all currency denominations are in
Australian dollars (AUD).
                                          1	presidents report   49 PODCASTS
ADVERTISING
Members and non-members                   42	AIE Branch NEWS    52 CALENDAR
may place paid advertisements
in ENERGYNEWS on behalf of
themselves or their organisations.
Advertisements can include products,
services, consulting, positions
vacant and required. Discounts are
available for members and for all
advertisements repeated in two or
more issues. Advertising rates are
listed at www.aie.org.au/energy-
news-journal

                                                                     Q1 2020 | ENERGYNEWS | 3
President’s Message

Promoting understanding and awareness of energy issues and the
development of responsible energy policies in Australia

aie President’s
Message
Welcome to the Australian Institute of Energy's first quarterly journal of 2020

A lot has happened since our last issue of            The AIE plays an important role in providing
ENERGYNEWS. The AIE has started the decade            an independent forum in which to build
with a fresh new look and has welcomed a new,         understanding and awareness of energy issues and
dynamic and gender-diverse team on the AIE            promote the development of responsible energy
National Board.                                       policies in Australia.
I would like to thank Leigh Morpeth for his service   We recognise that the recent Coronavirus
as President over the last two years, and his         (COVID-19) pandemic is a major concern for our
continuing support in the role of Vice President.     members and is causing disruption across the
I would also like to thank retiring directors Denis   nation. We will be taking appropriate measures
Cooke and Albert Thompson. We are grateful that       in response to advice from the Australian
both Denis and Albert continue to be involved in      Department of Health and the World Health
their local branches.                                 Organisation, including postponing some of our
The National Board met in February 2020, and          planned events.
I was delighted to welcome our new directors          We will also be looking at alternative forums
Glen Currie, Kylie Wilkie, Samantha Christie and      for discussion of critical energy issues and new
Nicholas Gurieff.                                     opportunities to deliver value to our members.
The board has a number of projects in the pipeline    In this issue of ENERGYNEWS we explore the
that we are excited to share with you over the        major issue of decarbonising Australia’s energy
coming months, including a new website and            sector. These include BloombergNEF’s outlook for
membership offering.                                  transitioning to low carbon technologies, BDO’s
                                                      view on opportunities for decarbonisation in
                                                      Australian mining, and the prospects for hydrogen
                                                      as a low carbon energy carrier.
                                                      We also interview Jessica Shaw MLA on the
                                                      findings of Western Australia's inquiry into
                                                      microgrids and the potential they offer for
                                                      improving electricity supply reliability in remote
                                                      regions while helping integrate distributed energy
                                                      resources such as rooftop solar, storage systems
                                                      and EVs. The findings of the inquiry are timely, as
                                                      across Australia bushfire-affected areas look to
                                                      build resilience and reduce cost.
                                                      Katharine McKenzie, AIE National President
                                                      president@aie.org.au
                                                      An energy policy specialist and commercial
The new AIE National Board photographed by
                                                      lawyer, Katharine has extensive experience across
fellow board member Charles Rendigs: (left to
                                                      the electricity and gas sectors. She is presently
right) Samantha Christie, Mena Gilchrist (Hon.
Secretary), Leigh Morpeth (Vice President),           Principal Policy Adviser to the Western Australian
Stephanie Moroz, Glen Currie (Hon. Treasurer),        Energy Minister, and sits on the WA Government’s
Katharine McKenzie, Jeremy Schultz, Kylie             Energy Transformation Taskforce and Renewable
Wilkie, Steve Blume and Nicholas Gurieff              Hydrogen Council.

  4 | ENERGYNEWS | Q1 2020
News

 IN BRIEF
                                     GREEN SCHEMES IN THE PILBARA
                                     Western Australia’s remote Pilbara is fast becoming the favoured
                                     location for projects looking to install large renewable arrays, some
                                     of which will be used to generate ‘green’ hydrogen. The region’s
                                     plentiful solar hours, wide open spaces and proximity to major
                                     resource projects are driving the interest. In February, ARENA
                                     announced it would part-fund a feasibility study by Yara Pilbara
                                     Fertilisers to explore making green hydrogen work at industrial scale.
                                     The Pilbara-based Asian Renewable Energy Hub and Murchison
                                     Renewable Hydrogen projects are also looking to generate hydrogen
Jeff Connolly, Siemens (left)
                                     from renewables for local and export use. And this month, Rio Tinto
and Terry Kallis, Hydrogen
                                     said it would invest $100-million in a solar and storage scheme to
Renewables Australia, shake          help power its Pilbara-based electricity network and Koodaideri iron
hands on the Murchison project       ore mine.

EV NUMBERS ON THE RISE WORLDWIDE
There are now over 7.9 million electric vehicles on the road
worldwide, according to a survey by the Germany-based Centre
for Solar Energy and Hydrogen Research Baden-Württemberg
(ZSW). Global numbers of EVs rose by 2.3 million in 2019
compared to the previous year. China remains the undisputed
world leader with over 3.8 million e-cars on the road, followed by
the US with nearly 1.5 million. In terms of registrations, more than
one in every two new passenger cars in Norway is electric. This
57% share is the largest worldwide. By comparison, EVs account
for 3% of new registrations in Germany, 5% in China and 2% in
the US. Tesla proved the most popular EV for buyers in 2019 with
361,000 of its EVs registered worldwide: zsw-bw.de/mediathek/          Tesla’s Model 3, currently the
datenservice                                                           best-selling EV worldwide

GE’S BATTERY BLACK-START                   AGN PLANNING GLADSTONE HYDROGEN PLANT
BREAKTHROUGH                               AGIG-owned Australian Gas Networks (AGN) is planning a
GE has successfully completed a            hydrogen plant in the Queensland port of Gladstone, home
first-of-its-kind backup support           to three LNG export terminals. The $4.2-million plant will be
system by deploying a battery              Australia’s first renewable hydrogen production facility able
energy storage to black start a            to deliver up to 10% blended hydrogen across the city’s total
heavy-duty gas turbine. A black            770 residential, small commercial and industrial customer
start consists of rebooting an idle        base. Construction is set to begin in November with the plant
power plant without support from           expected to be fully operational by December 2021. Earlier this
the grid in the event of a major           month, AGN was allocated $1.28 million in ARENA funding to
system disruption or a system-             establish the Australian Hydrogen Centre (AHC) that will study
wide blackout. To do this, operators       injecting renewable hydrogen into gas distribution networks in
typically use a dedicated diesel           South Australia and Victoria.
generator. GE’s 7.4 MW battery-
based energy storage system was
paired with the GE 7F.03, a 150
MW simple cycle gas turbine at
Entergy Louisiana’s Perryville Power                                                           Artist's
Station in the US to black start the                                                           impression
facility. The project demonstrates                                                             of AGN’s
the complementary nature of gas-                                                               Gladstone
powered energy and battery storage                                                             hydrogen
for system reliability.                                                                        facility

                                                                                 Q1 2020 | ENERGYNEWS | 5
Feature

  The first phase of the
    transition is about
             electricity,
   not primary energy
                                     By Seb Henbest, Chief Economist, BloombergNEF

 6 | Energy News | Q1 January 2020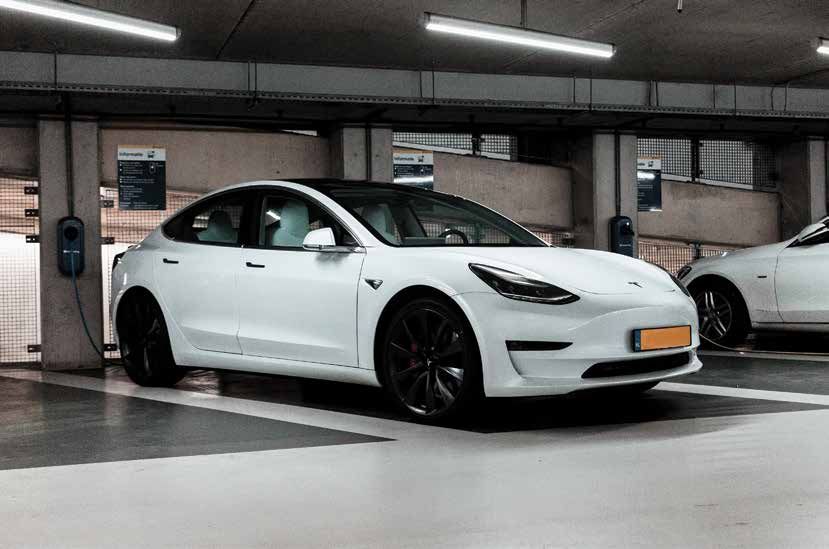
Feature

                                                      are highest at      and make up 21% of total
                                                      around 63%. It      installed capacity and 13% of
                                                      can also help       generation.
                                                      to explain why      In 2018 a record 108 GW of solar
                                                      many of the         PV was deployed worldwide, as
                                                      world’s most        well as 50 GW of wind power.
                                                      eminent energy      In 2019 the industry looked on
                                                      experts have        track to beat all records with
                                                      underestimated      121 GW of PV and 67 GW of
                                                      the growth          wind. This year, we estimate
                                                      to date of          another 138 GW of PV and 70
                                                      renewable           GW of wind. But how might this
                                                      energy, and its     continue?
                                                      future potential.
                                                                          The New Energy Outlook (NEO)
                                                       If we consider
                                                                          is BloombergNEF’s annual
                                                       that the
                                                                          long-term analysis of the future
                                                       electricity
                                                                          of energy. It draws together
                                                       sector
                                                                          the work of over 65 in-house
                                                       consumes
                                                                          analysts across the world to
                                                       about 38%
                                                                          describe a future, least-cost,
                                                       of fossil
                                                                          electricity system.
                                    fuel production – and that
Often we hear that wind and                                               The headline conclusion is
                                    renewables make up 25%
solar might be great and                                                  that a combination of cheap
                                    of electricity, and wind and
growing fast, but despite years                                           renewables, batteries, and other
                                    solar PV make up 25% of that
of deployment and government                                              new sources of flexibility grow
                                    – it is easy to see how these
support they are still just 1%                                            worldwide to reach almost 50%
                                    technologies can get lost in the
of primary energy and so can’t                                            wind and PV in the electricity
                                    noise of a much larger primary
possibly replace fossil fuels in                                          supply by 2050, with solar
                                    energy analysis.
the world energy economy.                                                 growing from around 2% to 22%
                                    Renewables are certainly not
Primary energy might be the                                               of electricity, and wind from 5%
                                    the one-size-fits-all solution that
right lens through which to                                               to 26%.
                                    enthusiasts sometimes claim.
think about energy when there                                             In contrast, the share of fossil
                                    However, if we think of the
are few alternatives to fossil                                            fuels in power declines to
                                    energy transition in phases, then
fuels, or if you’re an oil, gas,                                          31% from 63% today while
                                    we need to think of wind, PV
or coal company, for which                                                hydro and nuclear see modest
                                    and lithium-ion battery storage
primary energy describes the                                              growth or remain flat, the
                                    as ‘Phase I’ decarbonization
product you sell. However, the                                            former constrained by resource
                                    technologies that, if deployed
world economy does not run on                                             availability, the latter by a
                                    to their full potential, can make
primary energy, it runs on final                                          combination of high costs and a
                                    a big dent in greenhouse gas
energy. That’s the energy we                                              lack of flexibility.
                                    emissions and buy us time to
consume to heat and light our
                                    develop something else for            At its core, NEO is a story of
buildings, run our vehicles, and
                                    ‘Phase II’.                           technology disruption and
power industry.
                                    The world has been adding             nothing reflects this better
The major difference between                                              than solar PV. Since 1976 we
                                    more renewable power capacity
primary and final energy is waste
                                    than fossil fuel power capacity       have seen a rapid fall in the
heat, though there are also some
                                    since 2015. Today, renewables         price of crystalline silicon PV
losses from energy transport.       (excluding large hydro) account       modules, down from US$80/W
Altogether, around a third of       for almost 68% of new additions,      to US$0.27/W in 2018, and
primary energy is lost before it
can do anything useful.             “In Australia, one in five households already has rooftop
Thinking about the world in         PV. In the state of South Australia, it is one in four with
terms of primary energy also
masks the important role of
                                    rooftop PV accounting for more than half the system load
electricity where heat losses       at certain times”

                                                                                 Q1 2020 | ENERGYNEWS | 7
Feature

around US$0.25/W in 2019.           where wind parks can be             its equity hurdle rate of return.
Just since 2010 PV module           developed economically. Overall,    When we do this, we find that
prices have fallen 85%. Driving     onshore wind energy has a 15%       the cost of renewable projects
this are manufacturing scale        learning rate.                      have now fallen to such an
and ongoing deployment. The         In recent years, the cost of        extent, that today two-thirds
relationship between price and      offshore wind has come down         of the world population live
volume can be represented by        faster than most expected.          somewhere where wind or PV, or
an experience curve.                This is due to the combination      both, are the cheapest new-build
For PV, the experience curve        of larger turbines offering         electricity option. And in Japan,
describes a 28.5% decline in cost   better park layouts and fewer       Poland or Turkey where coal
for every doubling of capacity.     foundations, and less cabling       remains cheaper, or in Russia
That’s perhaps not as steep as      and maintenance. Larger             where gas remains cheaper,
equivalent curves seen in the       projects are also pushing the 1     this first tipping point in the
semi-conductor industry, but it’s   GW mark offering economics          economics is imminent.
of a similar order of magnitude.    of scale. Finally, growing global   We are also seeing firm
How long this relationship will     supply chains and developer         downward pressure on new
hold is unknown, but bottom-up      experience and improved             wind and PV project costs from
analysis looking at innovation      policy design are boosting the      more and more capacity being
in PV manufacturing on a            economics.                          awarded via tender or auction.
component-by-component              Both solar PV and wind are the      Here, competition between
basis makes us confident that       product of large-scale modular      developers continues to reveal
the industry won’t hit technical    manufacturing industries            incredibly low prices, which in
limitations anytime soon.           that find continuous micro-         turn has squeezed margins all
                                                                        along the supply chain.
Looking out to 2025 and             innovations in production
2030, we expect all-in cost         efficiency, materials and           Most recently, on 21 November
of energy from new solar PV         energy use. The cost of these       2019, the Dubai Energy and
to drop another 14% and 22%         technologies declines with          Water Authority awarded a
respectively.                       every unit deployed. And this       contract for 800 MW of PV to
                                                                        Saudi-based ACWA Power and
“If we expect renewable technology costs to continue to                 Kuwait-based Gulf Investment
                                                                        Corporation with an impressively
decline along their experience curves, then it’s a matter of
                                                                        low bid of US$16.95/MWh.
when, not if, new-build wind or PV drops below the cost of              This followed the lowest bid on
running existing, commissioned coal and gas plants”                     record of US$16.30 (¤14.80/
                                                                        MWh) from French developer
Wind technology has also been       is fundamentally different from     Akuo Energy which won 150 MW
getting cheaper. The price of       large, fuel-based power plants      in Portugal’s first solar auction in
wind turbines is down 40%           which are pieces of complex         August.
since 2010 on a per megawatt        system engineering, and where       Already this year we have
basis with an experience curve      50% of the lifetime cost of         seen 63 GW of new renewable
of around 11%. But while unit       a coal plant and 70% of that        capacity awarded via auction –
declines are less impressive than   for gas plants are due to fuel      more than ever before – with a
PV, wind remains competitive        prices, themselves subject to       further 97 GW announced for
with solar energy because each      commodity cycles.                   future rounds. The lowest bid
MW of wind yields more energy.      By taking technology costs,         for new onshore wind energy to
This improvement in capacity        balance of plant, operations,       date is in Mexico where Italian
factor comes from taller turbines   maintenance and financing costs     utility Enel won a total of 593
that can access faster wind         into account, we can calculate      MW, including a bid of US$17.70/
speeds, and bigger swept-area-      the levelized cost of electricity   MWh.
to-power-output ratios that         (LCOE) for new renewable and        These prices need to be read
increase the energy captured        fossil fuel assets alike.           cautiously as they hide a long list
where the wind is weaker.           The LCOE is the average offtake     of contract particularities that
Newer turbine models are also       price needed across a project       obscure the full lifetime cost of
widening the range of locations     lifetime for a developer to meet    the projects. For example, some

  8 | ENERGYNEWS | Q1 2020
Feature

bids are for delivery in future       In China, our calculations            time-of-use load shifting, large
years and developers can bake-        suggest new onshore wind will         reservoir hydro and pumped
in an expectation of cheaper          be cheaper than running existing      hydro, network interconnection,
equipment; projects also usually      coal-fired power as early as          and gas peaker plants that run
have a longer life than the length    2024. And in the US, which has        on-call for a small number of
of contracts awarded; and some        the cheapest gas in the world,        hours per year, can all offer
include inflation factors or          new-build wind and PV look            flexibility.
differential tariffs. However, even   likely to be cheaper than running     However, the most compelling
if we levelize these bids, they       most existing combined-cycle          technology story is lithium-ion
remain incredibly cheap and the       gas plants by 2030.                   batteries. Batteries can shave
costs are generally much lower        As these critical points are          peaks and can help PV meet
than those of new coal or gas         reached, renewables can start         demand when the sun has gone
plants.                               to take market share from             down, and wind meet demand
                                      commissioned coal and gas             when it’s not blowing. However,
If we expect renewable
                                                                            most importantly, like PV and
technology costs to continue to       plants, which consequently
                                                                            wind, lithium-ion batteries are
decline along their experience        see lower capacity factors and
                                                                            getting cheaper, fast.
curves, then it’s a matter of         higher generation costs.
                                                                            The price of a lithium-ion battery
when, not if, new-build wind          But there is an obvious problem
                                                                            pack is down 87% since 2010 on
or PV drops below the cost of         – wind and PV are not always
                                                                            a volume-weighted basis from
running existing, commissioned        available – so looking at the
                                                                            US$1,160/kWh to US$156/kWh,
coal and gas plants.                  LCOE alone is not enough.
                                                                            according to BloombergNEF’s
This second ‘tipping point’           Ultimately what’s needed is
                                                                            December 2019 annual survey.
happens at different times in         additional flexibility, both on the   At the same time, battery energy
different countries, depending        supply and the demand side to         density and cycle life continue
on the quality of renewable           help support variable renewables      to improve – the former up more
resources and fuel prices, but        and ensure security of supply.        than 67% since 2011. Like PV and
it happens sooner than most           Demand response, including            wind, this decline in costs is the
people might think.                   both capacity turn-down and           result of manufacturing scale

                                                                                   Q1 2020 | ENERGYNEWS | 9
Feature

and innovation, with battery          depending on what’s available.        ELECTRIC VEHICLES
pack demand rising 100-fold           They are also being used in           The fall in battery prices is the
from 2010 to 2018.                    some markets by large energy          result of growing demand from
The relationship between price        users to lower demand charges,        the EV industry. EV sales growth
and volume here describes             and grid operators to avoid           slowed a little in 2019, but we
an 18% learning rate, so as           costly network upgrades.              still expect a record 2.2 million
manufactured volume increases         However, in the future we             vehicles, up from 1.9 million in
over time, we expect costs            expect most batteries will find       2018, and just over 1 million in
will continue to fall to around       value in load shifting – that is,     2017. At the end of Q3 2019
US$94/kWh in 2024 and                 charging when renewables are          there were 6.5 million EVs on the
US$62/kWh in 2030. Right              abundant and prices low, and          road, over half of those in China.
now there is 366 GWh per              discharging during high value         The uptake is being driven
year of commissioned lithium-         hours when renewables are             in part by tighter tailpipe
ion battery manufacturing             offline and prices spike as more      emissions standards in US,
capacity worldwide. Based on          expensive generation ramps up.        China and Europe that require
manufacturer commitments, by          We can already see a pipeline         auto manufacturers to sell more
2022 that number is set to rise       of co-located renewables-plus-        EVs to balance sales of their
more than three-fold to 1,239         storage projects. If the battery      internal combustion engine (ICE)
GWh.                                  is small enough, these can be         models.
                                                                            There are currently 370 battery-
“The most compelling technology story is lithium-ion
                                                                            electric and plug-in hybrid
batteries. Batteries can shave peaks and can help PV meet                   EV models on the market
demand when the sun has gone down, and wind meet                            worldwide, and by this time next
demand when it’s not blowing. Most importantly, lithium-                    year there will be 428.
ion batteries are getting cheaper, fast”                                    More models means more
                                                                            choice, and more likely a buyer
                                                                            will find an EV option that suits
To give a sense of future scale-      competitive today, while lower        their needs. On the other side of
up, in 2018 demand for lithium-       cost, larger batteries are starting   the ledger, purchase subsidies,
ion batteries for electric vehicles   to look in the money.                 tax breaks and scrappage
overtook demand for lithium-                                                schemes are helping drive
                                      Our calculations suggest the
ion batteries for consumer                                                  consumer uptake. Governments
                                      cost of co-located wind-plus-
electronics, and in most markets                                            are also starting to send longer-
                                      storage and PV-plus-storage
EVs currently only make up 2%                                               term signals to the market.
                                      projects with larger four-hour
or less of the on-road fleet.                                               So far, 13 national governments,
                                      storage systems will fall over
While lithium-ion battery                                                   as well as 30 states and
                                      40% by 2030.
chemistries aren’t always                                                   municipal governments, have
a perfect fit for stationary          That means renewable energy           announced phase-out plans for
energy storage applications in        can reach more high-value hours       ICE vehicles. Norway is the most
the power sector, they have a         when they would otherwise be          ambitious country-level target,
significant cost advantage over       unavailable, competing directly       aiming to ban ICEs by 2025.
other technologies. Today, a          with new coal or gas projects for     Other European countries
four-hour lithium-ion battery         capacity by the mid-2020s.            such as Denmark, Sweden and
system charging from the grid                                               Netherlands are aiming for
                                      In India, for example, we think
has an average levelized cost                                               2030, and the UK, France and
                                      these co-located systems will
of around US$167/MWh, and as                                                Canada for 2040. Cities tend to
                                      look more economic than new
battery costs decline we expect                                             be more ambitious, with Madrid,
                                      pithead coal-fired generation by
this to fall to US$79/MWh by                                                Rome, Athens and Mexico City
                                      2024.
2030.                                                                       aiming to be ICE-free in six
Today, most business cases            And by the mid-2030s batteries        years. Los Angeles, Cape Town
for large-scale batteries rely        charging either from the grid         and Brussels are some of those
on stacking revenues from a           or from a co-located coal asset       aiming for 2030.
combination of energy, capacity       could be cheaper then running         Around 30% of the cost of a
and ancillary service markets,        existing coal or gas plants.          battery EV is the battery pack,

  10 | ENERGYNEWS | Q1 2020
Feature
so cheaper batteries means ultimately be as important as million barrels of oil per day by
cheaper EVs which, according how much load they add. 2040.
to our analysis, should reach Many energy suppliers in the Consumers are not just starting
upfront price parity with US and Europe already offer to buy EVs, they are also
equivalent ICE models as soon EV-specific rate structures that changing the energy system by
as 2023. From that point we provide a strong incentive for installing their own PVs, and in
expect uptake to accelerate, off-peak charging at night. some places they are also now
reaching 30% of new vehicle adding batteries. Small-scale
If an EV can be plugged in
sales worldwide by 2030, and PV deployed on rooftops and
during the 95% of the time a
57% by 2040, up from just 3% commercial buildings has grown
today. normal car is stationary, whether
strongly in markets with good
that’s at home, at work, or out-
By 2040, around 42% of cars on solar resources and high, or
and-about, then owners can
the road in the US are expected rising, retail electricity prices.
charge at the cheapest times,
to have a plug. In Europe it is In Australia, one in five
and the power grid benefits from
38%. Worldwide there are set to households already has rooftop
greater demand-side flexibility.
be around 576 million EVs on the PV. In the state of South
road in 2040. All these EVs do With the growth of close-to-zero Australia where I’m from, it’s one
two things: they add electricity marginal cost PV and wind, we in four and rooftop PV accounts
demand, and they reduce oil expect these tariffs to shift more for more than half the system
demand. vehicle charging to the middle of load at certain times.
the day when solar generation is
Growth in electric vehicles As solar gets cheaper more
accounts for 3,950 TWh, or 9%, at its best.
households and commercial
of electricity demand in 2050. Growth in EVs, and fuel economy facilities will add PV to offset
Again, this differs by region. improvements, mean we think their retail electricity bills.
In the US, EVs draw 16% of oil demand from road fuels And as the cost of lithium-
electricity in 2050, in Europe should peak around 2030, with ion batteries continues to fall,
15%, in Australia 13%, and in the combination of alternative adding storage alongside PV
China 10%. However, the hours drivetrains and growth in shared also starts to look more and
of the day when EVs charge will mobility displacing around 15 more attractive.
Q1 2020 | ENERGYNEWS | 11Feature
Consumer uptake can be by large amounts of PV during For example, the US energy
rapid when price and market the day, supported by wind in transition is dominated by
penetration meet critical the evenings and batteries that cheap natural gas which
thresholds and a copycat effect charge and discharge over short grows to 45% of generation in
drives steep adoption S-curves timeframes. In this new system, 2030 as it replaces aging coal
where uptake accelerates back-up and curtailment are a infrastructure. Once new gas
from early adopters to the feature, not a bug. plants are commissioned, they
mass market, before reaching are cheap to run and tend not
Firstly, there are limits to what
saturation. to face strong competition
wind, PV and batteries can do
from battery systems for their
Our diffusion modelling for together. This is because there
dispatchable hours this side of
consumer PV, and PV-plus- are days and weeks during the
2050.
battery products, shows that year when wind and PV simply
Wind and PV grow too but more
by 2050, 10-30% of power can’t produce enough electrons
slowly, making up just 35% of
capacity assets could sit behind- to meet demand, no matter how
electricity by mid-century. In
the-meter in major markets, many batteries are installed.
China, coal generation grows
with electricity demand in the
“No longer do large coal or gas plants run around-the-clock short to medium term, but we
at high capacity factors, supported by smaller peakers. think China will build its last coal
plant by 2025 and sees peak
Instead, cheap variable renewables form the backbone of
coal generation in 2027. After
the system, supported by batteries and conventional plants this, coal declines at around 2%
running at low capacity factors” per year, and by 2050, wind and
PV makes up 48% of China’s
electricity supply.
highlighting a massive shift in Some of the peakiest parts of
Coal-fired power is the first
system value downstream. the load might be met with
fossil fuel casualty of the energy
Looking at the NEO results at demand response, but that’s
transition, according to our
a regional and country level limited. That means these
modelling – peaking globally in
to 2050 shows that Europe systems need to call upon
2026 and falling to just 12% of
transitions furthest towards dispatchable back-up.
electricity in 2050, from around
renewables, and does so fastest. Secondly, there are weeks and 37% today.
The combination of low cost months when renewables are
bulk renewables, carbon pricing, This transition is most stark
running flat out producing more
and competitive batteries, in Europe and the US, where
electricity than is needed in real
propel wind and PV to over 80% coal-fired power continues
time and more than the battery
penetration by 2050 in some its recent decline, down 90%
fleet can store.
European states. Those where to 2050 in the US where it’s
At these times we have undercut by cheap natural gas
nuclear, hydro or biomass can
too much capacity and get and renewables, and down 97%
play a major role get close to
curtailment. But this is still in Europe where coal phase-
100% zero-carbon. An 80%
variable renewable energy least-cost, because as PV out plans, cheaper renewables
system looks very different from and wind get cheaper, they and batteries, as well as carbon
the power systems with which remain competitive despite not pricing, force it out of the mix.
we are familiar. producing useable electricity Coal continues to grow in China
during every hour of operation, and South East Asia into the
No longer do large coal or gas
that is, at lower and lower mid-2020s, and India until the
plants run around-the-clock at
capacity factors. late 2030s.
high capacity factors, supported
by smaller peakers. Instead, Ultimately, we think almost every The outlook for gas-fired power
cheap variable renewables form country could technically get to remains relatively flat, as growth
the backbone of the system, around 80% wind and PV before in the US is offset by longer-
supported by batteries and reaching seasonal limitations, term decline in Europe where it
conventional plants running but most would need to deploy is increasingly beaten on cost by
at low capacity factors. This new renewables much faster to the combination of renewables
configuration is characterized do so this side of 2050. plus batteries.
12 | ENERGYNEWS | Q1 2020Feature
In Asia, gas is beaten by cheap loads long distances is going The good news is that ‘Phase
coal and renewables. Gas grows to need something with better I’ can buy us time. But only if
0.6% per year, supplying system energy density than a battery. PV, wind, batteries and EVs are
back-up and flexibility rather Heating is also highly seasonal deployed as fast, or faster, than
than bulk generation in most which means a lot of energy the NEO suggests. At the same
markets. However, gas capacity demand is concentrated in a few time, government needs to start
doubles to help ensure security months of the year. It also has making a market for the ‘Phase
of supply, with combined-cycle a particular intraday pattern, II’ decarbonization technologies.
plant up 37%, and peaker units ramping up in the morning as And let the private sector start
that can ramp quickly to meet people wake up and turn on investing.
daily and seasonal extremes up their heating, and again in the Further information on
350%. evening when they arrive home. BloombergNEF’s New
From a climate perspective, the If a country like the United Energy Outlook is available
NEO is somewhat optimistic. Kingdom were to shift to 100% at: about.bnef.com/new-
It concludes that a least-cost electric heat, the coldest days energy-outlook/
deployment of renewable might drive a three-fold increase
energy would keep power in winter peak power demand,
sector emissions on track for right at the time when solar
a 2-degree trajectory, but only generation is at a nadir.
until around 2030. Beyond In industry, high temperature
that, decarbonization would heat is required for iron and
need to be hastened by policy steel production, chemicals,
intervention. To achieve a 1.5 cement, aluminum and glass,
degree trajectory as envisaged among others. While electricity
by the Paris Agreement will need can technically provide high
much more rapid transition than temperature heat, most
economics alone can deliver. technology options are still at
Achieving net-zero emissions by early stages of development.
the second half of the century Furthermore, in chemicals
means there is nowhere to hide manufacturing, for example,
for those slow on the uptake, fossil fuels also provide the raw
and no room for unabated materials, and in iron and steel
fossil fuels. In particular, net- production, they are chemically
zero emissions targets ask involved in the process itself.
serious questions about energy Even in the power sector,
transition pathways for industry we’ve seen that around 20%
and buildings. of electricity demand is going
One pathway is to switch to to be very difficult to supply
electricity to hitch a ride on the with wind, PV and batteries –
back of the renewable energy our ‘Phase I’ decarbonization
juggernaut. As discussed, this technologies – alone. To get to
is already well established for net zero we are going to need a
road transport, even some of the ‘Phase II’.
commercial vehicle segments. Perhaps the answer is nuclear,
It is also possible to use more hydro or solar thermal?
electricity for space heating in Perhaps it’s carbon capture
buildings, as well as low- and with permanent sequestration?
medium-temperature industrial Or perhaps we are going to
processes. need a clean molecule such
However, going electric isn’t a as hydrogen? What we know This article first appeared in
universal solution. Yes, there is for sure is that right now, all the January 2020 edition of
interesting progress being made the options we can list have Papeles de Energia entitled
in short-haul electric aviation limited potential or are far from ‘Perspective on the Energy
and shipping, but moving heavy commercially viable. Transition’.
Q1 2020 | ENERGYNEWS | 13The emerging Feature hydrogen market of Australia: a 2020 update By Luigi Bonadio 14 | ENERGYNEWS | Q1 2020
Feature

Hydrogen is gathering significant momentum
globally as it shifts to becoming an economically-
viable and flexible fuel, energy carrier and
enabler for the rapid and widespread deployment
and international trade of renewable energy.
The evaluation of commercial business
opportunities for hydrogen will rely on
the critical evolution and interrogation of
technological, economic, social, environmental
and political drivers and barriers. This article
provides a broad overview of these drivers and
barriers and covers recent developments across
the emerging hydrogen industry.

TECHNOLOGY
Other than in a few isolated cases, most of
the necessary technology underpinning the
development of a hydrogen industry exists and has
been operated safely with acceptable performance
on at least the pilot scale.
The distributed use of hydrogen as a fuel
and energy carrier to service mobility and                The market appetite for hydrogen has grown
power generation markets leverages off its                appreciably with automotive companies, power,
extensive utilisation across a number of process          gas and water utilities, manufacturers of fertilisers,
and manufacturing industries (chemicals,                  urea and explosives, mine operators and local
petrochemicals, hydrogenation of oils, glass,             councils now investing in hydrogen plant and
pharmaceuticals, microchip cleaning, space                hydrogen fuel cell electric vehicle trials across
industry, turbine cooling).                               Australia.
It also benefits from the various production              Many other large and small companies are
options available including the gasification of coal,     seriously evaluating the scale and timing of their
steam reformation of methane, partial oxidation of        future investments in hydrogen with a meticulous
hydrocarbons, electrolysis of water and biological
                                                          watching brief on the critical hydrogen production
production. The Hazer Group based in Western
                                                          costs and break even points.
Australia has developed a novel process using
natural gas and unprocessed iron ore to create a          The mobility sector is the early mover in the
low cost and low emission ‘clean’ hydrogen.               global hydrogen industry led by Toyota, Hyundai
                                                          and Honda in the light duty vehicle sector and
Hydrogen’s versatility lends itself to orderly
                                                          by Nikola, Toyota and Hyundai in the heavy duty
transitions from a high energy dependence on
                                                          vehicle sector.
fossil fuels to renewables and biofuels and from
highly centralised to distributed energy systems.         There are 432 hydrogen refuelling stations
                                                          currently in operation worldwide, with 226 planned
Hydrogen is safely transported over short and long
                                                          for commissioning and over 19,500 light duty fuel
distances in pipelines via dedicated compressor
                                                          cell electric vehicles (FCEVs) on the world’s streets
units or via compressed or liquid hydrogen tube
                                                          at the end of 2019 (US: 42%, South Korea: 26%,
trailers. It can be safely stored in gaseous, liquid or
                                                          Japan: 19%, Europe: 13% and China: 1%). Placed
solid forms for mobile and stationary applications
over short and long periods of time in any location       orders dominated by Asian buyers are set to
and on any scale, ranging from micro canisters for        increase this to over 50,000 by the end of 2020.
hand-held mobile devices to large storage vessels         Market opportunities exist for both battery electric
for bulk transport and intercontinental export.           vehicles (BEVs) and FCEVs for short, regular, urban
Hydrogen unit operations are integrated with              travel. However, owing to high volumetric density
the use of dedicated hydrogen lines, valves and           and fast refuelling, hydrogen FCEVs are deemed
vents with hydrogen flows tightly controlled              more suitable for long distance travel of heavy
and accurately measured. Hydrogen leaks can               duty vehicles such as trucks and coaches.
be identified by sensors and ultrasonic gas leak          Moreland City Council in Melbourne is trialling two
detectors.                                                Toyota Mirai FCEVs. Australia’s third hydrogen

                                                                                    Q1 2020 | ENERGYNEWS | 15
Feature
refuelling station will be built at the old Bulwer stages of development for the provision of space
Island Refinery in Brisbane to fuel QFleet’s FCEVs. heating in commercial buildings and as a source of
Other proposed hydrogen mobility projects are industrial process steam and heat.
planned for the City of Ballarat and Canberra. Yara Fertilisers, Incitec Pivot and H2 Utility are
There is also a growing level of development and trialling renewable hydrogen plants for ammonia
trialling of hydrogen fuelled trains, trams, boats, production in Western Australia, Queensland and
ships and fuel cell electric planes. South Australia, respectively. BOC, Origin Energy,
In the power generation sector, turbines in the Woodside Energy, H2 Utility, Renewable Hydrogen
order of 440 MW nominal capacity running Australia and Siemens are planning for the bulk
on a mixture of natural gas and hydrogen and export of hydrogen or ammonia. Queensland’s
dedicated hydrogen fuelled turbines utilising Minister for State Development, Cameron Dick
Wet Low Emissions Technology are being trialled announced at the Central Queensland Hydrogen
by Mitsubishi Hitachi Power Systems, GE Power, Forum on 26 February 2020 that H2 Utility had
Siemens Energy and Ansaldo Energia for large purchased a 171 hectare site in the Gladstone State
scale, low emissions power generation. Development Area to build and operate a 3 GW
Proton-exchange membrane (PEM) fuel cells PEM electrolyser for the production and export of
remain a relatively expensive cost component in green hydrogen and ammonia.
hydrogen systems at $1,000/kW, but have reached
energy efficiency and performance targets for ECONOMICS
market acceptance, particularly for mobility The net present value and internal rate of return
applications. of renewable hydrogen projects and, to a large
Jemena, Atco Gas and Australian Gas Networks extent, the growth of a renewable hydrogen
(HyPark South Australia and HyPark Gladstone) market are largely dictated by electricity costs.
are all investing in trials of hydrogen for natural Utility-scale wind and solar PV farms in specific
gas substitution in pipelines, some with the locations across Australia are providing abundant,
financial support of government funding. affordable and reliable energy at a low-end
The Australian Hydrogen Centre plans to inject levelised cost of energy (LCOE) of $34/MWh and
up to 10% renewable hydrogen into the gas $45/MWh, respectively. This represents a LCOE
distribution networks of selected towns in the less than coal plants that at best are producing
states of South Australia and Victoria by end- power at a LCOE of $60/MWh.
2022. Hydrogen-fired boilers are also in the early Even though the rate of LCOE reductions from
Figure 1: Fuel cell market sales by region, MW (2015-2019)
800
700
600
500
400
300
200
100
0
2015 2016 2017 2018 2019
Europe North America Asia RoW
Source: The Fuel Cell Industry Review 2019, E4 Tech, 2020
16 | ENERGYNEWS | Q1 2020Feature
solar PV and wind have eased over recent years, PEM electrolyser capital costs are forecast to
renewable hydrogen cost is estimated to drop into drop into the range of $400 to $600/kW within
the range of $2.0 to $3.2/kg H2 in many locations five years, adding to the viability of large scale
across Australia by 2030 and below or close to the hydrogen export projects, the replacement of
break-even point for various applications (trucks: diesel generators for remote area power systems
$3.6/kg, cars: $2.9/kg, ammonia production: $2.5/ and microgrids and the supplementation of power
kg and refinery hydrogen separation: $2.5/kg). across transmission networks for grid firming.
The largest known electrolyser located in Namie, An operator of hydrogen refuelling stations in
Japan just north of former Fukushima Daichi California is aiming to sell hydrogen over the next
nuclear plant, has just started operating at a 3-5 years at US$10/kg (US$0.98 per litre of petrol).
nominal capacity of 10 MW. It can produce enough Although FCEVs are relatively expensive lying in
hydrogen to full 560 hydrogen FCEVs. Toyota’s the US$40,000 to US$60,000 range, they are
new model Mirai FCEV is reported to travel starting to offer total cost of ownership parity
30% further than the standard model per kg of with BEVs for applications that require long range
hydrogen consumed. and heavy payload. As such, they are projected to
Construction of Air Liquide Canada’s 20 MW be less expensive to run than BEVs and internal
(3,000 tonnes per annum) electrolyser system combustion engine (ICE) vehicles within 10 years.
in Becancour, Quebec is underway and due for Hydrogen mobility applications are currently
completion by year’s end. There are two 20 limited by the prohibitive high cost of hydrogen
MW (4,000 normal cubic meter per hour) PEM refuelling stations compared to petrol and diesel
electrolyser plants planned for construction in refuelling equivalents.
Europe that are estimated to produce hydrogen at
The Asia Pacific hydrogen market is accelerating
a cost of US$6.0/kg ($9.18/kg). This is predicted to
faster than any other (Figure 1) and is estimated to
drop by 60% to US$2.6/kg by 2030.
reach a value of ¤30 billion ($52 billion) by 2030.
The Commonwealth Minister of Energy the Hon. Investors are pinning their hopes for long term
Angus Taylor has recently appointed Australia’s financial returns on the continued performance
Chief Scientist Dr Alan Finkel to lead a committee and cost improvements stemming from:
that will work on reducing electrolytic hydrogen
• the development of new, highly specific and
production costs in Australia to less than $2.0/kg
readily available composite and other materials
H2. Dr Finkel is confident that hydrogen can be
for catalyst coatings, membranes and storage
produced in Australia for as low as $1.20 by 2050.
vessels;
Dr Finkel has noted that these are critical
• the system optimisation of integrated hydrogen
projections as “if hydrogen production can achieve
systems; and
the same level of commercial competitiveness
as that achieved by solar and wind generation in • cost reductions from increased manufacturing
the electricity sector, it could create a substantial and installed plant capacity and deployment.
economic opportunity for Australia, generate The Cooperative Research Centre for Future
about 7,600 jobs and add about $11 billion a year in Fuels, CSIRO and many universities and research
additional GDP by 2050. If global markets develop organisations across the globe are working
faster, it could mean another 10,000 jobs and at on novel materials, system efficiency and cost
least $26 billion a year in GDP”. reductions for advanced hydrogen technologies
Table 1: Emissions intensity of different hydrogen production routes in Australia
Production route Emissions (kg CO2e/kg H2)
Electrolysis – renewables 0
Electrolysis – grid 40.5
Coal gasification - with CCS (best case) 12.7 - 16.8
Coal gasification – without CCS 0.71
Steam methane reforming - with CCS 8.5
Steam methane reforming - without CCS 0.76
Q1 2020 | ENERGYNEWS | 17Feature
and optimum pipeline, electrolyser, fuel cell, operates a hydrogen refuelling station to fuel a
storage and integrated hydrogen system designs. Toyota Mirai FCEV, demonstrating and raising
awareness and community acceptance of the
ENVIRONMENTAL technology.
Generally speaking, there appears to be greater Certified hydrogen technology training programs
market acceptance and a positive reception to the from genuine experts and skills development at
economic and environmental benefits of hydrogen. all levels of professional, trades and academic
It is clear that renewable hydrogen will provide the
education should be implemented as soon as
best environmental outcome, even when the land
possible.
impacts of solar farms and challenges with the
recycling of spent solar cells and wind blades are POLITICAL
included (Table 1). AIE members will recognise the critical importance
Many argue that investment in and adoption of of monitoring technological and regulatory
renewable hydrogen should be accelerated ahead developments abroad and the implications of an
of the cost curve, due to the broad economic increased reliance on imported crude oil, refined
impacts of climate change as the global average petroleum products, industrial chemicals and
carbon dioxide equivalent (CO2e) concentration automotive vehicles and components.
soars above 410 parts per million. Although many China, Japan, the Republic of Korea, the US, the
Australian and global businesses are committing UK, France, Germany, the Netherlands, Norway and
significant resources to the decarbonisation of other European countries are leading the global
their operations, over 40% of ASX 200-listed charge in hydrogen with billion-dollar investments
companies have yet to set emission reduction in commercial-scale mobility and renewable
targets. energy projects.
Although renewable electricity generation in Many European countries, India, Mexico and
Australia is increasing at over 10% per year California have set dates when the sale of petrol
and contributes to over 20% of all electricity and diesel-fuelled ICEs will be prohibited while
generation, its contribution to primary energy others have set clear targets on raising numbers of
production lies below 1%. It remains an imperative FCEVs and publically-funded hydrogen refuelling
to pursue all low carbon technologies as soon as stations. The UK government is currently seeking
possible inclusive of hydrogen and carbon capture views on bringing forward the date when sales
and storage (CCS) – and possibly nuclear – if we of new petrol, diesel and hybrid cars and vans
are to come to terms with the gravity of climate will cease from 2040 to 2035, or earlier if a faster
change impacts and the profound challenge ahead transition appears feasible.
to ameliorate them.
As an importer of automotive vehicles, Australia
SOCIAL will inevitably have to develop a hydrogen supply
Recent studies and surveys by the University of network to support FCEVs or hydrogen fuelled-
Queensland have identified gaps in the knowledge ICEs. Low domestic reserves of diesel fuel, the
and understanding of hydrogen technology and cessation of Holden’s domestic operations and
what can and cannot be reasonably achieved over Australia’s high dependence and vulnerability
short and long terms. Conservative perhaps cynical to Chinese demand for LNG give rise to national
energy practitioners continue to harbour deep concern, particularly if we are slow to adapt and
felt reservations citing concerns with fundamental respond to international developments.
thermodynamic limitations, low efficiencies and In any case, the emergence of a hydrogen
relatively high costs associated with hydrogen industry can play a critical role in boosting trade
production, compression, storage and conversion. and stabilising the energy security of Australia
These concerns mirror the same doubt over the and its neighbours, a key driver that has largely
future viability and cost of solar PV systems many been overlooked in recent hydrogen fora and
years ago. discussions.
Community awareness and acceptance of Many countries – some our not too distant
hydrogen as a safe and reliable fuel is mandatory, neighbours – will not be able to generate enough
particularly as hydrogen will be utilised in our hydrogen to satisfy their future domestic energy
cars, for heating and cooking in Australian homes, needs and will inevitably be heavily reliant on
offices and industrial plants in the near term. The hydrogen imports. Net energy importing countries
Toyota Hydrogen Centre in Altona, Melbourne such as Japan have articulated geopolitical
18 | ENERGYNEWS | Q1 2020Feature
"Net energy importing countries such as Japan
have articulated geopolitical reasons for
preferring to source their hydrogen from stable
economies such as Australia"
reasons for preferring to source their hydrogen Standards Australia has appointed Rachelle
from stable economies such as Australia. Doyle from Woodside Energy to lead its ME-093
The recent groundswell of interest in hydrogen Hydrogen Technologies committee charged with
is in no short measure the result of the sustained the development, modification and adoption of
co-ordinated efforts of the National Hydrogen new and existing Australian and international
Taskforce led by the Commonwealth Government’s standards covering hydrogen generation, storage,
Alison Reeve, Nicole Henry and Dr Alan Finkel who transport, refuelling, fuel cells and health, safety
presented the National Hydrogen Strategy (NHS) and environment.
to the Council of Australian Governments (COAG) Deliberations of the ME-093 committee
late last year after extensive consultation with
are geared to harmonising Australian and
government and industry stakeholders.
international standards and easing local regulatory
In a rare, landmark national achievement, the or compliance barriers to hydrogen project
recommendations of the NHS were unequivocally development and operation. Adelaide hosted the
and unanimously endorsed and accepted by
5th International HySafe Conference last year with
COAG Energy Ministers, presenting opportunities
proceedings confirming that hydrogen does not
for the accelerated development and scale up of
pose any additional safety risk to operators and
hydrogen pilot and research projects.
consumers over and above conventional fuels.
The NHS extends the initiative of State
New hydrogen lobby and advocacy groups
governments that have scoped out or are
developing dedicated hydrogen strategies, including The Australian Hydrogen Council
roadmaps and policies to establish frameworks (formerly Hydrogen Mobility Australia), The
to support greater market uptake of hydrogen Hydrogen Society of Australia and the Smart
and draw private investment into their states Energy Council’s Hydrogen Australia have been
economies. formed to advance the cause.
Dr Finkel has provided much-needed leadership The local hydrogen industry is poised for
in hydrogen over and above his core role as a significant development over the coming years.
scientific advisor to government. Although not What is not clear is how quickly it will evolve as
a popular perspective to share, he and others a mainstream commercial fuel and commodity
have identified that hydrogen demand cannot be and on what scale. This is an area of industry
satisfied by renewable hydrogen alone and not development that will hold great interest to AIE
well after 2050. members monitoring the energy transition.
Commonwealth and the majority of State
governments are offering grants to support Luigi Bonadio is a Melbourne-based chemical
hydrogen project development including engineer with over 25 years of local and
investments of $300 million from the Clean Energy international project management, engineering and
Finance Corporation’s Advancing Hydrogen Fund consulting experience. He designs and implements
and $70 million from ARENA to support the clean energy and water management solutions
development and demonstration of electrolyser for a broad range of government and corporate
technologies. clients operating across commercial and industrial,
National Energy Resources Australia (NERA) is manufacturing and transport sectors. Luigi sits
running a series of hydrogen industry stakeholder on AIE Melbourne’s committee and is Engineers
workshops across the country to consider the Australia’s representative on the Standards
benefits and efficacy of investments in the Australia ME-093 Hydrogen Technologies
formation of hydrogen clusters. Committee and Working Groups 1, 2, 3 and 5.
Q1 2020 | ENERGYNEWS | 19Feature An opportunity for the mining sector to lead in decarbonisation By Catherine Bell, BDO Global Natural Resources Industry Program Market dynamics are shifting fast and there is conference in Cape Town with Justin Boyce Cam, a growing expectation across all industries and M&A Partner of BDO Australia stating: “It’s a very businesses to reduce emissions. difficult equity market for juniors now. There is The Australian Prudential Regulation Authority a dearth of capital for development in public (APRA) and the Australian Securities and markets and fund managers are moving away from Investments Commission (ASIC) have begun mining for reputational reasons”. to weigh in heavily on businesses to become Miners are having to fight hard to prove the value more transparent with shareholders and other of projects, and to ensure that they fulfil the stakeholders on the financial and other impacts on growing Environmental, Social and Governance business of growing climatic events. (ESG) parameters that fund managers are The Reserve Bank of Australia (RBA) has also imposing. This is evidenced by the world’s largest begun to voice a concern over the risks posed by asset manager BlackRock announcing earlier this climate change with Deputy Governor Guy Debelle year that sustainability will be its new standard. quoted as saying “financial stability is better Sherif Andrawes, BDO’s Head of Global Natural served by an orderly transition to the low carbon Resources says that “mining companies must start economy rather than an abrupt disorderly one”. positioning themselves as part of the solution to The global evolution away from fossil fuels is the energy transition, not part of the problem. having a profound impact on traditional business, The energy transition to decarbonise is largely particularly mining. It is requiring a re-think dependent on the mining sector and it will be of business models and the adoption of new the rare earth/battery minerals, and even the technologies, which is never easy, especially for discovery of mineral X, which will be required in those companies that do not have the financial the manufacture of clean energy technologies”. capacity of the major miners. Mining companies have a huge opportunity to But the opportunity cost is becoming too great lead and have historically been very innovative. for any company to ignore. Public opinion around Apart from supplying the minerals required for use the energy transition is also turning investors away in renewable technologies, one area that mining from mining projects and into renewables. It was companies are investing in is the deployment of a recurring theme at the recent Mining Indaba renewable energy microgrids. 20 | ENERGYNEWS | Q1 2020
Feature

Rio Tinto has just announced plans to build a solar
farm to power its $2.6 billion Koodaideri iron ore
mine, something that is envisaged to help power
its entire Pilbara network.
Mining and exploration group IGO’s managing
director Peter Bradford said: “At IGO we believe
in the green energy future and are committed to
renewable energy sources as we strive to reduce
our carbon footprint. The development of this
innovative hybrid energy solution (operated by
Zenith Energy) will also improve our cost structure
with targeted renewable power insertion of up to
50% of demand via the solar PV facility.”
IGO has also developed a ‘Proactively Green’
mining concept which enhances its sustainability
framework to encompass better resource
utilisation, better resource access, use of
technology and sensors in exploration and
improved land access practices guided by the
‘shared value’ concept.                                Although capital costs to electrify existing
Goldfields CEO Nick Holland has been quoted as         underground mines are quite cost prohibitive at
saying: “Renewables make for great business –          present, the improvements in technology and
lower cost and supply security. Independence from      reduced costs in the near future means it is very
the grid is critical – microgrids are the future!”.    likely that it will be commonplace to see new
                                                       mines being fully electric in Australia.
Falling renewable costs, cost and productivity
gains, fit for purpose solutions, health and safety,   Given the capital intensity of mining, remote
market differentiation and increased pressures to      operating environments and new technology
reduce – and report on – emissions are the drivers     solutions coming to market, this is a perfect time
that will see more remote mining locations follow      for mining companies to re-think their business
suit.                                                  models and re-position themselves for a low-
The tipping point of renewables costs has been         carbon future.
met in many locations around the world, meaning        Mining companies should see the move to
that it is now cheaper to deploy renewables than it    decarbonise as an opportunity to promote other
is to use diesel.                                      aspects of the business – be it the health and
Increasingly the solutions coming to market are        safety of employees, attracting talent, innovative
now more aligned to the needs of mining projects       partnerships, becoming environmental stewards of
and timelines via purchase power agreements, re-       the land they operate and/or opportunities to build
deployable solar solutions and mixed technology        capacity within remote communities.
solutions that ensure reliability.                     The growing emphasis on miners to demonstrate
Opportunities for underground mines to electrify       their social license to operate will only increase in
are being driven less by emission reduction but        today’s global ‘go green’ movement.
more by health and safety concerns.                    The values of consumers, investors and employees
The increased awareness around chronic health          are shifting, and so too must business. It will be
issues associated with the presence of nano diesel     the pursuit of satisfying all these while at the
particulate (nDPM) matter in underground mines is      same time turning a profit that will see mining
requiring a solution. That could be electrification,   companies re-emerge as business partners for a
filtration and/or improved ventilation.                green future.

“The energy transition to decarbonise is largely
dependent on the mining sector... Mining
companies must start positioning themselves as
part of the solution”

                                                                                 Q1 2020 | ENERGYNEWS | 21
You can also read


