Investment Outlook: 2020 Midyear Outlook - Concurrent Advisors Investment Committee
←
→
Page content transcription
If your browser does not render page correctly, please read the page content below

Investment Outlook: 2020 Midyear Outlook
Concurrent Advisors
Investment Committee
                                         1
Investment Committee

     Eddy Augsten CAIA,    Michael M Mikeska,          Bill Rice III, CPM ®    Craig Weinstein AIF®
        CIMA®, MSF            CFP®, CIMA®            Investment Executive,     Wealth Advisor, RJFS
    Branch Manager, RJFS   Wealth Advisor, RJFS                RJFS

     Todd Schwartz, CFP®    Mike Kanner, CRPS®         Robert Bell, CRPS®          Mark Johnson
     Branch Owner, RJFS    Financial Advisor, RJFS   Financial Advisor, RJFS   Financial Advisor, RJFS

                                                                                                         2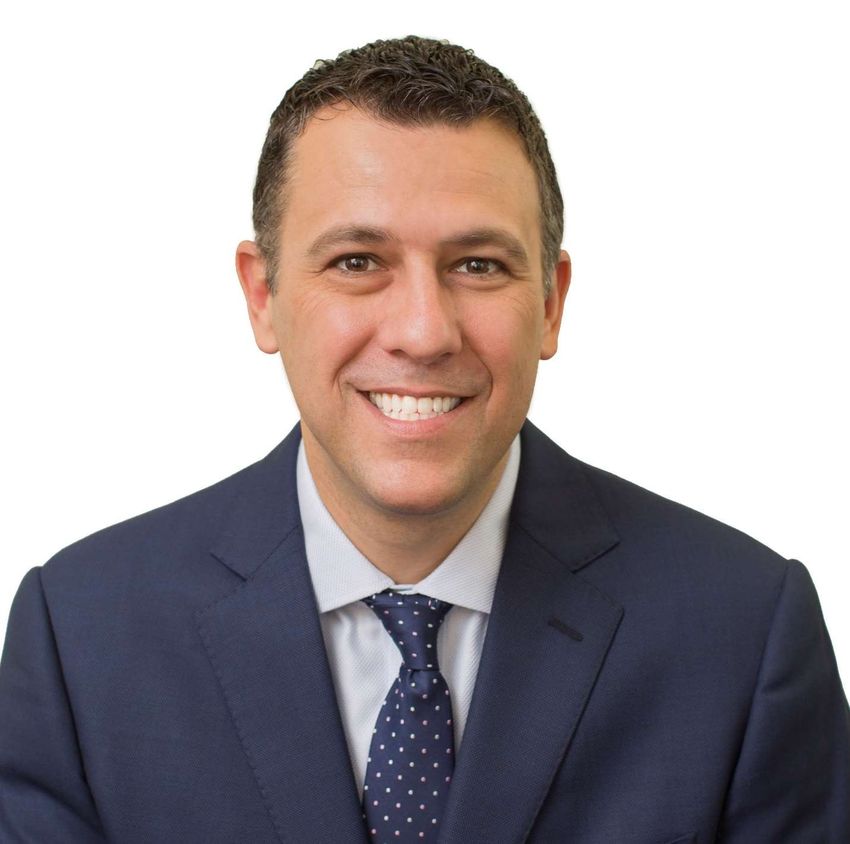
Table of Contents

Economic Outlook:                      4-7     Asset Allocation                         15-19
Economic Review                        8-11    Strategic vs Tactical Asset Allocation
Restarting the Economy                         Asset Class Returns
U.S. Employment                                Domestic Equity Returns
The Great Lockdown - Recession 2020            Equity Sectors Returns
Ballooning Debt                                Fixed Income Returns
Themes                                 12-14   Assessment                                20
Fund Flows – A run for safety                  Contact                                   21
Household vs Corporate Debt: Zombies           Disclosure                               22-25
Equity Markets – Out of Sync

                                                                                                3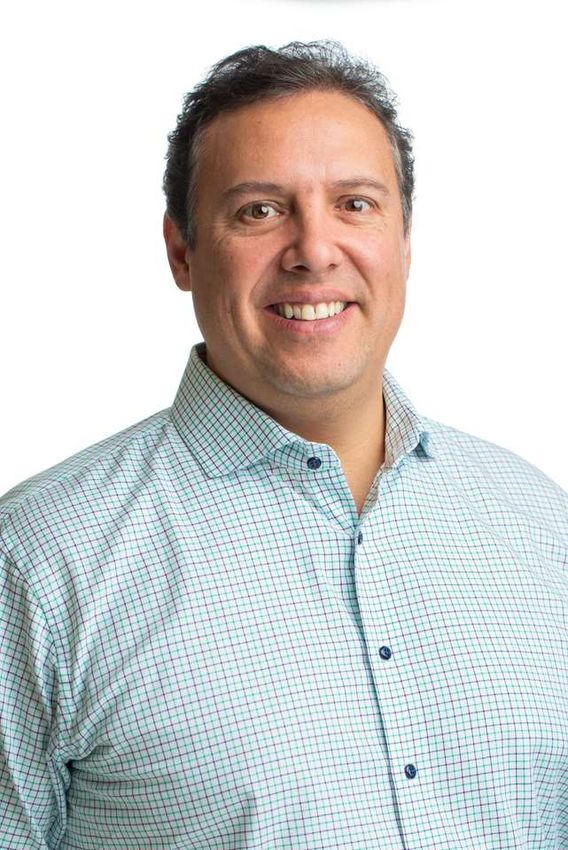
Unprecedented – It really has been!

Google search of word “unprecedented”
                                                                                                                                                              Day trading!
  peaks in March as market bottoms.

   ‘We were headed towards a mild, short
  recession. Then the COVID-19 pandemic
      struck and changed everything.’
— Campbell Harvey, famed Duke Professor “with perfect                                                                                                         Unprecedented!
               record.” Marketwatch

 Google search of words “day trading”
    skyrockets March-June 2020.

 An unprecedented event catapults the world into recession but spawn's new day traders taking great risks and making a quick
                                                            buck.

    @Google Trends https://trends.google.com/trends/explore?date=all&geo=US&q=unprecedented
    https://www.marketwatch.com/story/economic-expert-with-perfect-record-calling-recessions-is-betting-this-one-will-be-over-by-the-end-of-2020-2020-05-06
                                                                                                                                                                             4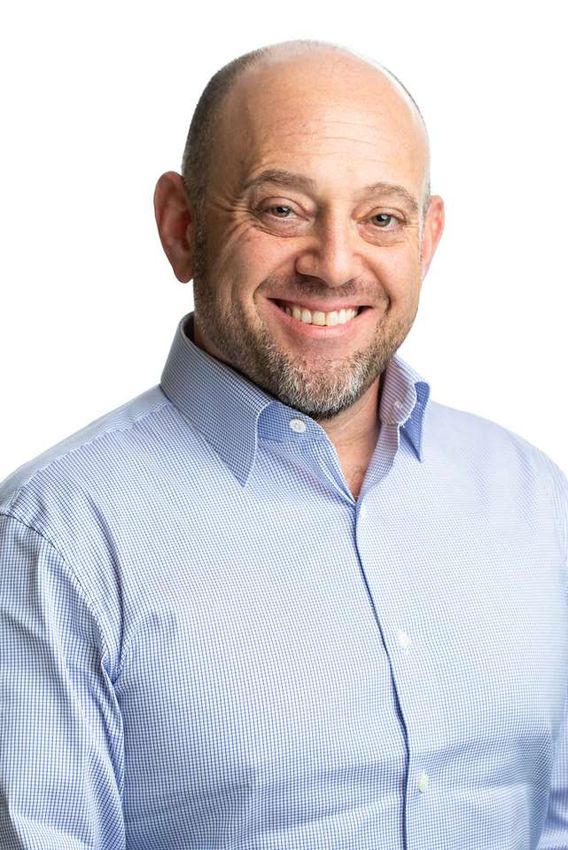
Unprecedented
The first half of 2020 is best described as unprecedented. It While we started 2020 positioned for supportive growth, we were
should, by no means, be a surprise that the stock market had one focused on the election and the Phase One trade deal with China.
of its best quarters ever following one of the worst economic We find ourselves again dealing with the election and renewed
shocks in history. trade tensions but overwhelmed by the virus and ongoing stimulus.
The S&P 500 peaked on February 19th,2020, ending an 11-year Bull Coming into the second quarter we knew economic data was
market and gaining over 529% (total return) or over 18% going to be unprecedented, fitting for a pandemic that saw the
annualized since March 9th, 2009. After peaking in February, the world come to its knees.
S&P 500 lost 33.8% over the worst 23-day trading period in the last
As the data came in, the economy did not fail to amaze. The
30-years. Bottoming on March 23rd the S&P 500 rebounded over
numbers and charts will fail to provide the human context of this
40% by early June but has been relatively flat since then.
tragedy. The economic data is not the only story though. The
The Federal Reserve started lowering rates in 2019 as the 2017 tax response from the Federal Reserve, the U.S. Treasury, and the
cuts wore off and unemployment hit record lows, but business Government is equally unprecedented.
investment slowed, and inflation remained stagnant. Coupled with
As we found ourselves in the depth of the panic, the Federal
a global slow down and trade tensions, fixed income and currency
Reserve (Fed) and the Treasury responded swiftly starting on
markets were offering plenty of cautionary signs as we hit new
March 15th by cutting the Fed Funds Rate to zero. You can find a
highs in January and February of this year.
laundry list of their response to markets here.
Data source: Factset
5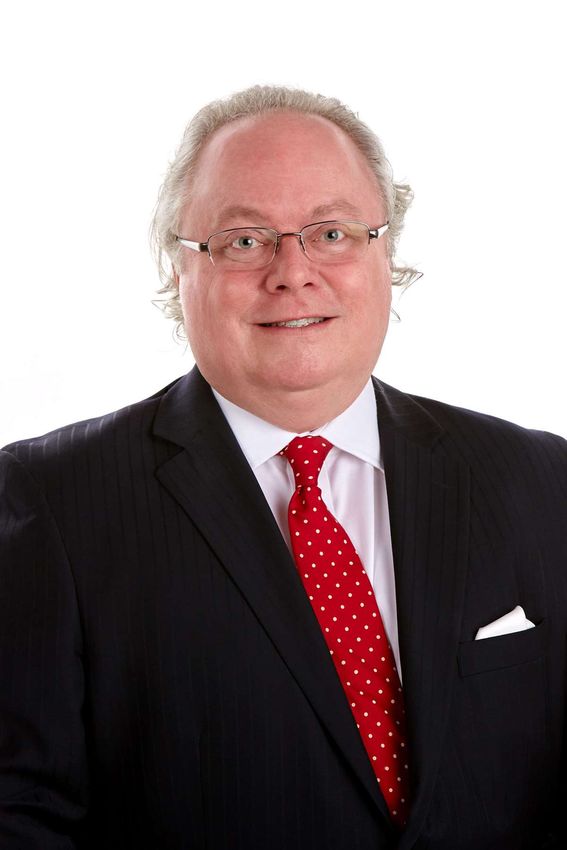
Unprecedented (Cont.)
The Fed’s response not only provided markets a bottom on March 23rd is likely PPP underwrote much of May and June’s surprise in job
but also reassurance that the amount of liquidity and market gains along with the nation’s partial reopening.
intervention would see the worst behind us. The Federal Government
Before making a full circle back towards February highs, the rally
followed through with the CARES Act signed into law on March 27th,
seemed to stall by early June as investors hang on every piece of
the largest economic stimulus bill ever passed in U.S. history.
news on the virus, reopening the economy, and a vaccine. A perfect
Along with worsening conditions of the Coronavirus, the extra $600 display of our confirmation bias, the tendency to search for and
per week in enhanced unemployment benefits is the greatest risk to favor information that supports and confirms our beliefs.
the economy and the stock market coming into Q3. The stimulus
As we venture into the second half of 2020 it is important to
ends in July and expectations are high that the Federal Government
consider how fast we moved and understand that upside seems
will act accordingly, but will they do so in time, will the stimulus be
limited without a vaccine. While we do not see a retest of the
the same, less, or more?
march bottom, we do advise caution. Though much of June’s
The current stimulus is providing many Americans more income than economic data is missing from this report, as we see it trickle in, we
they were getting from their previous jobs1 giving them confidence are confident it will continue to surprise to the upside and be better
and comfort and leading to consumption as well as skyrocketing than expected.
savings.
The market waits patiently, assumingly, and passively vulnerable to
This enhanced unemployment benefit and the Paycheck Protection the Federal Government and Federal Reserve.
Program (PPP) have had an incredible impact on the economy, but it -
Data source: Factset
6
Unprecedented (Cont.)
In summary, Q2 was driven by unprecedented government While Q3 will continue with the same storyline we will see
intervention, improving trends in the spread of Coronavirus, renewed focus on the earnings, the Presidential election and
reopening of the economy, and expectation of a vaccine by early Trade. The market is still near highs and we believe valuations
2021. are stretched, any of the above can warrant a correction. The
Federal Reserve, US Treasury and Federal Government acted
Hope of a vaccine. The market already expects a vaccine by
swiftly, and Americans did not witness what would have
early 2021, anything sooner is a positive surprise. Any news
otherwise been expected with 20-million unemployed, but risks
that delays that expectation is a negative.
abound with the Governments intervention and we are months if
Coronavirus positivity rates, hospitalizations, and fatalities.
not years from a vaccine. We believe Caution, patience, and
While infections continue to rise as states reopen, fatalities
vigilance are the way forward.
have not risen as fast. It appears older Americans that were
severely impacted early in the pandemic have taken the virus Stay safe,
seriously and social distancing and as younger Americans
Eddy Augsten and the Concurrent Advisors Investment
venture out, cases are rising but fatalities are not.
Committee
Economic reopening. The recent spike in coronavirus cases as
is worrisome and is prompting some states to roll back or slow
reopening. This is a concern we are watching and a warning
that data may again slow after May and June recoveries. As we
continue to reopen the economic data will likely beat
expectations.
1https://fivethirtyeight.com/features/many-americans-are-getting-more-money-from-unemployment-than-they-were-from-their-jobs/
Data source: Factset 7
Economy Restarting? Yes, but slowly                                                                                                          Markets cheered as Retail Sales surged
                                                                                                                                             by a record 17.7% in May.

                                Early signs of economic activity
                                picking up, but long road ahead!

             Hysteria

                                                                             Normalizing

                                                                                                Long road
                                                                                                  ahead
Source: Natixis PRCG, New York Federal Reserve, US Census, https://joinhomebase.com/data/covid-19/, https://1010data.exabel.com/covid-19/.
Small business hours worked rates compare that day vs. the median for that day of the week for the period Jan 4, 2020 to Jan 31, 2020.                                        8
https://www.marketwatch.com/story/retail-sales-surge-a-record-177-in-may-but-coronavirus-wounds-still-visible-2020-06-16
US Employment                                                          Insured Employed (06/13/2020)
                                                                         Seasonally Adjusted        19,522,000
                                                                         Non-Seasonally Adjusted    17,921,282

                                             Less than 14 weeks

                                                                                                                 < High School

                                                                                                                 High School /
                                                                                                                 No College
                                                                                                                 Some College

                                                                                                                 Bachelor or
                                                                                                                 higher
As of 2/29/20, the U.S. had a jobless rate of 3.5% with 5.8 million out-
 of-work Americans. As of 4/30/20, U.S. jobless rate was 14.7% with
23.1 million out-of-work Americans. May employment report surprises
     with $2.5 million gain, possibly signifies a bottom, but mostly
           represented by CARES Act, still long road ahead.

       https://www.frbatlanta.org/cweo/data-tools/unemployment-claims-monitor
       https://www.bls.gov/charts/employment-situation                                                                           9
       Department of Labor
Real GDP – The Great Lockdown
                                                                                 The longest bull market in history falls to the Coronavirus. While Q1 included 1-month of a national
                                                                                 lockdown, Q2 included two months followed by much of the country re-opening to some degree in
                                                                                   May. May and June saw big rebounds as desperation led to consumption and many economic
                                                                                  indicators spiked from Retail sales to driving and Flash PMI’s which survey the private sector on
                                                                                  output, new orders, and prices across the manufacturing, construction, retail and service sectors.

                                                                                                                                                            Nearly a 7% swing Q419-Q120

                                                                                                                                                                      *Projected, 11% swing
                                                                                                                                                                                   Q419-Q220

It’s official!
“The National Bureau of Economic
Research on Monday said a 128-month
expansion — the longest dating to 1854 —
came to a halt in February. The recession
also began the same month.” Marketwatch
                                                                              The shortest US recession in the last 100 years was the 6-month economic downturn that ran from
                                                                                                     January 1980 to July 1980. How will this one fair?

  National Bureau of Economic Research , https://www.bea.gov
  Projected Q2, https://www.cbo.gov/publication/56351                                                                                                                                   10
  https://www.marketwatch.com/story/us-entered-recession-in-march-after-end-of-longest-expansion-in-history-nber-finds-2020-06-08
Ballooning debt, a problem for another day.
A Trillion here, a Trillion
there.
The Fed's balance sheet increased almost
two-fold as a result of stimulus measures
such as the CARES Act.
The Balance Sheet was on an
unsustainable path before the pandemic.
There is no rush and supporting the
economy comes first, but as they say
chickens come home to roost.
Raymond James Investment Quarterly July 2020
11Record flows from funds/ETFs into Money Market
Volatility and uncertainty lead investors to
sell equity and bonds and move to money
market funds which saw a trillion dollars of
new flows, much of which hasn’t flowed
back to stocks. Many missing the rebound.
U.S. Category Groups' 12-Month Asset Flows
Volatility surpasses 2008 levels.
Dwarfing all previous records, Money Markets saw $1.1 trillion inflows in 11-
weeks during the crisis, while seeing over $100 billion leave Money Markets
over the last 6-weeks.
CBOE Exchange, Inc.
Lipper Rifinitiv https://lipperalpha.refinitiv.com, https://www.financialresearch.gov/money-market-funds/, https://fred.stlouisfed.org/series/MMMFTAQ027S
Investment Company Institute https://ici.org/research/stats 12Household Debt vs Corporate Debt
Watch for Zombies! After years of
overborrowing, much of which went towards
stock buybacks, many companies were not
prepared for this crisis. The Fed solved a
Personal Households liquidity issue by stepping into the markets but
what about a solvency issue. Many can't cover
their debt; bankruptcies are likely to increase.
Households are in great shape. Watch new
government stimulus. Watch new Junk Bond
Corporations
record issuance.
Personal savings has skyrocketed during the lockdown! This includes
unemployment insurance. Pent up demand can be seen spurring
recovery across the economy during May and June. BUT enhanced
While household leverage is believed to have made the 08/09 unemployment benefits end in July, creating an “Income cliff”
Financial Crisis the “Great” Recession, this time around, it’s
corporations that have over levered while households have
done well managing their balance sheets.
https://fredblog.stlouisfed.org/2020/04/household-debt-meets-corporate-debt/?utm_source=twitter&utm_medium=SM&utm_content=stlouisfed&utm_campaign=f41eb6d1-12d1-4650-806b-e6dea3027589
https://www.cnbc.com/2020/06/16/economist-mohamed-el-erian-warns-about-the-risk-of-zombie-markets.html 13
https://www.cnbc.com/2020/06/26/whats-more-likely-second-stimulus-check-or-back-to-work-bonus.html?__source=androidappshareEquity – Out of Sync
Equity markets send cautionary signals! By most metrics’ the S&P 500 seems stretched. The
economic data must catch up. At these levels' investor expectations should be low. And while stocks still
look relatively more attractive than bonds, investors shouldn’t chase stocks on the fear of missing out
(FOMO). Look for confirmation from new Federal stimulus, continued economic reopening and a vaccine
on the horizon. As corporate profits expand so will opportunities in stocks. Consider diversification across
asset classes and geography to provide better risk adjusted returns.
https://www.blackrock.com/us/individual/literature/investment-commentary/taking-stock-quarterly-outlook-en-us.pdf
14Strategic vs Tactical Allocation
Investment Committee - Tactical Asset
Allocation Weights - Survey
CONSERVATIVE
MODERATE
MODERATE
MODERATE
GROWTH Equity
CONSERVATIVE GROWTH
U.S.
EQUITY 27% 47% 64% 78% 93%
Large
U.S. Large Cap Blend 17% 19% 24% 28% 34%
U.S. Large Cap Growth 0% 3% 5% 7% 8%
Mid
U.S. Large Cap Value 0% 5% 7% 9% 10% Small
U.S. Mid Cap Equity 2% 5% 7% 8% 10% International
U.S. Small Cap Equity 1% 3% 4% 6% 6%
Developed
Non-US Developed Market
Equity
7% 12% 13% 16% 20% Emerging
Emerging Markets Equity 0% 0% 4% 4% 5% Fixed income
FIXED INCOME 71% 51% 34% 20% 0%
Core
Investment Grade Intermediate
Short
Maturity Fixed Income 48% 36% 24% 15% 0%
Intermidiate
Investment Grade Short Long
15% 11% 7% 5% 0%
Maturity Fixed Income Plus
Non-Investment Grade Fixed High Yield
3% 2% 0% 0% 0%
Income International
Multi-Sector Fixed Income 5% 2% 3% 0% 0%
Multisector
ALTERNATIVES 0% 0% 0% 0% 5%
CASH & CASH Alternatives
2% 2% 2% 2% 2%
EQUIVALENTS Cash & Cash
100% 100% 100% 100% 100%
Equivalents
Underweight Neutral Overweight
As of June 2020: Strategic Allocation source Raymond James, Capital Market Assumptions Mercer, Tactical Allocation Concurrent Advisors Investment Committee.
NOT a recommendation 15Broad Asset Class Returns
2010 2011 2012 2013 2014 2015 2016 2017 2018 2019 YTD
Non-US Non-US Cash & Cash
Real Estate Fixed Income US Equities Real Estate US Equities Real Estate US Equities Fixed Income
Equities Equities Alternatives
40.4% 7.8% 17.0% 32.4% 14.3% 1.4% 15.3% 24.8% 1.8% 31.5% 6.1%
Blended Non-US Non-US Cash & Cash
Commodities US Equities US Equities Fixed Income US Equities US Equities Fixed Income
Portfolio Equities Equities Alternatives
16.7% 2.3% 16.0% 21.6% 13.7% 0.5% 12.0% 21.8% 0.0% 23.2% 0.5%
Blended Blended Blended Blended Blended Blended Blended Blended
US Equities US Equities Commodities
Portfolio Portfolio Portfolio Portfolio Portfolio Portfolio Portfolio Portfolio
15.1% 2.1% 11.4% 17.0% 8.0% 0.5% 11.4% 15.0% -4.0% 21.1% -0.6%
Blended Cash & Cash Cash & Cash Cash & Cash Blended
Fixed Income Fixed Income Fixed Income US Equities Real Estate US Equities
Portfolio Alternatives Alternatives Alternatives Portfolio
10.8% 0.1% 4.2% 0.0% 6.0% 0.0% 6.9% 3.5% -4.4% 19.5% -3.1%
Non-US Cash & Cash Non-US Non-US Cash & Cash Non-US
Real Estate Real Estate Fixed Income Real Estate Fixed Income
Equities Alternatives Equities Equities Alternatives Equities
9.4% -2.2% 0.6% -2.0% 0.0% -2.6% 3.3% 0.8% -7.6% 8.7% -11.2%
Non-US Cash & Cash Non-US
Fixed Income Commodities Real Estate Fixed Income Commodities Commodities Commodities Commodities
Equities Alternatives Equities
6.5% -11.8% 0.1% -9.6% -3.9% -24.2% 2.6% 0.7% -13.0% 5.4% -19.7%
Cash & Cash Cash & Cash Non-US Cash & Cash
Commodities Commodities Real Estate Commodities Commodities Real Estate Real Estate
Alternatives Alternatives Equities Alternatives
0.1% -13.4% -1.1% -25.8% -17.0% -24.7% 0.3% -0.2% -13.6% 2.2% -22.4%
Source: Raymond James Capital Market Review As of July 2020, Factset
The Blended Portfolio allocation is 45% S&P 500 Index / 15% MSCI EAFE Index / 40% Bloomberg Barclays Aggregate Index. 16Domestic Equity Returns
2010 2011 2012 2013 2014 2015 2016 2017 2018 2019 YTD
Mid Growth Large Growth Mid Value Small Growth Large Growth Large Growth Small Value Large Growth Large Growth Large Value Large Growth
30.6% 4.7% 18.5% 42.7% 14.9% 5.5% 31.3% 27.4% 0.0% 31.9% 7.9%
Small Growth Small Growth Small Value Small Blend Large Blend Small Growth Small Blend Large Blend Small Growth Large Blend Large Blend
28.0% 3.6% 18.2% 41.3% 13.7% 2.8% 26.6% 21.8% -4.1% 31.5% -3.1%
Mid Blend Large Blend Mid Blend Small Value Large Value Mid Growth Mid Value Mid Growth Large Blend Large Growth Mid Growth
26.6% 2.1% 17.9% 40.0% 12.4% 2.0% 26.5% 19.9% -4.4% 31.1% -5.2%
Small Blend Small Blend Large Value Mid Value Mid Value Large Blend Small Growth Mid Blend Small Blend Mid Growth Small Growth
26.3% 1.0% 17.7% 34.3% 12.1% 1.4% 22.2% 16.2% -8.5% 26.3% -11.5%
Small Value Large Value Mid Growth Mid Blend Mid Blend Small Blend Mid Blend Large Value Large Value Mid Blend Mid Blend
24.7% -0.5% 17.3% 33.5% 9.8% -2.0% 20.7% 15.4% -9.0% 26.2% -12.8%
Mid Value Mid Growth Small Blend Mid Growth Mid Growth Mid Blend Large Value Small Growth Mid Growth Mid Value Large Value
22.8% -0.9% 16.3% 32.8% 7.6% -2.2% 17.4% 14.8% -10.3% 26.1% -15.5%
Large Value Small Value Large Blend Large Growth Small Value Large Value Mid Growth Small Blend Mid Blend Small Value Small Blend
15.1% -1.4% 16.0% 32.8% 7.5% -3.1% 14.8% 13.2% -11.1% 24.5% -17.9%
Large Blend Mid Blend Large Growth Large Blend Small Blend Mid Value Large Blend Mid Value Mid Value Small Blend Mid Value
15.1% -1.7% 14.6% 32.4% 5.8% -6.7% 12.0% 12.3% -11.9% 22.8% -21.0%
Large Growth Mid Value Small Growth Large Value Small Growth Small Value Large Growth Small Value Small Value Small Growth Small Value
15.1% -2.4% 14.6% 32.0% 3.9% -6.7% 6.9% 11.5% -12.6% 21.1% -24.5%
Source: Raymond James Capital Market Review As of July 2020, Factset
17Equity Sector Returns
2010 2011 2012 2013 2014 2015 2016 2017 2018 2018 YTD
Consumer Consumer Information Information Information
Real Estate Utilities Financials Real Estate Energy Health Care
Discretionary Discretionary Technology Technology Technology
32.3% 20.0% 28.8% 43.1% 30.2% 10.1% 27.4% 38.8% 6.5% 50.3% 15.0%
Consumer Consumer Consumer Consumer
Health Care Utilities Health Care Comm Services Materials Utilities Comm Services
Discretionary Staples Discretionary Discretionary
27.7% 14.0% 23.9% 41.5% 29.0% 6.9% 23.5% 23.8% 4.1% 32.7% 7.2%
Consumer Consumer Consumer
Industrials Health Care Real Estate Industrials Health Care Financials Financials Comm Services
Staples Discretionary Discretionary
26.7% 12.7% 19.7% 40.7% 25.3% 6.6% 22.8% 23.0% 0.8% 32.1% -0.3%
Information Information Information
Materials Real Estate Comm Services Financials Industrials Financials S&P 500 Health Care
Technology Technology Technology
22.2% 11.4% 18.3% 35.6% 20.1% 5.9% 18.9% 22.2% -0.3% 31.5% -0.8%
Consumer
Energy Comm Services Health Care S&P 500 Real Estate Materials Health Care Real Estate Industrials S&P 500
Staples
20.5% 6.3% 17.9% 32.4% 16.0% 4.7% 16.7% 22.1% -2.2% 29.4% -3.1%
Consumer Information Consumer
Comm Services S&P 500 Financials Comm Services Utilities S&P 500 S&P 500 Real Estate
Discretionary Technology Staples
19.0% 6.1% 16.0% 28.4% 15.2% 3.4% 16.3% 21.8% -4.4% 29.0% -5.7%
Consumer Information Consumer Consumer
S&P 500 Energy Industrials S&P 500 S&P 500 Industrials Materials
Staples Technology Staples Discretionary
15.1% 4.7% 15.3% 26.1% 13.7% 1.4% 13.8% 21.0% -8.4% 27.9% -6.9%
Consumer Information Consumer Consumer
Materials Materials Industrials Financials S&P 500 Comm Services Real Estate
Staples Technology Staples Staples
14.1% 2.4% 15.0% 25.6% 9.8% -1.5% 12.0% 13.5% -12.5% 27.6% -8.5%
Information Consumer Consumer
Financials S&P 500 Energy Industrials Utilities Financials Utilities Utilities
Technology Discretionary Discretionary
12.1% 2.1% 14.8% 25.1% 9.7% -2.5% 6.0% 12.1% -13.0% 26.3% -11.1%
Information Consumer Consumer
Industrials Utilities Materials Utilities Real Estate Industrials Materials Industrials
Technology Staples Staples
10.2% -0.6% 10.8% 13.2% 6.9% -4.8% 5.4% 10.8% -13.3% 24.6% -14.6%
Utilities Materials Energy Comm Services Comm Services Materials Real Estate Energy Materials Health Care Financials
5.5% -9.8% 4.6% 11.5% 3.0% -8.4% 3.4% -1.0% -14.7% 20.8% -23.6%
Health Care Financials Utilities Real Estate Energy Energy Health Care Comm Services Energy Energy Energy
2.9% -17.1% 1.3% 1.6% -7.8% -21.1% -2.7% -1.3% -18.1% 11.8% -35.3%
Source: Raymond James Capital Market Review As of July 2020, Factset
18Fixed Income Returns
2010 2011 2012 2013 2014 2015 2016 2017 2018 2019 YTD
Long-Term Emerging Long-Term Long-Term Long-Term
High Yield High Yield Municipal High Yield T-Bill Treasury
Bond Market Bond Bond Bond Bond
15.1% 17.1% 17.9% 7.4% 16.4% 3.3% 17.1% 12.2% 1.8% 23.4% 8.7%
Emerging Long-Term Emerging Short-Term Aggregate
Municipal High Yield Agency Municipal Agency High Yield
Market Bond Bond Market Bond Bond Bond
12.8% 10.7% 15.8% 1.0% 9.1% 1.8% 10.2% 8.2% 1.4% 14.3% 6.1%
Long-Term Long-Term Short-Term Emerging Global Bond ex Long-Term
Treasury Credit MBS Municipal Credit
Bond Bond Bond Market Bond US Bond
10.7% 9.8% 12.7% 0.3% 7.5% 1.5% 9.9% 8.0% 1.3% 13.8% 5.9%
Emerging Emerging
Credit Credit Credit T-Bill MBS Credit High Yield Agency Credit
Market Bond Market Bond
8.5% 8.4% 9.4% 0.0% 6.1% 1.3% 5.6% 7.5% 1.1% 13.1% 4.8%
Global Bond ex Aggregate Aggregate Aggregate Aggregate
Municipal US TIPS Treasury Credit MBS MBS
US Bond Bond Bond Bond
8.4% 7.8% 6.8% -0.9% 6.0% 0.8% 2.6% 6.2% 1.0% 8.7% 3.5%
Aggregate Emerging Aggregate Aggregate Short-Term
MBS Treasury Agency Municipal Treasury Municipal
Bond Market Bond Bond Bond Bond
6.5% 7.0% 4.2% -1.5% 5.1% 0.5% 2.6% 5.4% 0.9% 7.5% 3.0%
Emerging Short-Term Aggregate
Treasury MBS MBS Credit US TIPS US TIPS Treasury Municipal
Market Bond Bond Bond
5.9% 6.3% 2.6% -2.0% 4.8% 0.4% 2.5% 3.5% 0.7% 6.9% 2.1%
Global Bond ex Aggregate Global Bond ex Aggregate
MBS Treasury High Yield T-Bill Agency MBS US TIPS
US Bond US Bond
5.4% 6.1% 2.0% -2.0% 2.5% 0.0% 2.2% 2.9% 0.0% 6.4% 1.1%
Global Bond ex
US TIPS High Yield US TIPS Municipal Agency US TIPS MBS MBS US TIPS Agency
US
2.7% 5.0% 1.7% -2.6% 1.0% -0.4% 1.7% 2.5% -0.3% 4.5% 1.0%
Short-Term Global Bond ex Global Bond ex
Municipal US TIPS Agency Treasury Credit Treasury Treasury High Yield
Bond US US
2.4% 2.6% 1.0% -2.7% 0.7% -0.8% 1.0% 2.3% -2.1% 4.5% 0.9%
Short-Term Short-Term Short-Term Emerging Global Bond ex Short-Term Short-Term
T-Bill T-Bill Credit T-Bill
Bond Bond Bond Market Bond US Bond Bond
2.4% 1.5% 0.3% -4.1% 0.0% -3.6% 0.6% 0.8% -2.1% 3.3% 0.5%
Long-Term Emerging Emerging
Agency Agency T-Bill US TIPS High Yield T-Bill US TIPS T-Bill
Bond Market Bond Market Bond
1.0% 1.0% 0.1% -6.6% -1.4% -4.5% 0.3% 0.4% -2.5% 2.2% -0.4%
Global Bond ex Global Bond ex Global Bond ex Long-Term Short-Term Long-Term
T-Bill T-Bill Municipal Agency High Yield
US US US Bond Bond Bond
0.1% 0.1% -0.6% -7.1% -3.5% -4.6% 0.2% 0.3% -6.8% 1.0% -3.8%
Source: Raymond James Capital Market Review As of July 2020, Factset
19Investment Committee Assessment
Current State
We seem to be past the bottom – but moved too fast, expect volatility.
Stimulus worked - Two-thirds of recipients received more than they were earning*,
and May & June data shows consumers spent money.
Current Risk
Second peak in Covid-19 – watch test positivity rates. Slight acceleration for now.
End of Stimulus payments – Unemployment checks end in July.
Legislators need to act in a timely and effective manner. (Again)
Most measure show equity valuation are high.
Corporate Debt, bankruptcy risk and record appetite for new Junk Bond issuance
Assessment
The Federal Reserve, US Treasury and Congress acted swiftly, and Americans did
not witness what would have otherwise been expected with 20-million
unemployed.
Risks abound with the Governments intervention and we are months if not years
from a vaccine. Caution, patience, and vigilance is the way forward.
*https://www.marketwatch.com/story/a-staggering-number-of-laid-off-workers-are-receiving-more-money-from-unemployment-benefits-than-when-they-were-employed-2020-05-26?mod=article_inline
20Concurrent Advisors
By the Numbers Concurrent Advisors is an advisor-owned, full-service
Founded 2016 partnership, bringing together elite independent
Offices 38 offices with a common vision of transforming the client
Retail AUM $7.2B
experience. With offices nationwide and clients
Institutional AUA $8B
Revenue $66mm globally.
Advisors 94
For Press or to connect with Concurrent please contact:
Neelab Naibkhyl, CRPS
Director, Concurrent Advisors
Financial Advisor, RJFS
t: 858.924.8423
a: 12651 High Bluff Drive, Suite 250 San Diego, CA 92130
e: neelab@concurrentadvisors.com
21Disclosures
Data provided by Morningstar, Bloomberg, Factset.
Securities offered through Raymond James Financial Services, Inc. Member FINRA/SIPC
Investment advisory services offered through Raymond James Financial Services Advisors, Inc. Concurrent Advisors is not a registered broker/dealer and independent from Raymond James Financial Inc.
This material is for informational purposes only and should not be used or construed as a recommendation regarding any security outside of a managed account.
The information contained in this report does not purport to be a complete description of the securities, markets, or developments referred to in this material. The information has been obtained from sources
considered to be reliable, but we do not guarantee that the foregoing material is accurate or complete. Any opinions are those of Eddy Augsten and not necessarily those of Raymond James. Investing involves risk
and you may incur a profit or loss regardless of strategy selected. Investing in the energy sector involves special risks, including the potential adverse effects of state and federal regulation and may not be suitable
for all investors. Inclusion of these indexes is for illustrative purposes only. Keep in mind that individuals cannot invest directly in any index, and index performance does not include transaction costs or other fees,
which will affect actual investment performance. Individual investor's results will vary.
There is no assurance that any investment strategy will be successful or that any securities transaction, holdings, sectors or allocations discussed will be profitable. It should not be assumed that any investment
recommendation made in the future will be profitable or equal any investment performance discussed herein. Please note all indices are unmanaged and investors cannot invest directly in an index. An investor
who purchases an investment product that attempts to mimic performance of an index will incur expenses that would reduce returns. Past performance is not indicative of future results. The performance noted in
this presentation does not include fees and costs, which would reduce investor’s returns.
Keep in mind that individuals cannot invest directly in any index, and index performance does not include transaction costs or other fees, which will affect actual investment performance. Individual investor's
results will vary. Past performance does not guarantee future results.
Index returns do not reflect the deductions of fees, trading costs or other expenses. The Index is referred to for informational purposes only: the composition of each Index is different from the composition of the
accounts managed by the investment manager. Investors may not make direct investments into any index. Past performance may not be indicative of future results.
Inclusion of these indexes is for illustrative purposes only.
Certain investments may not be readily sold as desired. There could be considerable fluctuation in time and/or price for subsequent trades if there is not a strong market at the time of your order.
Small and mid-cap securities generally involve greater risks and are not suitable for all investors.
International investing involves additional risks such as currency fluctuations, differing financial accounting standards, and possible political and economic instability. These risks are greater in emerging markets.
The value of real estate investments may be adversely affected by several factors, including supply and demand, rising interest rates, property taxes, and changes in the national, state and local economic climate.
Commodities are volatile investments and should only form a small part of a diversified portfolio. There may be sharp price fluctuations even during periods when prices overall are rising.
Google Trends is a trademark of Google Inc.
22Index Descriptions
Asset class and reference benchmarks: Barclays High Yield: Covers the universe of fixed-rate, non-investment grade debt. Pay-in-kind (PIK)
bonds, Eurobonds, and debt issues from countries designated as emerging markets (e.g., Argentina,
ASSET CLASS BENCHMARK Brazil, Venezuela, etc.) are excluded, but Canadian and global bonds (SEC-registered) of issuers in non-
U.S. Equity Russell 3000 TR EMG countries are included. Original issue zeroes, step-up coupon structures and 144-As are also
Non-U.S. Equity MSCI ACWI ex US NR included.
U.S. Fixed Income Barclays U.S. Aggregate Bond TR
Global Real Estate (prior to 2008) NASDAQ Global Real Estate NR Barclays U.S. Corporate High Yield: Composed of fixed-rate, publicly issued, non-investment grade
Global Real Estate (2008-present) FTSE EPRA/NAREIT Global Real Estate NR debt.
Commodities Bloomberg Commodity TR USD
Cash & Cash Alternatives Citi Treasury Bill 3 Mon USD Citi 3-Month Treasury-Bill Index: This is an unmanaged index of three-month Treasury bills.
Alerian MLP (TR): The Alerian MLP Index is the leading gauge of large- and mid-cap energy Master Limited FTSE EPRA/NAREIT Global Real Estate Index : Designed to represent general trends in eligible listed
Partnerships (MLPs). The float-adjusted, capitalization-weighted index, which includes 50 prominent real estate stocks worldwide. Relevant real estate activities are defined as the ownership, trading and
companies and captures approximately 75% of available market capitalization, is disseminated real-time on development of income producing real estate.
a total-return basis.
Global Financial Data: Index data has calculated for world ex US indices back to 1919. Since the
Bloomberg Commodity Total Return Index: Formerly the Dow Jones-UBS Commodity Index TR (DJUBSTR),is Morgan Stanley World index was not calculated before 1970, an index has been put
composed of futures contracts and reflects the returns on a fully collateralized investment in the BCOM. together to simulate how a World Index would have performed had it been calculated back to 1919.
This combines the returns of the BCOM with the returns on cash collateral invested in 3 Month U.S. From 1970 on, the indices are capitalization weighted and include the same
Treasury countries as are now included in the MSCI World Index.
Bills.
MSCI All Country World Index Ex-U.S Index.: A market-capitalization-weighted index maintained by
Barclays 10-Year Municipal: A rules-based, market-value weighted index engineered for the long-term tax- Morgan Stanley Capital International (MSCI) and designed to provide a broad
exempt bond market. This index is the 10 year (8-12) measure of stock performance throughout the world, with the exception of U.S.-based companies. It
component of the Municipal Bond Index. includes both developed and emerging markets.
Barclays 10-Year U.S. Treasuries: Measures the performance of U.S. Treasury securities that have a MSCI EAFE Index (Europe, Australasia, Far East): A free-float adjusted market capitalization index that
remaining maturity of 10 years. is designed to measure developed market equity performance, excluding the
United States and Canada. The EAFE consists of the country indices of 21 developed nations.
Barclays U.S. Aggregate Index: Represents securities that are SEC-registered, taxable, and dollar
denominated. The index covers the U.S. investment-grade fixed rate bond market, with index components MSCI EAFE Growth Index: Represents approximately 50% of the free-float adjusted market
for government and corporate securities, mortgage pass-through securities, and asset-backed securities. capitalization of the MSCI EAFE index, and consists of those securities classified by MSCI
as most representing the growth style.
Barclays Global Aggregate ex-U.S. Dollar Bond Index: Tracks an international basket of bonds that currently
contains 65% government, 14% corporate, 13% agency and 8% mortgage-related bonds. MSCI EAFE Small-Cap Index: An unmanaged, market-weighted index of small companies in developed
markets, excluding the U.S. and Canada.
23Index Descriptions (Cont.)
MSCI EAFE Value: Represents approximately 50% of the free-float adjusted market capitalization of the Russell 2000 Value Index: Measures the performance of those Russell 2000 companies with lower price-to-book
MSCI EAFE index, and consists of those securities classified by MSCI as most ratios and lower forecasted growth values
representing the value style.
Russell 2000 Growth Index: Measures the performance of those Russell 2000 companies with higher price-to-
MSCI Emerging Markets Index: Designed to measure equity market performance in 25 emerging book ratios and higher forecasted growth values.
market indexes. The three largest industries are materials, energy and banks.
Russell 3000 Index: measures the performance of the 3,000 largest U.S. companies based on total market
MSCI Local Currency Index: A special currency perspective that approximates the return of an index as capitalization, which represents 98% of the investable U.S. equity market.
if there were no currency valuation changes from one day to the next.
Standard & Poor’s 500 (S&P 500): Measures changes in stock market conditions based on the average
NASDAQ Global Real Estate Index: The index measures the performance of real estate stocks which performance of 500 widely held common stocks. Represents
listed on an Index Eligible Global Stock Exchange. The index is market capitalization approximately 68% of the investable U.S. equity market.
weighted.
S&P 500 Consumer Discretionary: Comprises those companies included in the S&P 500 that are classified as
Russell 1000 Index: Measures the performance of the 1,000 largest companies in the Russell 3000 members of the GICS® consumer discretionary sector.
Index, which represents approximately 90% of the investible U.S. equity market.
S&P 500 Consumer Staples: Comprises those companies included in the S&P 500 that are classified as members
Russell 1000 Value Index: Measures the performance of those Russell 1000 companies with lower of the GICS® consumer staples sector.
price-to-book ratios and lower forecasted growth values.
S&P 500 Energy: Comprises those companies included in the S&P 500 that are classified as members of the
Russell 1000 Growth Index: Measures the performance of those Russell 1000 companies with higher GICS® energy sector.
price-to-book ratios and higher forecasted growth values.
S&P 500 Financials: Comprises those companies included in the S&P 500 that are classified as members of the
Russell Mid-Cap Index: Measures the performance of the 800 smallest companies of the Russell 1000 GICS® financials sector
Index, which represent approximately 30% of the total market capitalization of
the Russell 1000 Index. S&P 500 Health Care: Comprises those companies included in the S&P 500 that are classified as members of the
GICS® health care sector.
Russell Mid-cap Value Index: Measures the performance of those Russell Mid-cap companies with
lower price-to-book ratios and lower forecasted growth values. S&P 500 Industrials: Comprises those companies included in the S&P 500 that are classified as members of the
GICS® industrials sector.
Russell Mid-Cap Growth Index: Measures the performance of those Russell Mid-cap companies with
higher price-to-book ratios and higher forecasted growth values. S&P 500 Information Technology: Comprises those companies included in the S&P 500 that are classified as
members of the GICS® information technology sector.
Russell 2000 Index: Measures the performance of the 2,000 smallest companies in the Russell 3000
Index, which represent approximately 8% of the total market capitalization of the S&P 500 Materials: Comprises those companies included in the S&P 500 that are classified as members of the
Russell 3000 Index. GICS® materials sector.
.
24Index Descriptions (Cont.)
S&P 500 Telecom Services: Comprises those companies included in the S&P 500 that are classified as
members of the GICS® telecommunication services sector.
S&P 500 Utilities: Comprises those companies included in the S&P 500 that are classified as members
of the GICS® utilities sector.
S&P Mid Cap 400 (S&P 400): Provides investors with a benchmark for mid – cap companies. The index,
which is distinct from the large-cap S&P 500, measures the performance of mid-cap companies,
reflecting distinctive risk and return characteristics of this market segment.
S&P Small Cap 600 (S&P 600): Provides investors with a benchmark for small – cap companies. The
index, which is distinct from the large-cap S&P 500, measures the performance of small-cap companies,
reflecting distinctive risk and return characteristics of this market segment.
VIX is the Chicago Board Options Exchange (CBOE) Volatility Index, which shows the market's
expectation of 30-day volatility. It is constructed using the implied
volatilities of a wide range of S&P 500 index options. It is a widely used measure of market risk.
25You can also read


