BANKER - C. SCOTT WILLIAMS In Memoriam - PageTurnPro
←
→
Page content transcription
If your browser does not render page correctly, please read the page content below

BANKER
THE OHIO COMMUNITY

The Official Publication of the Community Bankers Association of Ohio                        Fourth Quarter 2018

                                                                        In Memoriam
                                                             C. SCOTT WILLIAMS
                                                                   JULY 12, 1938 - AUGUST 27, 2018

                                                                        www.cbao.com | The Ohio Community Banker   1
ARCHITECTURE
                           + DESIGN

                                                                          Union Bank Operations Center - Columbus Grove, OH

Richwood Bank - Richwood, OH

K4 believes in designing and creating environments in which banks
can succeed and thrive. We believe it is possible to design your space
to attract both younger and older generations.

We believe you can integrate technology while still preserving the
traditional core values and legacy of your institution. We believe that
people still value personal relationships. We believe in brand
consistency and balance. We believe in the future of the bank             Citizens National Bank - Defiance, OH

branch and in the Ohio Banking community.

Whether you need a new facility, an interior remodel, or a graphics
refresh; we provide appropriate design solutions for where and when
you need them. We are proud to share our financial portfolio and
have completed over 2,000 financial projects in the last 18 years.

Contact us today, we look forward to building a relationship with you.

                     Look for K4 at the 2019 CBAO
                         Annual Convention.
                                                                          First Financial Bank - Madeira, OH

    2       The Ohio Community Banker | Fourth Quarter 2018
Contents                                                                                                                            Fourth Quarter 2018

                                                                                    FEATURES
                                                                                    06 Remembering C. Scott Williams
                                                                                    25 2018 CBAO Chairman Farewell
                                                                                    29 2019 Dates To Remember

                                                                                    COLUMNS
                                                                                    05 Industry Update - Thanks Scott...
                                                                                    09 Community Banking Briefs
                                                                       6            17 Community Banking: One at a time
                                                                                          – Community Banks Make the Difference

                                                                                    36 From the ICBA Chairman
                                                                                    37 From the ICBA President

                                                                                    LEGISLATIVE REPORT CARDS
                                                                                    13 State Legislative Report Cards
                                                                                    14 Federal Legislative Report Cards

                                                                                    CONTRIBUTED ARTICLES
                                                                    42              22 A Bank’s Most Important Asset is Not on the
                                                                                          Balance Sheet!

                                                                                    27 Risk Management Among Top 3 Skills for Sought-
                                                                                          After CFOs

                                                                                    30 Leveraging Customer Data for Growth
                                                                                    32 Rethinking CECL – Innovative Insights to Drive
                                                                                          Business, Not Just Your Reserve.

                                                                                    34 BOLI—Time for a Re-Look?
                                                                                    39 Avoid Being Caught Off Guard by SBA Policies
                                                                                    42 How Banks can Improve The Customer
                                                                    25                    Experience in 2019

With the exception of official announcements, Community Bankers Association of Ohio (CBAO) and its staff disclaim responsibility for opinions expressed and
statements made in articles published in the Ohio Community Banker. This publication and other CBAO programs are intended and designed to provide accurate
and authoritative information regarding the subject matter covered. These services are provided with the understanding that CBAO is not engaged in rendering legal,
accounting, or other professional services. If legal advice or other expert assistance is required, the services of a competent professional should be sought.

                                                                                                          www.cbao.com | The Ohio Community Banker                3
CBAO Officers        CBAO Region Directors and Directors at Large
                   Chairman Kate Fischer – President & CEO, Metamora State Bank           Region 1 Ben Babcanec – SVP / Head of Retail Administration, Heartland Bank
      1st Vice Chairman Charlie Cecil – President / CEO / Director, First City Bank       Region 2 Kent James – President & Chief Executive Officer, Greenville National Bank
               2nd Vice Chairman Scott McComb – President & CEO, Heartland Bank           Region 3 Tracey Craig – President & CEO, Woodsfield Savings Bank
                                Secretary Robert L. Palmer – President & CEO, CBAO        Region 4 Alicia Freeman – President / CEO, The Peoples Bank
                                                                                          ICBA Federal Delegate Scott McComb – Chairman, President & CEO, Heartland Bank
                                                                         CBAO Staff       Donn Schafer – President & CEO, The Settlers Bank
                             President & CEO Robert L. Palmer, rlpalmer@cbao.com          Leo Miller – President & Chief Executive Officer, The Apple Creek Banking Company
                                    COO Aza H. Bittinger Jr., ahbittinger@cbao.com        Mike Monnier – CEO, Osgood State Bank
    Education and Special Events Coordinator Lianne Simeone, lsimeone@cbao.com            Tom Caldwell – President & CEO, The Middlefield Banking Company
          Marketing & Digital Design Coordinator Susan Houser, shouser@cbao.com           Scott McComb – President & CEO, Heartland Bank
                           Administrative Coordinator Patti Webb, pwebb@cbao.com
                                                                                          CBAO Past Chairman
                                            Legislative & Regulatory Committee            Chad Hoffman – President & CEO, Richwood Bank
                                                             Chairman Mike Monnier        Mickey C. Schwarzbek – President & CEO, The Sherwood State Bank
                               Executive Agency Lobbyist/Secretary Robert L. Palmer       Ralph Lober – President & CEO, Consumers National Bank
                                                        CBAO COO Aza H. Bittinger Jr.
                                                         CBAO Chairman Kate Fischer       Executive Committee
                                                  CBAO Past Chairman Chad Hoffman         Chairman Kate Fischer
                                         CBAO Past Chairman Mickey C. Schwarzbek          President & CEO, Secretary   Robert L. Palmer
                                                    CBAO Past Chairman Ralph Lober        Charlie Cecil
                                                                       Diane Hoops        Scott McComb
                                                                       Brian Gehres       Chad Hoffman
                                                               James (Tony) Gorrell       Mickey Schwarzbek
                                                                       Eric Faulkner      Ralph Lober
                                                                     Alicia Freeman
                                                                    Donn R. Schafer       Education & Training Committee
                                                                        Tracey Craig      Chairman Alicia Freeman
                                                                         Jeff Kessler     CBAO President & CEO Robert L. Palmer
                                                                         Kent James       CBAO COO Aza H. Bittinger Jr.
                                                                      Tom Caldwell        CBAO Past Chairman Chad Hoffman
                                                                           Leo Miller     CBAO Past Chairman Mickey C. Schwarzbek
                                                                                          CBAO Past Chairman Ralph J. Lober II
                                 CBAO Service Corporation Board of Directors              CBAO Chairman Kate Fischer
                                                           Chairman Kate Fischer          1st Vice Chairman Charles C. Cecil
                                         CBAO President & CEO Robert L. Palmer            Secretary Lianne Simeone
                                        CBAO COO / Secretary Aza H. Bittinger Jr.         Diane Hoops
                                                       Treasurer Vacant Position          Frances Samson
                                                                  Charles C. Cecil        Rachel Weaver
                                     CBAO Product & Service Advisor Tim Chapman           Lisa Keeney
                                                                                          Timothy Coan
                                                 CBAO Service Corporation Staff           Alissa Schierberl
                     CBAO President & CEO Robert L. Palmer, rlpalmer@cbao.com             Donn Schafer
                           CBAO COO Aza H. Bittinger Jr., ahbittinger@cbao.com            Kent James
              CBAO Product & Service Advisor Tim Chapman, tchapman@cbao.com               Tom Caldwell
                                                                                          Leo Miller
                                               CBAO Insurance Agency Inc. Staff
                     CBAO President & CEO Robert L. Palmer, rlpalmer@cbao.com             CBAO Insurance Agency, Inc. Board of Directors
                           CBAO COO Aza H. Bittinger Jr., ahbittinger@cbao.com            Chairman Chad Hoffman
              CBAO Product & Service Advisor Tim Chapman, tchapman@cbao.com               CBAO President & CEO Robert L. Palmer
                                                                                          CBAO COO Aza H. Bittinger Jr.
                                                                                          CBAO Product & Service Advisor Tim Chapman

                                            ICBA Federal Delegate Scott McComb - Chairman, President & CEO, Heartland Bank
                                             Legal Counsel H. Grant Stephenson, Partner, Porter, Wright, Morris & Arthur LLP
                                Executive Agency Lobbyist Robert L. Palmer, President & CEO, Community Bankers Association of Ohio
                            Financial and Insurance Services Consultant James L. Harvin, Managing Director, JLH Associates LLC: 517.351.4158
             Community Bank Stock Consultant Greig McDonald, President, Community Banc Investments, Community Bank Stock: Hotline:                    800.224.1013

                               Community Bankers Association of Ohio l 8800 Lyra Drive, Suite 570 l Columbus, Ohio 43240
                                                                  www.cbao.com

                                                        For advertising opportunities, contact CBAO at shouser@cbao.com.
                     To view advertising rates, visit www.cbao.com and click on Advertising Opportunities under the Publications tab on the navigation bar.

4   The Ohio Community Banker | Fourth Quarter 2018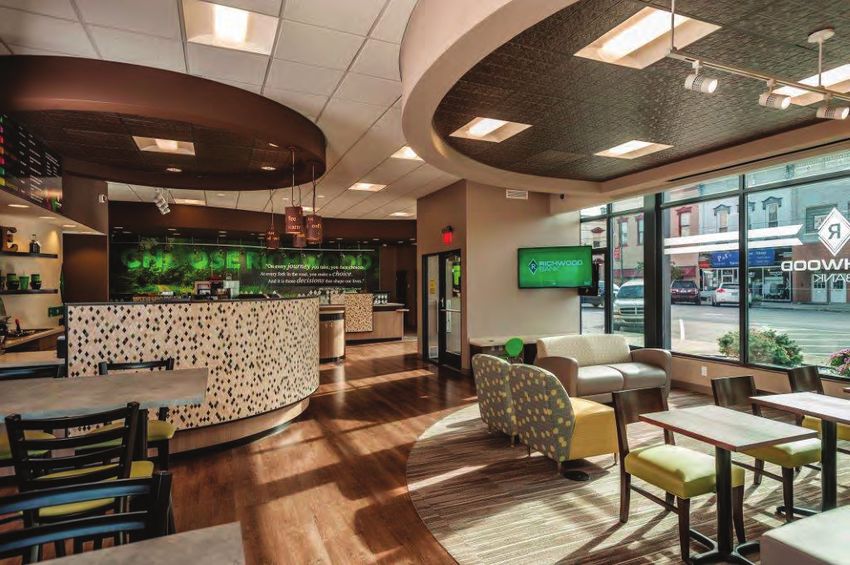
INDUSTRY UPDATE

THANKS SCOTT…
                            Most of you are probably aware of        So, first hand I can tell you that when Scott retired CBAO
                            the recent passing of Charles Scott      was in strong financial condition. Even today, 19+ years
                            Williams “Scott” at the age of 80. He    after his early retirement we still enjoy legacy revenues on
                            was the first Executive Director and a   programs that he created. He clearly understood the value of
                            founder of CBAO. What you may not        aggregating community banks not only as a collective voice for
                            be aware of is his lasting impact on     our industry’s issues but to negotiate discounts and service
                            Ohio’s community banking industry        enhancements that directly benefit the bottom line of every
                            and the industry as a whole.             community bank in Ohio regardless of asset size. He made
                                                                     CBAO one of the largest, financially sound, and most influential
                            For those of you who never had           state trade associations of the CCBAs while exclusively
                            the opportunity to work with or          representing the industry that he loved and served.
                            be personally acquainted with
                            Scott, I would like to share with you
                            some of my personal thoughts and
                            observations.
Robert L. Palmer
President and
Chief Executive Officer
                            My wife Mary and I first met
                            Scott and his wife Arlene in 1999
Community Bankers           while attending a meeting of
Association of Ohio
                            the Executive Council of State
rlpalmer@CBAO.com           Community Bankers Associations
(614) 846-2349              (CCBA). CCBA is an organization that
                            is comprised of state community
banking associations that exists for the exclusive benefit and
perpetuation of community banks in their respective states.
CBAO is a long-standing member of CCBA. Today in CCBA
there remains 25 state banking associations, down from
approximately 40, exclusively focused on community banks
and affiliated only with the Independent Community Bankers
of America (ICBA). Scott served as President (now Chairman) of
this organization in 1987.
                                                                     Scott was a relationship builder, a highly creative individual, a
When we were introduced I was serving as President and               strong negotiator, a visionary, and extremely passionate and
Chief Executive Officer of a De Novo community bank in West          committed to the success of community banks in Ohio and
Virginia and as the volunteer President of the West Virginia         across the country. He looked for ways to avoid confrontation
Community Bankers Association.                                       and had that great rare and unique quality of “ownership” for
                                                                     the organization which reflected in the many decisions that
I tell you this as Scott was the first person to welcome me
                                                                     he made. CBAO’s success today is due in large part to Scott as
to the meeting. While together for about three days Scott
                                                                     he gave us such a strong foundation to build from.
and I, Mary and Arlene, had the opportunity to have several
informal conversations about family, community banking,              The job of representing an industry isn’t an easy one. The
the value of community banks to their communities, and               same goes for the community banking industry. In the
the value of state associations like CBAO to their respective        position of Executive Director, you make many great friends,
state’s community banking industry.                                  build long-lasting professional relationships, and sadly create
                                                                     some enemies. Scott chose his battles wisely and when it was
Something must have “clicked” between us as we had these
                                                                     time to go to battle he never hesitated to lead the charge.
conversations. When the meeting ended and we all departed
for home we had an unscheduled reconnection in the airport           Scott remained a strong supporter of CBAO and advocate
in Charlotte, North Carolina. While having lunch there together      for our industry until his death. Our sincere condolences to
Scott offered this unsolicited statement to me. (paraphrased)        Arlene and his family.
“Because of your community banking experience and passion
for the community banking industry, you should strongly              Thanks, Scott! May God Bless You and this great industry
consider becoming a state trade association executive.”              called community banking!

I never really gave his comment another thought after that           Best Wishes,
day until late in 2000 when I learned through a professional
acquaintance that a Search Committee had been formed
to find a successor to Scott who was retiring early due to
personal illness. As they say, the rest is history. I was hired in
March 2001 as the second Executive Director of CBAO.

                                                                                      www.cbao.com | The Ohio Community Banker       5
Remembering
                                                 C. SCOTT WILLIAMS
                                                            JULY 12, 1938 - AUGUST 27, 2018
                                               In 1974, a man accepted a challenge to lead an organization that would
                                               provide community banks in Ohio with the necessary ammunition to
                                               compete with large regional and national banks. Along with three other
                                               community bankers, Scott Williams organized a small meeting of 12
                                               bankers from across Ohio, and the Community Bankers Association
                                               of Ohio was soon established. In March of 1980, he became the first
C. Scott Williams
                                               executive director of CBAO.
President and Executive Director
(1980-2000)                                    Scott Williams was an integral part of developing group purchasing
Community Bankers                              power, legislative lobbying, educational opportunities, the annual
Association of Ohio                            convention, regional meetings, a quarterly publication, and other
                                               valuable resources that remain vital to our association. He established
                                               a united voice for the industry, championing the unique values of
                                               community banking and the strength of joining together.

                                               We are deeply grateful for Scott Williams and the profound impact he
                                               had on our industry and association. He will always be remembered.

                                                                                                       d  o   n  t h e efforts
                                                                                                   se
                                                                  m   u n  it y   bank is ba                       eople are
                                                        “A com                                 n  d  t h e s  e  p
                                                              g r o u  p   o f people. A                       c o  m  m unity.
                                                         of a                                          t h e
                                                                                   in volved in                                y
                                                         more t    o   t a l l y
                                                                                                     b r in  g in  g industr
                                                                  a  r e   in   t erested in                         in  school
                                                          They                                        re  s t e d
                                                                                    u nity, inte
                                                          to the       c o  m    m
                                                                                                      t o r ,  t h e  Chamber
                                                                       s ,  t  h  e  public sec
                                                           activ it ie
                                                                                          t o t a l in  v olvement.”
                                                                              rce. It’s
                                                           of Comme
                                                                     t  W  il  li a m s, 1979
                                                            - Scot

6     The Ohio Community Banker | Fourth Quarter 2018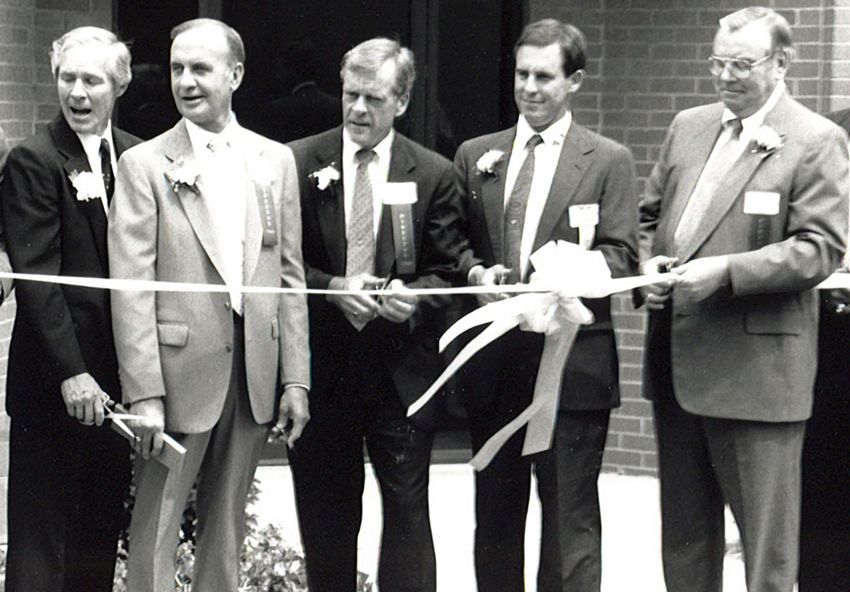
munity
e p it o m e of a com
“Scott was
th e hat it is
m a d e th e CBAO w
d
banker an
tod a y .”
on
Chuck Dix
President
/ CEO Company
S a v in g s and Loan
The Home
, Ohio
of Kenton
as
e t r uly w
h
and of its
e c t i ous 6 years CBAO,
s inf rst 2 for
s s i o n wa for the fi the trail dation
’s pa AO zing foun oice
W i l liam ice of CB d on bla ding the werful v le
tt o e il o b
“Sco ce and v as focus and bu nd the p remarka
e f a e w n c e n a d a
th . H resista tio an a
n
ence l ocia .”
exist g off al able ass great m dvocacy
i n k a a
fight is remar We lost Banking
h y. nity
for t ve toda
e h a C o mmu
w o r
eer f
pion
gs 1
H artin man 200 -2016 is set
Jac k a i r 1 5 d that
Ch n 20 sa p e r io gure or
CBAO hairma is d e fined a p r o m inent fi n era has
C “An er a m e ,a
ICBA
t y p ifi e d by so . For the CBAO ing feature
off or ure efin
c t e r is tic feat 20 years its d
chara over
and for ms.”
passed C. Scott Willia
en
has be
Era… ms”
d of an tt Willia cember 2000
“The En odbye to Sco ker, De
Saying
Go
m u n ity Ban
io Com
The Oh
www.cbao.com | The Ohio Community Banker 7
8 The Ohio Community Banker | Fourth Quarter 2018
COMMUNITY BANKING BRIEFS

OHIO SUPREME COURT: A GENERAL LIABILITY
POLICY DOES NOT COVER SUBCONTRACTOR’S
FAULTY WORKMANSHIP
                          Ohio bankers should be aware            So, what is a contractor to do? Additional insurance may
                          of a current significant change         not be the answer. Caution must be exercised in purchasing
                          in the legal environment                supplemental insurance that is intended to cover faulty
                          for their contractor clients:           work. In Charles Constr., the insured-contractor, in addition
                          commercial general liability            to its CGL policy, bought a products-completed operations-
                          (CGL) insurance probably does           hazard (PCOH) insurance policy to expressly cover faulty
                          not cover faulty workmanship            work performed by its subcontractor on the project. The
                          performed by contractor or its          Court, however, applying the same “known business risk”
                          subcontractors. Such claims could       standard, determined that, like the CGL policy, the PCOH
                          dramatically impact a contractor’s      policy was not triggered without an accidental occurrence.
                          creditworthiness.
                                                                  As a result of these decisions, there is a risk that faulty
                           Courts in many states have             workmanship is uninsured. Bankers should be sure to check
H. Grant Stephenson        concluded that CGL insurance           their client’s policies to determine whether the coverage
CBAO Legal Counsel         policies cover property damages        contractor has purchased includes the coverage contractor
Porter, Wright, Morris &   arising from faulty workmanship        need. And bankers should consider insisting upon an
Arthur LLP
                           unless such coverage was               endorsement rider to CGL insurance policy that redefines
                           specifically excluded from             an insurable occurrence to include coverage for faulty
                           the policy. However, the Ohio          workmanship and defective construction.
Supreme Court, in two recent decisions, has rejected that
approach. To insure against defective construction and            (Tom Nocar, a Senior Attorney and Ryan Sherman, a Partner
faulty workmanship in Ohio, a contractor must specifically        in the Columbus office of Porter Wright Morris & Arthur LLP,
include the coverage in its policy.                               contributed to this section of Bank Brief.)

Claims against an insured’s CGL policy are triggered by an        DOES YOUR WORKPLACE FOSTER A CULTURE OF SAFETY?
occurrence—when an accidental or fortuitous event has             NEW OSHA MEMO RELAXES RULE ON DRUG TESTING
occurred resulting in bodily injury and/or property damage.       POLICIES AND INCENTIVE PROGRAMS
Recently, however, the Ohio Supreme Court has determined
that faulty workmanship isn’t accidental or fortuitous.           In 2016 OSHA issued an anti-retaliation rule related to
                                                                  the reporting of illnesses and injuries. The rule prohibited
In 2012, the Court held that a claim filed by a contractor        employer retaliation against employees reporting workplace
under its CGL insurance policy for property damage caused         injuries and illnesses, and implementation of policies that
by the contractor’s own faulty workmanship was not an             discourage accurate reporting. At the time the rule was
occurrence such that the CGL policy would cover the loss. In      finalized, OSHA clearly indicated it would be interpreted
Westfield Ins. Co. v. Custom Agri Sys., Inc., the Court decided   strictly and would affect employer incentive programs and
that an occurrence must occur by accident or by chance.           post-accident drug testing policies.
The contractor’s own faulty work, the Court held, was not
accidental, but was instead a known business risk assumed         On Oct. 11, 2018, OSHA published a memorandum changing
by the contractor from the outset. Business risks are not         its position, taking a significantly more relaxed approach
covered under a CGL insurance policy.                             on this anti-retaliation rule. OSHA states that it “does not
                                                                  prohibit workplace safety incentive programs or post-
On Oct. 9, 2018, in Ohio N. Univ. v. Charles Constr. Servs.,      incident drug testing.”
the Supreme Court of Ohio extended its Custom Agri
precedent to subcontractor’s work declaring that any faulty       Under the Trump Administration, OSHA’s new position is
workmanship, whether performed by the contractor-insured          that actions related to safety-incentive programs or post-
or its subcontractors, is not an occurrence that would            accident drug testing are legitimate when taken to promote
trigger CGL insurance coverage. As a result, CGL policies in      workplace health and safety. The anti-retaliation rule is
Ohio generally do not insure against faulty workmanship or        violated only when employers penalize employees for
defective construction performed by the general contractor        reporting workplace injuries and illnesses.
or its subcontractors.
                                                                  (cont.)

                                                                                   www.cbao.com | The Ohio Community Banker      9
COMMUNITY BANKING BRIEFS (CONT.)
Incentive programs                                                  •   Testing unrelated to reporting of work-related injuries
                                                                        or illnesses
Under the previous interpretation, OSHA took issue
with incentive programs that conditioned rewards on                 •   Required drug testing under state workers’
low workplace safety incident rates, claiming that these                compensation laws or federal laws
programs actually deterred accurate reporting of illnesses
and injuries. Now, OSHA has revised its position and                •   Drug testing to investigate the cause of an accident that
provides examples of permissible incentive programs.                    harmed or could have harmed employees

First, incentive programs rewarding employees for reporting         Specifically regarding post-accident testing, while OSHA
hazards and near-misses encourage employee involvement              states that “all employees whose conduct could have
in a culture of safety. “Positive action” taken in regard to this   contributed to the incident, not just employees who
type of incentive program is always permissible according to        reported” should be tested.
OSHA.
                                                                    The new guidance from OSHA is generally good news for
The second type of incentive program addressed by OSHA is           employers.
rate-based— one that rewards employees for an injury-free
month or similar reduced rates. The anti-retaliation rule in        In short, OSHA’s relaxed stance on incentive programs and
the past considered these incentive programs improper.              post-accident drug testing may lead to less scrutinizing of
Conversely, OSHA now takes the position that these                  employers. However, employers should not completely
incentive programs are permissible so long as they “are not         ignore the original interpretation, as it provides good tips
implemented in a manner that discourages reporting.”                and may help foster a culture of safety in your workplace.
                                                                    Although rate-based incentive programs are permissible
How can you make certain your incentive program does                under the current administration, consider pairing a rate-
not discourage reporting?                                           based incentive with one that rewards active behaviors,
                                                                    such as reporting hazards. Though OSHA permits post-
Employers must have “adequate precautions” to ensure                accident drug testing, it is a good practice to only test when
employees feel free to report. Alone, a statement                   there is reason to believe the accident involved drugs or
encouraging employees to report, assuring that they will            alcohol.
not face retaliation, is unlikely to meet this burden. Further,
OSHA offers the following as suggestions for employers:             Beware: under-reporting could lead to under-recording

•    Create a work culture that supports and emphasizes             Finally, one aspect of the anti-retaliation rule not discussed
     safety over rates                                              was a concern for under-recording of injuries and illnesses.
                                                                    As a result, any incentive program encouraging under-
•    Implement incentive programs that reward employees             reporting could lead to under-recording, resulting in
     who report unsafe working conditions                           employer liability for inaccurate recordkeeping.

•    Use training program to reinforce reporting rights and         (Jourdan Day, an associate in the Columbus office of Porter
     responsibilities                                               Wright Morris & Arthur LLP, prepared this section of Bank
                                                                    Brief.)
•    Implement a mechanism to evaluate employees’
     willingness to report                                          IRS LETTER RULING GENERATES INTEREST IN EMPLOYER
                                                                    STUDENT LOAN BENEFIT PLANS, BUT BE AWARE OF
Post-Accident Drug Testing                                          TESTING AND OTHER ISSUES

Under the previous interpretation, OSHA considered                  The Internal Revenue Service (IRS) recently issued a private
automatic post-accident drug testing improper. It required          letter ruling, PLR 201833012 (PLR) that has generated
the policy to call for testing only where there was a               interest among employers about student loan benefit
“reasonable possibility” that drug use contributed to the           programs. An IRS official at a recent conference, however,
accident. Recently OSHA changed its position, stating “most         cautioned practitioners to read the PLR because the scope
instances of workplace drug testing are permissible” under          of the PLR is more narrow than what some headlines may
the anti-retaliation rule. These permissible instances of drug      have led people to believe. In particular, the PLR did not
testing include:                                                    allow employers to authorize distributions from 401(k) plans
                                                                    to allow employees to repay their student loans.
•    Random drug testing

10     The Ohio Community Banker | Fourth Quarter 2018
Instead, the PLR allowed an employer to make nonelective with administration of the loan program. Issues that
contributions to the company’s 401(k) plan on behalf of arise in student loan repayments include deferment, loan
employees who were paying off student loan debt. To receive forgiveness, payment restructuring and refinancing, and
that benefit, the employees were required to opt out of defaults. Is the employer confident that the administrator can
receiving the normal matching contribution. In other words, address these issues? Do the service provider agreements
the plan that was the subject of the PLR was quite unique. address these issues?
While it is encouraging to see the IRS support innovative plan
designs that provide a benefit that employees value, it is Safe harbor questions
important to understand what the PLR addressed and what
it did not address before employers create their own plans. Safe harbor 401(k) plans are not subject to the complex
Specifically, the PLR held only that this benefit did not violate nondiscrimination testing of traditional 401(k) plans. The
the contingent benefit rule. The PLR did not address other PLR did not address how a plan in which an employee opts
practical questions that employers will need to resolve before out of receiving matching contributions would work in the
implementing their own similar program. We describe these context of a safe harbor plan. Unless the IRS were to create
items below. an exception, an employer that sponsors a safe harbor plan
may need to structure its student loan benefit in a different
Non-discrimination issues way from the one that was subject to the PLR.
An employer has to show that the availability of the benefit Replacement vs. additional benefit
and the amount of the benefit being provided does not
disproportionately favor highly compensated employees. Somewhat related to the point above is that the plan at issue
Presumably, the workers who would be making student loan under the PLR essentially replaced matching contributions
repayments would be young and not highly compensated for another type of employer contribution. Employers may
employees. Depending on the industry, however, an want to consider whether to leave the matching contribution
employer could have a mix of highly compensated and non- allocation terms in their 401(k) plans unchanged and instead
highly compensated employees participating in this program. offer an additional nonelective contribution that is based on
Highly compensated employees have the ability to repay their student loan repayments.
student loans more quickly than non-highly compensated
employees and therefore potentially could receive more of
Our impression is that while the PLR has sparked interest
these non-elective contributions. The PLR did not explain
in a student loan benefit plan, until the IRS provides more
how coverage and nondiscrimination testing would apply or
guidance on these issues, employers remain hesitant to
whether exceptions could be made to the rules to prevent
implement this type of plan. Industry groups have begun
student loan repayment contributions from causing plan
asking the IRS to provide this guidance. The ERISA Industry
testing failures.
Committee has already asked the IRS to issue a more
generally applicable revenue ruling to provide employers the
Substantiation confidence to implement similar programs. Once we have
guidance, this type of feature could be a great way to attract
Another question the PLR did not address is whether an younger employees, but for now, it may still be premature.
employer must verify that the employees actually repaid their
student loans, and if so, how extensive are the substantiation (Greg Daugherty and Seth Hanft, partners in the Columbus office
requirements. Would asking the employees to provide of Porter Wright Morris & Arthur LLP, prepared this section of
copies of bank statements be sufficient? Alternatively, should Bank Brief.)
employers require direct proof of payment from student
loan providers or arrange for direct payment of student loan
NEW TAX CREDIT REWARDS COMPANIES THAT OFFER
payments through an employer’s payroll system? Those last
PAID FMLA LEAVE IN 2018 AND 2019
two approaches could be quite burdensome.
The federal Tax Cuts and Jobs Act of 2017 contains an often-
Refinancing
overlooked tax credit for employers that provide qualifying
types of paid leave to their full- and part-time employees. The
The PLR did not address whether a plan could make a credit is available to any employer, regardless of size, if:
student loan repayment contribution conditional upon an
employee refinancing his or her existing student loans.
• The employer provides at least 2 weeks of paid family
and medical leave annually for employees who have
Administration been with the company for at least 12 months
Employers may decide that because of the issues described (cont.)
above, they will want a third party administrator to assist
www.cbao.com | The Ohio Community Banker 11COMMUNITY BANKING BRIEFS (CONT.)
• The paid leave is at least 50 percent of the wages employees. The policy may not exclude any classification of
normally paid to the employee employees (for example, collectively bargained employees)
if they are qualifying employees.
The IRS has issued a set of frequently asked questions and a
notice to help employers understand the tax credit, which is • Effective date of policy
only available for wages paid in 2018 and 2019. The notice,
entitled Notice 2018-71, is effective as of Sept. 24, 2018, and Generally, the employer’s written policy must be “in place”
similarly only applies to wages paid in 2018 and 2019. Here before the paid family and medical leave for which the
are some of its highlights: employer claims the credit is taken. The written policy
is considered to be “in place” on the later of the policy’s
• Calculating and claiming the credit adoption date or the policy’s effective date. Additionally,
eligible employers who establish a qualifying paid leave
For an employer that offers paid leave in the amount of program or amend an existing program by Dec. 31, 2018
50 percent of an employee’s wages, the tax credit is 12.5 will be eligible to claim the tax credit retroactively to the
percent of the amount paid. The credit is increased by 0.25 beginning of the employer’s 2018 tax year for qualifying
percent for each percentage point by which the paid leave leave already provided.
exceeds 50 percent of the employee’s normal wages, but it
is capped at a maximum credit of 25 percent. • Family and medical leave
• Eligible employer Paid leave made available to an employee qualifies as
“family and medical leave” under the tax credit only if
An employer does not have to be subject to the Family the leave is specifically designated for one or more FMLA
and Medical Leave Act (FMLA) to take advantage of the tax purposes, is not to be used for any other reason, and is not
credit. Any employer will be eligible for the credit if it has a paid by a state or local government or required by state or
written policy in place that provides paid family and medical local law. If an employer provides paid leave as vacation
leave, satisfies the minimum paid leave requirements, and, leave, personal leave, or medical or sick leave (other than
if applicable, includes certain required “non-interference” leave specifically for one or more of the FMLA purposes),
language. The employer must include this “non- that paid leave is not considered family and medical leave
interference” language in its written policy if it employs at under the tax credit. However, paid leave provided under
least one qualifying employee who is not covered by Title an employee’s short-term disability program may qualify as
I of the FMLA. The “non-interference” language must state family and medical leave under the tax credit if it otherwise
that the employer will not interfere with, restrain, or deny meets the requirements to be family and medical leave
the exercise or attempted exercise of any right provided under the tax credit.
under the paid leave policy, and will not discharge or
discriminate against any individual for opposing any practice Bottom Line
prohibited by the policy.
In addition to the provisions listed above, the notice
• Qualifying employee announces that the Treasury Department and the IRS
intend to publish proposed regulations on the tax credit
A qualifying employee is an employee who has been in the future. Until that time, however, employers who
employed by the employer for one year or more, and are considering implementing a paid leave policy should
who made less than $72,000 in compensation in 2017. familiarize themselves with this tax credit and analyze how
Until further guidance is issued, an employer may use any the credit might impact their decision. Because the tax
reasonable method to determine whether an employee credit is available only for wages paid in 2018 and 2019,
has been employed for one year or more. However, any employers should consult their attorneys and/or financial
requirement that an employee work 12 consecutive months advisors to determine whether instituting a paid leave policy
to be a qualifying employee will not constitute a reasonable merely to claim this credit is worth the cost.
method.
(Arslan Sheikh, an associate in the Columbus office of Porter
• Classifications of employees Wright Morris & Arthur LLP, prepared this section of Bank Brief.)
An employer’s written policy must provide at least 2 weeks © 2018 Porter Wright Morris & Arthur LLP. Portions of this Bank
of annual paid family and medical leave to all qualifying Brief may have appeared on bankingandfinancelawreport.com,
employees who are not part-time employees, and at the blog of the Banking and Finance Practice Group of Porter
least a proportionate amount of annual paid family and Wright Morris & Arthur, or in other publications of the firm.
medical leave to all qualifying employees who are part-time
12 The Ohio Community Banker | Fourth Quarter 2018LEGISLATIVE UPDATE
LEGISLATIVE REPORT CARDS
As part of our commitment to our community banks, CBAO is actively engaged in the legislative and regulatory activities at the State and
Federal level. Visit our Industry Representation page at cbao.com to keep updated on the activities that affect you.
STATE LEGISLATIVE REPORT CARD – HOUSE
PRIMARY CBAO EFFECTIVE
BILL DESCRIPTION House Senate
SPONSOR POSITION DATE
HB 49 Smith, R. 2018-2019 Ohio Operating Budget Yes Yes Monitor June 29, 2017
HB 52 Rezabek, J. Solicitation of Deeds Bill Yes Yes NEUTRAL May 11, 2018
HB 67 Young, R. Confessions of Judgement/Cognovit Clause Bill --- --- OPPOSE
Patton, T.
HB 106 Regulation of Nonbank ATM Bill --- --- Monitor
Patmon, B.
Koehler, K.
HB 123 Modify Short-term Loan Act Yes Yes NEUTRAL October 29, 2018
Ashford, M.
Sub HB 182 Seitz, B. Address Debt Adjusting Yes --- Monitor
HB 187 Dever, J. Job Applicants Information Bill --- --- Monitor
HB 199 III, Blessing, L. Enact Ohio Residential Mortgage Lending Act Yes Yes NEUTRAL March 23, 2018
Sub HB 213 Dever, J. Appraisal Law and Appraisal Management Bill Yes Yes Monitor December 14, 2018
HB 282 Hambley, S. Prohibit criminal mischief against residential rental property --- --- Monitor
Exempt loop credit and reward cards from Unclaimed Funds
Sub HB 353 Reineke, B. Yes Yes SUPPORT January 22, 2019
Law
Henne, M.
HB 386 Credit Agencies Fees Freeze Yes --- Monitor
Kelly, B.
Lipps, S.
HB 482 Nuisance Properties --- --- Monitor
Miller, A.
Sub HB 489 Dever, J. Financial Institutions Yes --- SUPPORT March 18, 2019
HB 495 Seitz, W. --- --- Monitor
Medical Marijuana Payment Processing
SB 254 Terhar, L. --- --- Monitor
Lipps, S.
HB 569 Modify Sales Tax on business-related electronic services --- --- Monitor
Reineke, B.
Require credit agency to provide credit reports to
HB 769 Dever, J. --- --- Monitor
businesses
HB 770 Seitz, B. Revise Credit Union Laws --- --- Monitor
Sheehy, M.
HCR 7 Reinstate Glass-Steagall Act --- --- Monitor
Ramos, D.
www.cbao.com | The Ohio Community Banker 13STATE LEGISLATIVE REPORT CARD – SENATE
PRIMARY CBAO EFFECTIVE
BILL DESCRIPTION House Senate
SPONSOR POSITION DATE
SB 24 Terhar, L. Enact Consumer Installment Loan Act Yes Yes NEUTRAL September 12, 2017
Coley, B. --- Yes
SB 29 SUPPORT
Oelslager, S. Enact New Banking Law September 29, 2017
HB 35 SUPPORT
Hughes, J. --- ---
SB 38 Yuko, K. --- --- OPPOSE
Minimum Wage Bill
HB 86 Smith, K.; Craig, H. --- --- OPPOSE
SB 49 Williams, S. Job Applicant Felony Question Bill --- --- OPPOSE
SB 120 Eklund, J. Address Debt Adjusting --- --- Monitor
Sub SB 158 Wilson, S. Combat Elder Fraud Bill --- Yes SUPPORT March 18, 2019
Hackett, B.
SB 220 Safe Harbor Cybersecurity Program Bill Yes Yes NEUTRAL November 02, 2018
Bacon, K.
SB 261 Tavares, C. Establish family and medical leave insurance benefits --- --- Monitor
Huffman, M.
SB 263 Enact Notary Public Modernization Act --- Yes SUPPORT March 18, 2019
Wilson, S.
Conduct performance audit of Medical Marijuana Control
SB 264 Coley, B. --- --- Monitor
Program
SB 292 Terhar, L. Allow credit unions to serve as public depositories --- --- OPPOSE
SCR 7 Skindell, M. Reinstate Glass-Steagall Act --- --- Monitor
FEDERAL LEGISLATIVE REPORT CARD – HOUSE
PRIMARY CBAO EFFECTIVE
BILL DESCRIPTION House Senate
SPONSOR POSITION DATE
H.R. 1 Brady, K. Tax Cuts and Jobs Act Yes Yes Monitor December 22, 2017
H.R. 2 Conaway, M. Agriculture and Nutrition Act of 2018 aka Farm Bill Yes Yes SUPPORT
December 20, 2018
S. 3042 Roberts, P. Agriculture Improvement Act of 2018 --- Yes SUPPORT
H.R. 10 Hensarling, J. Financial CHOICE Act of 2017 Yes --- SUPPORT
H.R. 24 Massie, T. Monitor
Federal Reserve Transparency Act of 2017 --- ---
S. 16 Paul, R. Monitor
H.R. 389 Royce, E Amend Credit Union Member Business Loan Bill --- --- OPPOSE
---
H.R. 402 Cohen, S. Fair Access to Credit Report Scores Act of 2017 --- Monitor
H.R. 493 Capuano, M. Subsidy Reserve Act of 2017 --- --- Monitor
H.R. 517 Ellison, K. Ensure Fair Prices in Title Insurance Act of 2017 --- --- Monitor
FHLB Community Development Financial Institutions
H.R. 704 Ellison, K. --- --- Monitor
Expansion Bill
H.R. 864 Love, M. Stop Debt Collection Abuse Act of 2017 --- --- Monitor
H.R. 924 Rothfus, K. Financial Institutions Due Process Act of 2017 --- --- SUPPORT
H.R. 1153 Huizenga, B. Amend Truth in Lending Act Bill Yes --- SUPPORT
(cont.)
14 The Ohio Community Banker | Fourth Quarter 2018FEDERAL LEGISLATIVE REPORT CARD – HOUSE (CONT.)
PRIMARY CBAO EFFECTIVE
BILL DESCRIPTION House Senate
SPONSOR POSITION DATE
H.R. 1244 King, P. Capital Access for Credit Unions --- --- OPPOSE
H.R. 1264 Williams, R. CFPB Exemption for Community Financial Institutions Bill --- --- SUPPORT
H.R. 1457 Tipton, S MOBILE Act of 2017 Yes --- SUPPORT
H.R. 1696 Reichert, D. --- --- SUPPORT
S Corporation Modernization Act of 2017
S. 711 Thune, J. --- --- SUPPORT
H.R. 2133 Luetkemeyer, B. SUPPORT
The CLEARR Act of 2017 --- ---
S. 1002 Moran, J. SUPPORT
H.R. 2148 Pittenger, R. Clarifying Commercial Real Estate Loans Yes --- SUPPORT
H.R. 2204 Hultgren, R. Homeowner Information Privacy Protection Act (HMDA) --- --- Monitor
H.R. 2215 Perlmutter, E. --- --- Monitor
SAFE Act of 2017
S. 1152 Merkley, J. --- --- Monitor
H.R. 2339 Marchant, K. Capital Access for Small Business Banks Act --- --- SUPPORT
H.R. 2396 Trott, D. Privacy Notification Technical Clarification Act Yes --- SUPPORT
H.R. 2403 Moore, G. --- --- SUPPORT
Reciprocal Deposits/Non-Brokered Deposits Bill
S. 1500 Warner, M. --- --- SUPPORT
H.R. 2874 Duffy, S. Yes --- SUPPORT
H.R. 1422 Ross, D. --- --- Monitor
H.R. 1558 Royce, E. --- --- Monitor
H.R. 2246 Luetkemeyer, B. --- --- Monitor
21st Century Flood Reform Act
H.R. 2565 Luetkemeyer, B. --- --- Monitor
H.R. 2868 Zeldin, L. --- --- Monitor
H.R. 2875 Velazquez, N. --- --- Monitor
H Res 616 Byrne, B. Yes --- SUPPORT
H.R. 2706 Luetkemeyer, B. Financial Institution Customer Protection Act of 2017 Yes --- SUPPORT
H.R. 2948 Stivers, S. --- --- Monitor
Amend S.A.F.E. Mortgage Licensing Act of 2008
S. 1753 Heller, D. --- --- Monitor
H.R. 2954 Emmer, T. Yes --- SUPPORT
Amend HMDA Act of 1975
H.R. 3354 Calvert, K. Yes --- SUPPORT
H.R. 3221 Kustoff, D. Securing Access to Affordable Mortgages Act --- --- Monitor
H.R. 3299 McHenry, P. Yes --- SUPPORT
Protecting Consumers’ Access to Credit Act of 2017
S. 1642 Warner, M. --- --- Monitor
H.R. 3971 Tenney, C. Community Institution Mortgage Relief Act of 2017 Yes --- SUPPORT
H.R. 3978 Hill, J. French TRID Improvement Act of 2017 Yes --- SUPPORT
H.R. 4464 Posey, B. Common Sense Credit Union Capital Relief Act of 2017 --- --- OPPOSE
H.R. 4545 Tipton, S. Financial Institutions Examination Fairness and Reform Act Yes --- SUPPORT
H.R. 4607 Loudermilk, B. Comprehensive Regulatory Review Act Yes --- SUPPORT
H.R. 4648 Emmer, T. Home Mortgage Reporting Relief Act of 2017 --- --- Monitor
H.R. 4771 Love, M. Yes --- SUPPORT
Small Bank Holding Company Relief Act of 2018
H.R. 1948 Love, M. --- --- Monitor
H.R. 4790 Hill, F. Volcker Rule Regulatory Harmonization Act Yes --- Monitor
H.R. 5534 Duffy, S. --- --- Monitor
GUIDE Compliance Act
S. 3443 Hatch, O. --- --- Monitor
H.R. 6199 Jenkins, L. Modernizing Health Savings Accounts Act of 2018 Yes --- SUPPORT
(cont.)
www.cbao.com | The Ohio Community Banker 15FEDERAL LEGISLATIVE REPORT CARD – HOUSE (CONT.)
PRIMARY CBAO EFFECTIVE
BILL DESCRIPTION House Senate
SPONSOR POSITION DATE
H.R. 6311 Roskam, P. Expanding Health Savings Accounts Act of 2018 Yes --- SUPPORT
National Flood Insurance Program Extension and Enhanced
H.R. 6402 Royce, E. --- --- Monitor
Consumer and Community Protections Act of 2018
H.R. 6741 Barr, A. Federal Reserve Reform Act of 2018 --- --- Monitor
H.R. 6743 Luetkemeyer, B. Consumer Information Notification Requirement Act --- --- Monitor
H.R. 6746 Hensarling, J. Protecting American Taxpayers and Homeowners Act of 2018 --- --- Monitor
H.R. 6972 Waters, M. Consumers First Act --- --- OPPOSE
H.J. Res 62 Graves, T. --- --- Monitor
CFPB Prepaid Accounts Rule Disapproval
S.J. Res 19 Perdue, D. --- --- Monitor
H.J. Res 111 Rothfus, K. Disapproval of CFPB Arbitration Rule Yes Yes SUPPORT November 01, 2017
FEDERAL LEGISLATIVE REPORT CARD – SENATE
CBAO EFFECTIVE
BILL SPONSOR DESCRIPTION House Senate
POSITION DATE
S. 105 Fischer, D. CFPB 5-Member Board of Directors Bill --- --- SUPPORT
S. 223 Collins, S. Senior$afe Act --- --- Monitor
S. 365 Rounds, M. CFPB Dismantling Bill --- --- Monitor
S. 366 Rounds, M. --- --- SUPPORT
TAILOR Act of 2017
H.R. 1116 Tipton, S. Yes --- SUPPORT
S. 387 Perdue, D. CFPB Accountability Act of 2017 --- --- SUPPORT
S. 403 Hatch, O. HSA Expansion Bill --- --- Monitor
S. 563 Heller, D. Flood Insurance Market Parity and Modernization Act --- --- Monitor
S. 567 Heitkamp, H. --- --- SUPPORT
Federal Savings Association Charter Flexibility Act of 2017
H.R. 1426 Rothfus, K. Yes --- SUPPORT
S. 1139 Tester, J. Main Street Regulatory Fairness Act --- --- Monitor
S. 1284 Hatch, O. --- --- Monitor
Community Bank Relief Act
S. 1962 Rounds, M. --- --- Monitor
S. 1310 Rounds, M. HUMDA Amendment Bill --- --- Monitor
S. 1579 Rounds, M. CFPB Advisory Board Enhancement Act --- --- Monitor
S. 1910 Hatch, O. --- --- Monitor
State Regulatory Representation Clarification Act of 2017
H.R. 3915 Lucas, F. --- --- Monitor
Economic Growth, Regulatory Relief, and Consumer
S. 2155 Crapo, M. Yes Yes SUPPORT May 24, 2018
Protection Act
S. 2283 Risch, J. --- --- Monitor
Small Business 7(a) Lending Oversight Reform Act of 2018 June 21, 2018
H.R. 4743 Chabot, S. Yes Yes SUPPORT
S. 3042 Roberts, P. Farm Bill --- --- SUPPORT
S. 3343 Booker, C, Overdraft Fees and Reform Bill --- --- OPPOSE
16 The Ohio Community Banker | Fourth Quarter 2018COMMUNITY BANKING
ONE AT A TIME – COMMUNITY BANKS MAKE THE
DIFFERENCE
In Frank Capra’s 1947 classic, “It’s
a Wonderful Life,” George Bailey
forgoes multiple childhood dreams
and opportunities to reluctantly
take over the Bailey Brothers
Building & Loan. Little did George
know at that time, the significance
of that decision. One customer
at a time, he helps the citizens of
Bedford Falls achieve their dreams
and goals, and thereby improving
their community.
Aza H. Bittinger Jr. Unbeknownst to George, he
COO was slowly putting together a
Community Bankers
patchwork quilt. Each patch
Association of Ohio
ahbittinger@CBAO.com intricately weaved to the next
(614) 846-2238 relying on that bond. As he helped
each individual, they were able to
assist the next individual. Each individual becoming a larger
part of a more intertwined story.
Community bankers are leaders and difference makers While George Bailey may have been a fictional character in
stitching together needs and opportunities for the benefit an American classic, his bank succeeded because he made
of their communities, employees, stakeholders, and it personal. This personal commitment and dedication are
shareholders. Each community bank has an exceptional story evident throughout Ohio. As a result, Bedford Falls was a
to share, whether they are a de novo bank or more than 150 much better community, as are the communities in Ohio. At
years old. Each story is rich with pioneers, colorful characters, CBAO, the advancement of community banking is personal
game changers, and leaders. and we are proud to serve – one customer at a time.
While technology and innovation will always serve its place Advocating Exclusively for Community Banks in
in evolving business models, community banks possess an the state of Ohio since 1974
asset few businesses can lay claim to. It’s their story. This
story needs to be shared in our communities. Stories are
interesting and captivating. People always tune in for a good
story. If you spend any time at the teller line, you will hear a
few good stories shared by our customers from times gone
by or recent memorable events.
Every December, many of us tune in for our annual viewing
tradition of watching “It’s a Wonderful Life.” While we know
the ending, we still tune it because it’s an exceptional story Aza H. Bittinger Jr.
that is captivating and memorable with life lessons to be
learned.
“There’s always
room for a story that
All Ohio community banks have a unique and exceptional can transport people
story to share. Do our staffs and customers know our history? to another place.”
Do they know the energy needed to create our community
bank, who was involved in the process and what the original
need in the community was at that time? Do they know the – J. K. ROWLING
commitment needed and the prudent decisions made along
the way that contributed to success today?
www.cbao.com | The Ohio Community Banker 17Secure Endpoint Management
Endpoints are the gateway to your data.
Who is guarding the door?
A well managed endpoint is key to productivity and essential
to security and compliance. Our Fortress service brings the tools,
talent, and techniques to bear on the secure management of your
endpoints so you can focus on running your bank.
OVERWATCH
Remote Monitoring & Management
GUARDIAN
Managed Patching
SENTINEL
Managed Antivirus
VAULT
Managed Endpoint Backup
Reduce the cost and the time spent on IT management, mitigate
cyber threats, and become a resilient bank. Learn how by visiting,
www.mcpc.com/Fortress
18 The Ohio Community Banker | Fourth Quarter 2018CBAO FED PAC
Supporting CBAO FED PAC is the best way to aid the business from which we
earn our livelihood.
WHAT IS CBAO FED PAC
CBAO FED PAC is a voluntary, nonpartisan political action committee of Community Bankers
Association of Ohio. The objective of CBAO FED PAC is to support the election of candidates
who have an understanding of the community banking industry. CBAO FED PAC is an essential
tool in the efforts to ensure that our common concerns are heard and heeded by those who will
make decisions affecting our industry.
WHAT RESPONSIBILITIES WE FACE
Advancing our issues and the protection of our interests is CBAO FED PAC’s number one priority. Community bank and thrift
institutions are facing critical legislative issues. Supporting CBAO FED PAC is the best way to aid the business from which we earn
our livelihood.
WHY YOUR CONTRIBUTIONS ARE NEEDED
Under Ohio law, corporate funds cannot be contributed to candidates. Political Action Committees (PACs) must obtain their
funds directly from individuals and use those funds only to help candidates finance their campaigns. Your personal contribution
made directly to candidates clearly helps those candidates, but often may not convey the message that you are an officer,
director, or staff member of a community bank or thrift institution that is directly affected by many types of legislation.
CBAO thanks the following CBAO FED PAC 100% Contributors...
as of December 31, 2018
Hamler State Bank – Hamler, OH The Peoples Savings Bank – New Matamoras, OH
The Waterford Commercial & Savings Bank Woodsfield Savings Bank – Woodsfield, OH
– Waterford OH The Apple Creek Banking Company
The Sherwood State Bank – Sherwood, OH – Apple Creek, OH
The Richwood Banking Company – Richwood, OH Heartland Bank – Whitehall, OH
Andover Bank – Andover, OH First City Bank – Columbus, OH
Greenville National Bank – Greenville, OH Consumers National Bank – Minerva, OH
Farmers & Merchants Bank – Miamisburg, OH The Corn City State Bank – Deshler, OH
Metamora State Bank – Metamora, OH Osgood State Bank – Osgood, OH
The Peoples Bank – Gambier, OH Sutton Bank – Attica, OH
The Peoples Bank Co. – Coldwater, OH
www.cbao.com | The Ohio Community Banker 19Merchant Services
CBAO Preferred Partner
Is your merchant
services program No liability or
working for you? underwriting
The right program should Revenue on all
complement your bank’s unique processing activity
needs and circumstances.
Marketing support
FiNet takes pride in customizing a and branded assets
program for your bank that does
just that.
20
p: 330.702.8415 | 800.487.5577 | finet.net
The Ohio Community Banker | Fourth Quarter 2018Stay informed and connected in your banking field...
NETWORKING FORUMS 2019
CBAO University’s networking forums meet quarterly and facilitate idea exchange among peers
of a specific job function. Forum attendees discuss what’s currently going on in the industry with
regards to their role and discuss ways to improve in their area.
CFO/Controller Forum Human Resources Forum
Grow as a leader in bank financial management Bringing together a team strategy for long-term success
March 14 | June 18 | October 16 February 19 | May 23 | August 13 | November 7
Compliance Forum Innovating the Retail Experience Forum
Gain insight on new legislation and areas of regulatory focus Establishing strong customer relationships in a digital age
January 29 | May 7 | August 7 | November 5 March 7 | June 20 | September 12 | November 14
Cybersecurity/IT Forum Marketing Forum
Keep up with the latest in technology and risk management Thinking outside the box to solve the everyday challenges
February 25 | June 24 | October 21 February 27 | June 26 | October 23
Senior Lender Forum
Learn and explore emerging lending issues
February 28 | June 13 | August 15 | October 30
MORE DETAILS & ONLINE REGISTRATION AT CBAO.COM/FORUMS
www.cbao.com | The Ohio Community Banker 21A Bank’s
Most Important Asset
is Not on the
Balance Sheet!
James Caliendo It seems as though you can’t walk down the street without running into at
PWCampbell least one bank. In addition, access to countless more is available through the
internet.
It seems as though you can’t walk down the street For the most part, the product offering is the same, so what makes
without
running into at least one bank. In addition, access to
you choose one bank over another? In most instances, it is the efficiency,
countless more is available through the internet. For the
most part, the product James
offeringG. knowledge
is the same, so what makes and friendliness of your staff that keeps a customer coming back.
you choose one bank over another? In most With that
instances, much importance placed on youroffront
The quality our line, what are
buildings canyou doing
Caliendo
it is the efficiency, knowledge and friendliness of your
President/COO
staff that keeps a customer coming back. Withto that
attract
muchand retain the right impact
employees nottoonly oura productivity
deliver top notch customer
importance placed on yourPWCampbell experience?
front line, what are you doing Millennials, who but
willalso the way
comprise 40%weoffeel. Followingby 2020,
the workforce
to attract and retain the right employees to deliver a top the WELL Standards can effectively
are making decisions about where they work based on their values. Their
notch customer experience? Millennials, who will comprise
expectations
40% of the workforce by 2020, are making decisions
provide the following benefits:
about for a workplace environment plays a significant role in this
where they work based on their values. Theirchoice and therefore employers that meet their expectations will attract the
expectations
for a workplace environment plays a significant role in this • A more efficient and creative
choice and therefore employers that meet their bestexpectations
talent. That’s where the Wellworkforce
Building Standard comes into play.
will attract the best talent. That’s where the Well Building
• TheLower
WELLabsenteeism
Building Standard®,
rates the latest
Standard comes into play.
The WELL Building Standard®, the latest development in development in construction, is not only a
construction, is not only a new trend but a healthy one and • new trend healthcare
Lower but a healthycosts
one and piggy backs
piggy backs on the LEED certification program that was
introduced over a decade ago. LEED certification means
on the LEED certification program that
healthier, more productive buildings along with reduced • wasEnhanced
introducedability
over ato attract
decade and
ago. LEED
stress on the environment by encouraging energy and retain exceptional talent
certification means healthier, more productive
resource-efficient buildings. Of the sectors that have adopted
LEED, the financial sector has proven to be a leader in green buildings along with reduced stress on the
• A superior work environment
building and there is no reason to think the financial industry environment by encouraging energy and
people want to work in
won’t embrace the new correlating building trend which more
directly impacts the health and wellbeing of employees.
resource-efficient buildings. Of the sectors that
• have adopted LEED,
Improved the financial sector has
brand commitment
The new WELL Building Standard® is a performance-based
system for measuring, certifying, and monitoring features
proven
throughto beleadership
a leader in green
and building and
of the building environment that impact human health and innovation
there is no reason to think the financial industry
wellbeing, through air, water, nourishment, light, fitness, won’t embrace the new correlating building
comfort, and mind. A comprehensive listing for each Increased
• trend job directly
satisfaction
featured category is evaluated and scored to determine the which more impacts the health
company’s overall performance as it relates to the standards and wellbeing of employees.
established by the International WELL Building Institute.
22 The Ohio Community Banker | Fourth Quarter 2018Just as financial institutions have had to adjust to change
and new technology for decades, the trend continues with
the branch of the future and adopting this new idea of
creating environmentally healthy workspaces to enhance
the well-being of all employees. While some experts envision
the modern branches to be built for speed based with an
emphasis on self-service and 24-hour access, others believe it
to be built on engagement where branding plays a key role in
setting up more of a retail type feeling where customers are
encouraged to actively engage not just transact and get out.
Either way, employees play a key role in each strategy and About James G. Caliendo
their performance will play a vital role on whether or not it
will be successful. James G. Caliendo is a former bank executive and now
President and COO at the 107 year old retail services and
There’s no doubt people are the most important asset in design/build firm, PWCampbell. In the past
your bank and a major driver of overall success. It makes 10 years alone, PWCampbell has
absolute business sense to invest in them with quality influenced over 4 million square feet
workspace. As this is the core mission of WELL - to make of banking locations and worked with
businesses more effective by making the employees more
over 175 financial institutions to create
productive as well as an effective way to attract talented
engaging, impactful and scalable
millennials – it’s a strategy that should be strongly considered
as you contemplate renewing or adding to your retail delivery solutions for every sized project.
system or operations space.
We’ve harvested something big for agricultural lenders...
AGRICULTURAL SUMMIT 2019
WEDNESDAY, JANUARY 30, 2019 – HILTON GARDEN INN FINDLAY
www.cbao.com | The Ohio Community Banker 23REACH NEW HEIGHTS.
Payment solutions you can rely on from people you can trust.
Through the delivery of flexible, innovative payments and digital
commerce solutions, ICBA Bancard is helping community banks
challenge the payments status quo to meet their customers’
evolving needs and expectations.
Reach new heights with ICBA Bancard.
24 The Ohio Community Banker | Fourth Quarter 2018 www.icbabancard.org | bancard@icba.org | 800-242-4770You can also read


