Transitions to low carbon electricity systems: Key economic and investments trends - Changing course in a post-pandemic world
←
→
Page content transcription
If your browser does not render page correctly, please read the page content below

Transitions to low carbon electricity systems:
Key economic and investments trends
Changing course in a post-pandemic world

June 2021

The clean energy transition has been too slow and
progress too uneven to prevent the most severe impacts
 of climate change. But the COVID-19 pandemic forces
 decision-makers to change their course of action and
prioritize green recoveries over unsustainable strategies.

Countries, financiers, innovators and the civil society are
increasingly rallying around carbon neutrality objectives
around mid-century. The years ahead will be decisive for
 climate action. Sustainable lifestyles are within reach if
 the challenges inherent to clean energy transitions are
                    suitably anticipated.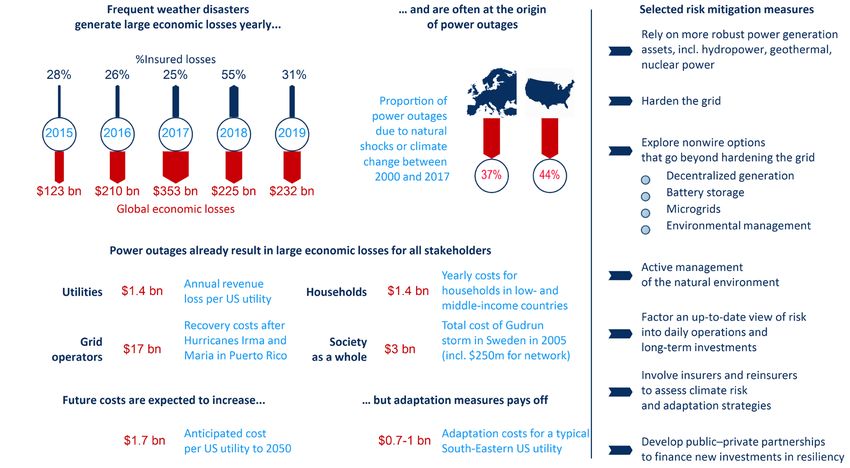
From a global crisis                                           Clean electricity roll-out:
      to a global opportunity                          p.2           From marathon pace to sprint speed p.4

• Climate science underpins the considerable physical,         • The transition to clean electricity manifests itself in

                                                                                                                           Recent trends on the energy transition
  social and economic benefits of reaching carbon                many markets but remains too slow for net-zero
  neutrality by 2050.                                            emission targets to be met on time.
• The shift to clean and secure electricity will lay the       • Thirty five percent of global electricity was supplied
  foundations for end-use electrification. Coal                  by low carbon sources in 2018. This share barely
  displacement is now a political priority.                      evolved over the past thirty years.

      No more one-size-fits-all                                      Growing more with less:
      in an evolving nuclear landscape                 p.8           A sober electrification                        p.10
• Nuclear power provides predictable and reliable              • The availability of clean electricity alone does not
  electricity in 32 countries and is a direct alternative to     guarantee the sustainable transformation of the
  coal.                                                          energy sector.
• At a levelized cost of $30-35 per MWh, extending the         • Energy-saving measures are crucial to circumvent
  operation of existing nuclear plants by 10 to 20 years         the burst of electricity consumption foreseen in many
  is one the most cost-effective low-carbon options.             countries, often outpacing economic activity.
                                                                 Unmonitored electricity consumption would result in
                                                                 overinvestments and higher energy bills.

      The impact of the COVID-19                                     More flexible systems

                                                                                                                           Topical issues on the
      outbreak on the electricity sector              p.12           to enable the transition                       p.14

                                                                                                                             energy transition
• The COVID-19 pandemic transformed the operation              • Flexible electricity infrastructure revolves around
  of power systems across the globe and offered a                regional interconnectors, dispatchable power
  glimpse of a future electricity mix dominated by low           generation units, including natural gas assets,
  carbon sources.                                                pumped storage hydropower plants and nuclear
• The competitiveness and resilience of low carbon               plants operated flexibly.
  technologies have often resulted in higher market            • Energy storage and demand-response options are
  shares for nuclear, hydro, solar and wind power.               also indispensable to reach carbon neutrality.

      Setting the global decarbonization                             From recovery packages
      in motion: All roads lead to carbon                            to low carbon finance                          p.20
      neutrality                          p.18
                                                               • The proposed energy plans in response to the

                                                                                                                           Key features and drivers of the transition
• Electricity production and end-use energy                      pandemic remain largely at odds with climate goals.
  consumption require a swift displacement of                  • More than $600 billion are invested yearly in clean
  unabated fossil fuels and a convergence towards                electricity infrastructures. Clean energy investments
  clean energy technologies.                                     must double immediately to pave the way for carbon
• By 2040, over 80% of electricity should be low                 neutrality.
  carbon, more than double current levels.

      Linking up local pollution and                                 Factoring the changing natural environment
      climate change agendas                         p.23            into investments decisions             p.25
• Local air pollution and climate change have common           • Severe environmental conditions episodically affect
  origins: unsustainable urban infrastructures. Clean            infrastructures worldwide, at great economic and
  power, clean mobility and efficient energy used in             social expense for asset owners, insurers and local
  manufacturing improve air quality and reduce                   communities.
  societal costs.                                              • Investing in built-in resilience of future energy
• CO2 emissions are declining in high income countries           systems to cope with a broader range of external
  but often continue to rise elsewhere. Populations              shocks will largely offset risk mitigation costs.
  living in lower income countries are particularly
  exposed to outdoor (and indoor) pollution.

      Aligning actions to
                                                     p.26
                                                                                                                           Policy priorities

      build back better

• Governmental leadership and institutional initiatives,       • Green recovery measures are expected to stimulate
  incl. the establishment of sustainable finance                 employment and economic activity. Social and
  taxonomies based on objective, transparent and                 inequality concerns inherent to the transition must be
  science-based criteria, are critical to boost low              tackled to ensure successful and just outcomes.
  carbon investments.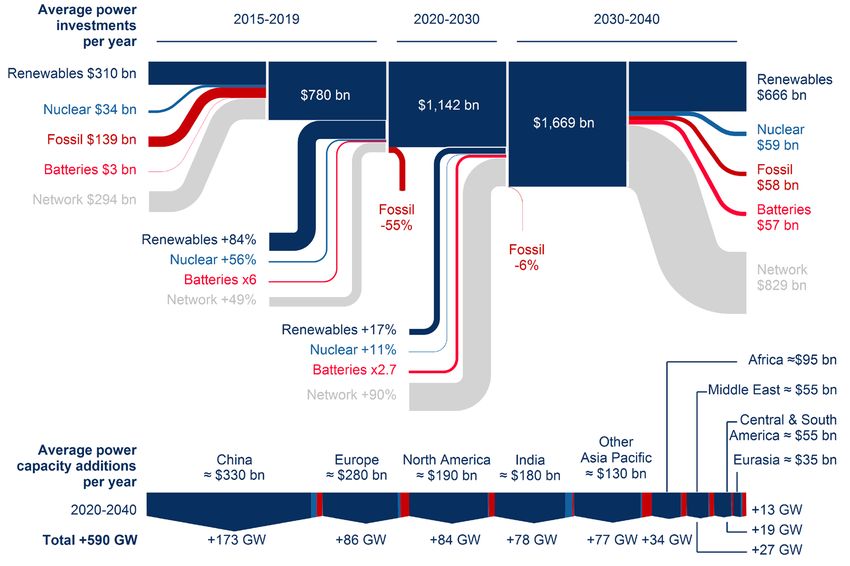
Transitions to low carbon electricity systems: Key economic and investments trends
Changing course in a post-pandemic world
The electricity sector1 acts as a catalyst for an economy-wide transition to a low carbon,
climate-resilient and sustainable future. This document shines a light on the nature and pace of
the ongoing transition to low carbon electricity systems, takes stock of the immediate impact of
the COVID-19 pandemic, and weighs prospects for accelerating the transition post-pandemic.
Will 2021 be a pivotal year for the energy transition?

             FROM A GLOBAL CRISIS TO A GLOBAL OPPORTUNITY

A year into the pandemic and a gradual recovery in                                                        Public and private leaders of the energy transition
sight. The social and economic shockwaves generated                                                       rally around high-stake opportunities to accelerate
by the COVID-19 outbreak laid bare the vulnerability of                                                   the recovery through clean energy adoption and
our societies and created one of the deepest economic                                                     pave the way to carbon neutrality. But countries’
recession in generations. Governments and the health                                                      progress and access to these opportunities remain
sector turned to scientific evidence to design and                                                        contrasted. The evidence compiled in this document
coordinate their responses. The World Bank and the                                                        points to a gradual and partial transformation of the
IMF foresee an uneven and uncertain recovery for 2021                                                     global energy landscape, as confirmed by the World
and beyond, and warn that the crisis hit the poorest                                                      Economic Forum (WEF): The Transition Readiness
nations hardest (Gopinath, 2021; Malpass, 2021),                                                          index reveals incremental progress in 94 of the 115
affecting their ability to respond to another looming                                                     countries monitored over the past six years (Fig. 1). High
challenge: the climate emergency.                                                                         income countries appear best prepared to pursue the
                                                                                                          domestic rollout of clean energy as they are to weather
A year for decisive climate action. Preliminary data
                                                                                                          the consequences of the pandemic. But fast progress
for 2020 points to a temporary drop in global CO2
                                                                                                          is also observed in South Asia, Southern Africa and
emissions but also a net increase in overall greenhouse
                                                                                                          Latin America, albeit starting from a lower base. The
gas emissions despite the economic slowdown (WMO,
                                                                                                          pandemic did not alter the fundamentals underlying
2020). A wide mobilization of scientific and financial
                                                                                                          WEF country scores. The success of a green recovery,
resources is thus as urgent as necessary if the world
                                                                                                          possibly giving new impetus to the energy transition,
is to avert the most severe impacts of climate change
                                                                                                          will depend greatly on governments’ ability to set
on our living environments. With firmed up political
                                                                                                          radical goals, implement policy reorientations and opt
ambitions, the emergence of integrated low carbon
                                                                                                          for sustainable supply chains across the entire energy
solutions and harmonized corporate strategies, the
                                                                                                          sector.
year 2021 can culminate at the UN climate change
conference in Glasgow with landmark outcomes.

Figure 1 – World Economic Forum Energy Transition Index 2

                    Change in ETI country score from 2015 to 2020                                                                 2020 Top 5 ETI scores by income group

                                                                                                                 High income              SWE    74%
                                                                                                                 Average ETI score: 62%   CHE    73%
                                                                                                                                           FIN   72%
                                                                                                                                          DNK    72%
                                                                                                                                          NOR    72%
                                                                                                                 Upper middle income      COL    63%
                                                                                                                 Average ETI score: 53%    CRI   62%
                                                                                                                                          MYS    59%
                                                                                                                                          PER    59%
                                                                                                                                          GEO    59%
                                                                                                                 Lower middle income        AR
                                                                                                                                          MAR    56%
                                                                                                                 Average ETI score: 48%    LKA   56%
                                                                                                                                          PHL    55%
                                                                                                                                           SLV   55%
                                                                                                                                          VNM    53%
                                                                                                                 Low income                TJK
                                                                                                                                            JK   50%
                                                                                                                 Average ETI score: 43%   ETH    46%
                                                                                                                                          MOZ    42%
         ETI                                                                                                                               HTI   36%
  difference from
     2015-2020

             +30%

              0%
   © 2021 Mapbox
          -5%    © OpenStreetMap

 Note: The Energy Transition Index benchmarks countries on the performance of their energy system, as
 well as their readiness for transition to secure, sustainable, affordable, and reliable future energy system.

                                                                                                    2
Recent findings from climate science underpin                                  human resources means will see a more progressive
the considerable physical, social and economic                                 implementation. Recent country pledges suggest that
benefits of limiting the global temperature increase                           carbon neutrality may be reached by the wealthiest
well below 2ºC. A strict management of our carbon                              nations around mid-century and a decade later
budget is of the essence. Ongoing trends suggest                               elsewhere through piecemeal approaches compatible
a temperature rise in excess of 3ºC before the end                             with economic development.
of the century. At current levels of global greenhouse
                                                                               The adoption of low carbon technologies will
emissions, our carbon budget would be exhausted
                                                                               materialize as solutions gradually reach market
in about a decade, triggering warming beyond 1.5°C
                                                                               maturity. The shift to clean and secure electricity
irremediably (with one in two chances) (IPCC, 2018). Our
                                                                               will lay the foundations for end-use electrification.
energy systems rest on regular boundary conditions of
                                                                               Coal replacement has become a political priority.
water availability and temperature. Higher atmospheric
                                                                               Clean electricity is an indispensable precursor to
temperatures would raise the odds of extreme rainfalls,
                                                                               carbon neutrality in other sectors (Fig. 2). Electricity-
flooding and droughts, eventually impeding the
                                                                               related emissions, trending upward for decades, must
reliability of energy services; cooling demand in cities
                                                                               now drop by at least 6% every year through to 2030. In
would soar, amongst other and numerous impacts. The
                                                                               addition to nuclear and hydro, various clean electricity
Race to Zero, initiated by the UNFCCC, must therefore
                                                                               options have reached mass market in recent years ;
gain momentum. A quarter of greenhouse emissions
                                                                               their deployment can be immediately accelerated to
expected by 2030 could be avoided with the sole
                                                                               replace uncompetitive coal assets, at the origin of two
implementation of unconditional Nationally Determined
                                                                               thirds of power-related emissions (SystemIQ, 2020).
Contributions announced before the pandemic (UNEP,
                                                                               A coal-to-clean energy transition could generate over
2020a).
                                                                               $100 billion in net financial savings as early as 2025.
Policy makers gradually embrace holistic                                       But a clear path to phaseout, including the refinancing
approaches to decarbonization, addressing all                                  of existing assets, is lacking (RMI, 2020).
energy producing and consuming activities,
                                                                               The remainder of the document depicts ongoing trends
but also governmental aspirations in favour of
                                                                               and initiatives in support of the energy transition,
a just transition. The climate action instigated by
                                                                               including the overall impact of the COVID-19 outbreak
individual countries is more and more embedded
                                                                               on electricity systems. The emphasis is given on
in inclusive strategies aimed at generating income
                                                                               immediate opportunities for cleaner electricity in
and employment, in line with other industrialization
                                                                               various economic contexts and in an evolving financial
objectives. Comprehensive policy frameworks, based
                                                                               landscape. Some of the key enablers of the transition,
on fiscal, financial and other social protection measures,
                                                                               including various options for flexible operations, are
as well as behavioural and sector coupling policies,
                                                                               illustrated through selected examples. Broader policy
are necessary to create the conditions for a just and
                                                                               drivers are also discussed, such as air pollution and
cost-effective transition (IRENA, 2020a). Early adoption
                                                                               the vulnerability of energy infrastructures exposed to
of low carbon measures and a progressive shift away
                                                                               harmful climate conditions.
from fossil fuels is expected in high income countries.
Other jurisdictions with more limited financial and

Figure 2 – Illustrative transition to low carbon power systems in line with the Paris Agreement; 2019 serves as the reference year3

 Global GHG Emissions                      2010                       2019                                2030                                  2040

                                                                59.1Gt
                                                                                                                         2019
                          -14%
                                                                                                                       Total GHG
 Total GHG
                           -9%                                 33.3Gt
 Energy-related CO2                                                                        -27%

 Power-related CO2         -10%
                             0                                  13.7Gt                                                         -56%
                                  12.4Gt
                                                                                           -43%   7.8Gt
 2019 Total GHG                                                                                                                -77%                    3.2Gt

 CO2 emissions for
 electricity generation

                                   -10%                        13.7Gt
 Total                                                                           3.1Gt
                                                                                                  -43%
                                                  -16%                                                           -9%                   -77%          -41%
 Coal
                                  +30%                        0.7Gt                               -55%
 Oil                                                                                                      -53%                        -71%
                                              -10%                           9.9Gt
                                                                                                                                              -87%
 Natural Gas

                                                                         3
CLEAN ELECTRICITY ROLLOUT: FROM MARATHON PACE TO SPRINT SPEED

Clean electricity is on its way to replace fossil fuels          production capacity to address both domestic needs
and become the main driving force of economic,                   and markets overseas have established China as the
social and environmental progress. The switch to                 global leader of clean power manufacturing. The year-
clean electricity is manifest in many markets but                on-year change in low carbon power approaches 11%
remains too slow for net-zero emission targets to be             in China while electricity consumption progresses at
met on time. Among the main energy carriers, electricity         more than 7%. At current rates of market penetration,
is growing the fastest confirming a general trend                about thirty years would be necessary to reach 100%
towards electrification of energy use. A fifth of energy         low carbon electricity in China and almost fifty years
consumption is electric, leaving vast opportunities for          globally, way too late to avoid severe hardships resulting
fossil fuel displacement in final consumption sectors            from climate change (IPCC, 2018).
(Fig. 3, top panel). Electricity usage has levelled off in
                                                                 Non-dispatchable electricity sources are now
North America, Europe and other high-income regions
                                                                 on par with most conventional sources in many
thanks to effective energy-saving measures and
                                                                 markets, stimulated by major technological
moderate economic growth. By contrast, consumption
                                                                 advances and cost reductions as well as robust
grows swiftly in fast-growing economies, resulting in
                                                                 regulatory frameworks. Comprehensive policy and
an acceleration of global electricity needs (on average
                                                                 regulatory frameworks, indispensable to accelerate the
+2.7% every year since 2010). Thirty five percent of
                                                                 clean energy transition, are now in place in a majority
global electricity was supplied with low carbon sources
                                                                 of countries (World Bank, 2020b). Direct mechanisms
in 2018 (Fig. 3, mid panel). This share barely evolved
                                                                 in support of renewable expansion are wisdespread,
in more than thirty years. Growing at an average 3.8%
                                                                 inlc. fiscal exemptions (e.g. production tax credits or
each year during the last decade, and 5% in the last
                                                                 investment tax credits), and various mechanisms to
five years alone, the expansion of low carbon electricity
                                                                 guarantee operators’ revenues independently from
only makes up for the incremental electricity needs
                                                                 market conditions. Auctions are often preferred
but remains insufficient to alter the sector’s emissions
                                                                 options to identify the most competitive vendors. The
perceptibly. Electricity generation is responsible for
                                                                 enforcement of such measures has created favourable
42% of global CO2 emissions, another stable figure for
                                                                 conditions for the uptake of modern renewable
more than two decades (Fig. 3, bottom panel).
                                                                 energy in a wide range of countries across all income
Progress is unevenly distributed across income                   segments. The surge in low carbon electricity from
groups. Contrasted realities and prospects for                   onshore wind and solar PV, but also small to mid-size
rapid evolution stem from current market drivers                 hydropower projects, has resulted in a doubling of
and other legacy assets, chief among them are                    renewable capacities since 2010. On average, 200 GW
inefficient coal power plants. High income countries             of renewable capacity is installed yearly, incl. 100 GW
tend to have relatively lower carbon footprints of               of solar, 50 GW of wind and another 20 GW of hydro
electricity largely as a result of early investments             (IRENA, 2020b). Solar and wind sources now supply
in hydro and nuclear power capacities. The carbon                7% of global electricity. In 2018, solar and wind supplied
intensity in high income countries operating nuclear             half of clean electricity in 27 countries. By comparison,
capacities is generally among the lowest, averaging              hydro and nuclear account respectively for 16% and
300 grams of CO2 per kWh, and as low as 50 grams                 10% (IEA, 2020b).
in Sweden (Fig. 4).Average intensities in other income
                                                                 Clean energy leapfrogging is increasingly
groups are closer to 500 grams. In 2018, half of the low
                                                                 within reach for low income countries thanks to
carbon electricity in countries with nuclear assets was
                                                                 adapted solutions and innovative finance. But
produced from nuclear power plants. However, clean
                                                                 some bottlenecks remain for the transition to be
power progresses half as fast in high income countries
                                                                 fully inclusive. Distributed and renewable electricity
as in lower income groups (resp. 3% and 7% on average
                                                                 access and mobile payments are accesible to the
since 2015). Rapid improvements in carbon intensities
                                                                 most vunerable populations. But stark regulatory
were realised in upper-middle to lower-middle countries,
                                                                 discrepancies between the wealthiest and the poorest
thanks to higher environmental standards and policy
                                                                 nations remain. Financially unhealthy power utilities,
reforms such as fossil fuel subsidy removals, direct
                                                                 “the main off-takers of renewable energy and principal
public support for low carbon programmes and waves
                                                                 implementers of energy efficiency programs”, should
of inefficient coal plant shutdowns. Strong policies,
                                                                 be at the centre of governments’ attention (World Bank,
the development of local supply chains and enough
                                                                 2020b).

                                                             4
25
IDN
I
USA
J
Domestic
DE
SA
Electricity
42%
40%
|
0
00 5 10
10 15 20
20 25 30
30 35 40 45 2000 2018
CO2 emissions from electricity generation as share of global total (%)
Global CO2byemissions
Figure 3 – Domestic vs global distribution of final consumption of electricity by country (Top panel); Low carbon electricity country
(Mid panel); Electricity-related
In 2000, CO2was
electricity production emissions by of
at the origin country
40% of(Bottom panel),
global CO2 2000-2018. Top 10 contributors are highlighted in blue.4
emissions
In 2018, electricity production was at the origin of 42% of global CO2 emissions
Domestic share of electricity in final energy
100
100
–– 2000
–– 2018 9,938 Mtoe
consumption (%)
75
75
7,032 Mtoe
50
50 81%
JPN
CAN FRA
USA GBR BRADEU
| | | 84%
25
25 | | | | RUS CHNIND
| | |
JPN
CHN
KOR
FRA
CAN
U
USA
Electricity
BRA
IND
RUS
19%
|
00 16%
00 5 5 10 10 15 15 20 20 2000 2018
Final electricity consumption as share of global total (%) Global final energy consumption
In 2000, electricity consumption accounted for 16% of global final energy needs
In 2018, electricity consumption accounted for 19% of global final energy needs
NOR
SWE
| |
electricity
FRA BRA
NOR
SWE
100
100
| |
| |
26,619 TWh
electricity
–– 2000 FRA BRA
100
100 –– 2018
–– 2000
CAN
| | 26,619 TWh
low carbon
–– 2018 |
CAN
(%) (%)
75
75
of carbon
|
generation
75
75 65%
15,427 TWh
generation
JPN
of low
DEU 65%
50
50 RUS
| 15,427 TWh
share
FRA FRA
|
BRA BRA
JPN
CAN CAN
| DEU
USA
50
50 RUS
|
|
share
65%
| |
CHN
Domestic
USA
GBR GBR
| |
DEU DEU
25
25 CHN
65%
Domestic
Low carbon
RUS RUS
USA USA
electricity
CHN CHN
25
25 | 35%
JPN JPN
IND IND
| |
Low carbon
electricity
35%
00 35%
35%
00 00 5 10
10 15 20
20 25 30
30 35 40
40 2000 2018
0
0 5 10 Low carbon
10 15 electricity 20
as
20 share of global
25 total (%)30
30 35 40
40 Global electricity generation
2000 2018
Low carbon electricity as share of global total (%) Global electricity generation
In 2000, 35% of global electricity consumption was low carbon
In 2018,
2000, 35% of global electricity consumption was low carbon
electricity
In 2018, 35% of global electricity consumption was low carbon
electricity
100
–– 2000
fromfrom
100 –– 2018 33.5 GtCO2
ZAF –– 2000
emissions
| –– 2018 33.5 GtCO2
(%) (%)
75 RUS
ZAF POL
emissions
| |
AUS
|
IND GBR
generation
RUS
75 POL | IND
|
CHN
USA
| 23.2 GtCO2
| |
AUS DEU GBR 58%
|
generation
of CO2
50 | | CHN | DEU
USA
KOR JPN
|KOR | 23.2 GtCO2
| | JPN
|
58%
of CO2
50 | | 60%
| |
share
KOR KOR
60%
CHN CHN
ZAF ZAF
RUS RUS
IND IND
JPN JPN
share
25
DEU DEU
SAU SAU
IDN IDN
USA USA
Domestic
Electricity
42%
25
Domestic
40%
| |
Electricity
42%
0
40%
0 00 5 10
10 15 20
20 25 30
30 35 40 45 2000 2018
00 5 10
CO2 emissions15
10 20 25 as share30
20 generation
from electricity 30 35 (%)
of global total 40 45 2000
Global 2018
CO2 emissions
CO2 emissions
In 2000, electricity production from
was at theelectricity generation
origin of 40% asCO2
of global shareemissions
of global total (%) Global CO2 emissions
In 2000,
2018, electricity production was at the origin of 40%
42% of global CO2 emissions
In 2018, electricity production was at the origin of 42% of global CO2 emissions
energy
100
energy
100
in final
100 –– 2000
100
5 –– 2018 9,938 Mtoe
ricity in final
–– 2000
(%) (%)
75 9,938 Mtoe
electricity
75 –– 2018
mption
75
75
7,032 Mtoe
on
The integration of large volumes of non-dispatch- A wider adoption of carbon pricing regimes and
able electricity creates a challenging environment fossil fuel subsidy reforms can be transformative
for investors and operators. Low operating costs for the power sector. But concerns persist
characterizing wind and solar energy result in growing regarding the choice of instruments, the sectoral
market price volatility and pose significant risks for scope, their practical implementation, and the
investment in capital intensive technologies. Nuclear economic and social impacts. 46 national and 35
operators are directly exposed but large offshore wind subnational jurisdictions, representing 22.3% of global
and solar thermal developers are not exempt and can GHG emissions, have already integrated carbon pricing
have risky profiles to private financiers as well. in their portfolios, through either direct taxation or
tradable emission rights and other implicit charges
The observed decline in fossil fuel generation in early
stemming from regulatory standards (World Bank,
stages of the COVID-19 pandemic, as well as frequency
2020c). For instance, Swedish utilities and end-users
deviations observed early 2021 in the Continental
have been facing a combination of market and fiscal
Europe synchronous area, drew attention to additional
instruments for years. With these instruments in place,
grid stability challenges likely to emerge further into the
and large hydro and nuclear capacities, the Swedish
energy transition. Replacing heavy rotating steam and
electricity is among the most carbon sober in the world.
gas turbines with variable renewables leads to a loss of
National emissions dropped by 25% and the economy
inertia in the electricity system, and may result in greater
grew by 60% since the carbon tax introduction in
instability, poorer power quality and increased incidence
1991, demonstrating the environmental and economic
of blackouts. Large nuclear plants can alleviate the risk
effectiveness of carbon penalties. Corporate decisions
of supply disruptions in fully decarbonized electricity
are also increasingly driven by internal climate
systems. Grid managers without nuclear or natural gas
objectives and carbon prices. Finally, reforms of fossil
capacities at hand are gradually turning to synchronous
fuel subsidies were conducted successfully in many
condensers and storage solutions to integrate non-
countries across all levels of income, e.g. Nordic
dispatchable renewable energy. New business models
countries but also Argentina, Costa Rica, Ethiopia,
and revised pricing rules are foreseen to support this
India, Indonesia and Zambia.
trend.
Figure 4 – Carbon intensity of electricity by income level, 1990-20185
Lower middle income group Upper middle income group High income group
1990 2018a 1990 2018a 1990 2018a
Nuclear country
1200 1200 1200 Non nuclear country
Country group average
Nuclear country average
1000 1000 1000
---ZAF
Grammes of CO2 per kilowatt-hour
800 800 800
---IND ---CHN
---RUS
600 600 ---CZE
600
---KOR
---UKR
---IRN
---BGR ---JPN
---MEX ---NLD
---DEU
---ROU
400 ---PAK 400 400 ---USA
---HUN
---ARG
---SVN
---FIN
---ESP
---GBR
---BEL
200 200 ---ARM 200 ---SVK
Long term target
---CAN
50 gCO2 per kWh
---BRA
---FRA
---SWE
---CHE
0 0 0
1990 702 MtCO2 1990 RUS 2,591 MtCO2 1990 USA 4,189 MtCO2
2018 IND 1,814 MtCO2 2018 CHN 6,441 MtCO2 2018 USA 4,486 MtCO2
6
Figure 5 – Breakdown of low carbon electricity by country, 20186
In 2018, nuclear power accounted for High Income Nuclear
Upper Middle Income
at least half of low carbon electricity Dispatchable Renewable
Lower Middle Income
in 11 of 30 countries Low Income Non-Dispatchable Renewable
FIN CHE GBR
SWE
ARM ESP
IRN
ZAF
ROU
RUS
JPN
SVN
DEU
USA
MEX
BEL
PAK
BGR
SWE FIN CHEGBR
ESP
CAN
SVK IRN
ZAF
RUS ROU
SVN JPN ARG 2010
CZE DEU
USA
MEX
BEL
NLD
BGR PAK
FRA
CAN
SVK
ARG CHN
HUN CZE Countries
NLD
FRA with operating IND
CHN
KOR HUN nuclear capacity
IND
KOR
BRA
UKR UKR
2018 BRA 2000
HI UMI
LMI LI
ZWECUWBEN BWA BRN
UZB ZMB
TJK ERI
SYR ISR
SDN KGZ
PRY LIE
LAO NER
CRI SAU
AGO SSD
ALB YEM
MOZ ARE In 2018, non-dispatchable accounted
ISL JOR
for at least half of renewable
MMR TUN
electricity in 27 countries
COG MHL
COD CYP
COL ZMB
UZB CUW
ZWE BEN
BWA
BRN
TJK
SYR ERI
ISR DZA
SDN
PRY
KGZ
LIE
VEN LAO NER IRL
CRI SAU
AGO SSD
GAB ALB YEM MNG
MOZ ARE
ISL JOR
NPL MMR TUN MAR
COG MHL
KHM COD CYP DNK
COL DZA
CMR VEN IRL JAM
GAB MNG
NPL MAR
NGA GRC
KHM DNK
HTI CMR
NGA
Countries JAM
GRC
POL
GHA HTI without operating POL AUS
GHA AUS
ECU ECU nuclear capacity MAC MAC
IDN PRT
IDN VNM TGO PRT
VNM
GEO
SUR
2018 URY
BLR TGO
SRB ITA 2010
GEO BIH EST URY
MDV NIC
SUR NAM HND BLR
NOR TUR
SRB HKG DOM ITA
IRQ CHL
LBN CUB
BIH TZA SGP EST
KEN BGD
MDV ETH THA NIC
NZL EGY
GTM LSO
AZE CIV
NAM BOL SEN HND
MNE
LKA AUT
HRV
PER
SLV
KAZ
MDA
PAN
MUS PHL
KWT
NOR TUR
HKG DOM
IRQ CHL
LBN CUB
TZA SGP
KEN BGD
ETH THA 2000
NZL EGY
GTM LSO
AZE CIV
BOL SEN
MNE AUT
LKA HRV
PER SLV PHL
KAZ MDA PAN MUS KWT
HI UMI
LMI LI
Note: High income= HI, Upper middle income = UMI, Lower middle income = LMI, Low income = LI
7
NO MORE ONE-SIZE-FITS-ALL IN AN EVOLVING NUCLEAR INDUSTRY

The merits of nuclear power and its place in the                Construction risks and capital costs can undermine
achievement of carbon neutrality are generally                  the financeability of nuclear projects in liberalised
acknowledged. The extent to which nuclear power                 markets. Tailored fiscal support and risk transfer
can favour the transition will depend on the industry’s         schemes to restore competitiveness are under
ability to bring costs down, accelerate innovation              examination. Financial innovation will be critical to
and garner enough public support. In 2019, the                  overcome project risk and fiscal burden associated
nuclear capacity installed globally saw a net decline of        with delays in project delivery and cost overruns (NEA,
4.5 gigawatts as the permanent shutdowns confirmed              2020a). Risk premiums can be substantial. In the case
in Japan offset new grid connections elsewhere (IAEA,           of UK’s Hinkley Point, where a contract for difference
2020a). But increased capacity factors, notably in the          guarantees the operator’s revenue irrespective of
United States, helped maintain global power generation          wholesale market conditions, risk premiums account
levels. Nuclear fleet extensions are at various stages          for more than a third of the strike price approved by the
of advancement in 16 countries while 5 new nuclear              government (£36 per MWh) (NSD, 2020). The proposed
programmes are in the construction phase (Fig. 6). The          Regulated Asset Base model aims at transferring risks
centre of gravity of nuclear operations is swiftly moving       to consumers with enhanced government protection
towards Central and Eastern Europe and Asia at large.           during the construction phase and could serve as a
                                                                model for other projects worldwide (UK BEIS, 2020).
The traditional economic model of nuclear power
is challenged by liberalised electricity markets in             Maintaining and extending the safe operations of
which many plants operate, by the diversification               existing plants preserves clean power capacity,
of power mixes as well as the rapidly evolving                  is economically sound and could, as such, be
policy, regulatory and technological landscape.                 incorporated into COVID-19 recovery packages to
Nuclear power provides predictable and reliable                 boost local economies and foster the transition.
electricity, providing 32 operating countries with a            Nuclear supply chains are generally considered
secured supply of electricity. The need for flexibility         valuable vectors of local economic development and
in electricity generation and system management – a             job creation: Every million-dollar invested in nuclear
trend accelerated by the pandemic – will increasingly           creates four jobs (IEA, 2020d). With a supportive
characterize future energy systems over the medium              investment environment, a 10-20-year licence renewal
to longer term. Improved frameworks for remunerating            can be realized at a levelized cost of around $30-
reliability, flexibility and other services would favour        35 per megawatt-hour, placing it among the most
nuclear operators.                                              cost-effective low-carbon options, while maintaining
                                                                dispatchable capacity (NEA, 2020b). Without such
The climate imperative and a wider value
                                                                extensions, 40% of the nuclear fleet in developed
proposition for better market adequacy may
                                                                economies may be retired within a decade, adding
boost nuclear developments in the mid-term. The
                                                                around $80 billion per year to electricity bills (IEA, 2019).
historical contribution of nuclear power to low carbon
                                                                Long term operation is common in the United States
electricity is widely acknowledged, nuclear power
                                                                with most licences renewed for 60 years, four reactor
remaining the second largest source of clean electricity
                                                                licences subsequently renewed to 80 years and others
globally. A single gigawatt-scale nuclear project can
                                                                set to follow. France’s Grand Carenage programme
dramatically improve climate compliance in mid-sized
                                                                aims at 10 to 20-year extensions for an estimated cost
countries, as shown by the recent start of United Arab
                                                                of EUR45-50 billion.
Emirates’s nuclear programme which will eventually
supply a quarter of national needs with clean power.            The nuclear industry has yet to find its niche in the
Nonetheless, a certain lack of governmental and                 supply of new services, including opportunities
policy support prevents nuclear energy from meeting             in a nascent hydrogen economy. Several business
its full mitigation potential. The inclusion of nuclear         models are being designed. Arizona’s public power
in taxonomies to channel sustainable investments                utility is looking to produce hydrogen from its nuclear
could encourage potential investors (OECD, 2020).               plant, blend it with natural gas to fuel another of its
Small modular reactor designs draw attention in many            plants, and thereby optimize its production and reduce
countries seeking a quick transition to low carbon              its overall carbon footpint. Alternatively, the UK Clean
power but with limited financial and physical capacity to       Energy Hubs in Sizewell and Moorside are fully-
absorb larger projects. Fast tracking the manufacturing,        integrated propositions, conceived in partnership with
shipping and installation of modules is expected to             local energy users, linking emerging technologies such
accelerate commercialization.                                   as low carbon hydrogen and energy storage.

                                                            8
Figure 6 – Nuclear electricity generation by income group, 2000 and 2019. Estimated annual electricity generation from nuclear power
plants currently under construction7
Income per capita group
Countries with operating capacity, new nuclear programmers with plants under
High Income
construction, and IAEA integrated Nuclear Infrastructure Review(INIR) missions Upper Middle Income
Lower Middle Income
Low Income
Countries with operating nuclear capacity Nuclear generation from plants
under construction and new
nuclear programmes
USA
USA
ARE
BLR
TUR
EGY
BGD
113 TWh
FRA FRA
JPN Nuclear generation from plants
under construction in existing
nuclear programmes
DEU KOR
CAN KOR
GBR GBR
CAN DEU JPN
JPN USA
FIN SVK CHN
SWE
ESP FRA
ESP
SWE
GBR RUS
BEL
2000 CHE 2019 BEL
BRA
CZE IRN
FIN
2444 TWh SVN
2657 TWh CHE 333 TWh ARG
FIN IND
NLD
HUN UKR
KOR SVK PAK
SVK ROU
HUN
SVN
ZAF NLD
CZE
MEX
ARG PAK
BRA BGR
PAK BRA
MEX ZAF
LUX
LIT CHN BGR ARG
ARM IRN
IND RUS IND
ROU RUS
UKR ARM IAEA Integrated Nuclear
CHN Infrastructure Reviews
UKR
conducted since 2009
GHA NGA
IDN PHL
JOR POL
17% of global total electricity generation 10% of global total electricity generation KAZ SAU
48% of global low carbon electricity generation 28% of global low carbon electricity generation KEN SDN
MDV THA
MAR VNM
NER ZAF
High Income 81%
2000 USA JPN FRA DEU Other KOR
High Income 72%
0.0% 20.0% 40.0% 60.0% 80.0% 100.0% 120.0% 140.0%
2018 USA FRA KOR Other CHN RUS
0.0% 20.0% 40.0% 60.0% 80.0% 100.0% 120.0% 140.0%
Note: Anticipated nuclear generation from reactors under construction
9GROWING MORE WITH LESS: A SOBER ELECTRIFICATION
Electricity demand is set to become one the main electricity consumption worldwide. Policies, fiscal
indices of energy transformation. Contrary to most incentives and wider value propositions from car
mature economies where consumption growth manufacturers are boosting electrification of ground
has come to a halt, electricity remains an essential transportation, now considered a major source of value
driver of development in fast-growing economies. creation in the near term. Low-carbon electricity-based
In high income countries, the yearly consumption of solutions also have the potential to eliminate emissions
electricity per capita now lies above the 9,000 kWh from cement, steel, plastics and aluminium production
mark, a slight decline since 2010, but also a 12% and increase industries’ profitability. This trend may
increase compared to levels observed in 2000 (Fig. leave consumers better off given the small portion of
7, upper panel). Setting carbon neutrality goals may electricity in the total cost of finished products. Plug-to-
delay the saturation in consumption across all income wheel consumption of battery-powered electric vehicles
segments. By contrast, consumption keeps growing could be 73% lower than tank-to-wheel consumption of
in lower income countries, spurring industrialization a typical gasoline car. Similarly, the tonne of green steel
and the emergence of middle class populations with may increase by 20% but adding only $180 to the price
increased ownership of electrical appliances and other of a car (ETC, 2020).
electronic devices. Each year, the average individual
However, the sole availability of clean electricity does
consumption of electricity rises around 3% (resp. 4%)
not guarantee a sustainable transformation of the
in upper-middle (resp. lower-middle) income countries.
energy sector. Unmonitored electricity consumption
Per capita electricity consumption in China and India
would result in overinvestments and higher energy
have reached respectively 5,000 kWh and 1,200 kWh
bills, eventually altering the economic benefits of the
per year but growing significantly faster than their peers
energy transition. Anticipating realistic future needs
in their respective income groups. The annual rate of
is critical to schedule the cost-effective upgrade of
progress has been closer to 2% in the lowest income
energy infrastructures. The EU Strategy for Energy
countries where large electrification gaps – and deficient
System Integration addresses the issue by placing the
existing infrastructures – are closing only gradually.
emphasis on more circular energy systems with an
Access to reliable electricity allows economies “energy-efficiency-first” principle (EC, 2020).
to flourish and living standards to improve. The
Tailored incentives and mandates, which are
adoption of high-performance electrical equipment
necessary to optimize electricity production and
is also deemed good value for money. A quick
moderate consumption, remain the blind spots of
access to electricity services, simplified administrative
existing policy frameworks. Incentives and mandates
procedures, moderate and transparent tariffs, are vital
are decisive for power and grid utilities seeking
for businesses to thrive (World Bank, 2020d). Frequent
efficiency gains and managing demand-side measures.
power outages and non-cost reflective tariffs, often
But progress in regulatory frameworks is reportedly
the result of chronic under-investments, are common
slow and penalties in case of non-compliance are often
in lower income economies and can be particularly
lacking, including in high-income countries (World
harmful to local entrepreneurial activity.
Bank, 2020b). Public budget financing, consumer
Electricity consumption is accelerating in many surcharges, combined with optimized time-of-use rate
countries, often outpacing economic activity (Fig. 7, structures, can be used to compensate for revenue
lower panel). Every dollar generated globally embeds losses induced by mandated energy efficiency activities
roughly 23 kWh of electricity. The decoupling between but are implemented too sporadically. Incentives and
electricity and GDP was sizeable two decades ago but mandates can also be beneficial to large industrial and
has been slowing down more recently. Since 2010, commercial consumers. But a lack of awareness and
the electricity intensity of the global economy has inadequate energy management programmes prevent
been growing at 1% per year (1.8% in upper-middle the full optimization of electricity usage. Other incentives
countries). Generalizing the electrification of end- for further energy efficiency gains can be applied to
use, either directly (potentially supplying 65% to 70% public procurement rules with a binding obligation to
of final demand according to ETC, 2020) or indirectly track realized savings in public administrations and
through e.g. water electrolysis for hydrogen production other types of institutional infrastructures.
(potentially 15-20% of energy needs), is likely to boost
10Figure 7 – Per capita electricity consumption and electricity intensity of GDP by income group, 2000-20188
LI LMI UMI HI
Per capita electricity consumption (kWh per capita)
2019
Togo India China United States
2018
Togo India China United States
2010
Togo India China United States
2000
1 10 100 1,000 10,000
CAGR per capita electricity consumption (% per year) LI LMI UMI HI
2000-2010
15% 2010-2018
Togo India China
United States
10%
5%
0%
-5% 2000-10 avg: 4.3% 2000-10 avg: 3.0% 2000-10 avg: 1.5%
2010-18 avg: 4.4% 2010-18 avg: 1.9% 2010-18 avg: 0.5%
LI LMI UMI HI
Electricity intensity of GDP (kWh per US$ GDP)
2019 Togo India United States China
2018
Togo India United States China
2010
Togo India China United
e States
2000
0.008 0.04 0.2 1
CAGR electricity intensity of GDP (% per year) LI LMI UMI HI
2000-2010
10% 2010-2018
India China
5% Togo
United States
0%
-5%
2000-10 avg: -1.3% 2000-10 avg: -3.2% 2000-10 avg: -2.6%
-10% 2010-18 avg: -0.4% 2010-18 avg: -1.3% 2010-18 avg: -2.4%
Note: High Income=HI, Upper middle= UMI, Lower middle=LMI, Low income=LI; CAGR = Compound Annual Growth Rate.
11THE IMPACT OF THE COVID-19 OUTBREAK ON THE ELECTRICITY SECTOR
The COVID-19 pandemic transformed the operation the first period of global lockdowns. Then economic
of power systems across the globe and offered a activity – and electricity markets – resumed to more
glimpse of a future electricity mix dominated by low regular conditions. The large price drops in Europe
carbon sources. The systemic economic and social resulted from not only COVID-19 lockdown measures
impact of the COVID-19 outbreak, and the accompanying from March to June 2020, but also collapsing demand
responses, have led to an unprecedented and sustained due to an unusually warm winter, increased supply
decline in demand for electricity in many countries, of from renewables, and a slump in commodity prices
the order of 10% or more relative to 2019 levels over a (S&P, 2020). Such low prices create a challenging
period of a few months, thereby creating challenging environment for many electricity generators, including
conditions for both electricity generators and system nuclear plants. France’s EDF saw a 1% drop in its
operators (Fig. 8, left panel). Early IEA projections first quarter revenues. Similarly, Russia’s Rosatom
anticipated a 2% reduction in global electricity usage experienced a significant demand drop in April and May
for the entire year 2020, with a record 5.7% decline 2020, contributing to an 11% decline in revenues for the
foreseen in the United States alone (IEA, 2020d). first five months of the year (President of Russia, 2020).
Electricity generation from fossil fuels has been The competitiveness and resilience of low carbon
particularly hard hit, due to relatively high operating technologies have resulted in higher market shares
costs compared to nuclear power and renewables for nuclear, solar and wind power in many countries
and simple merit order effects. By contrast, low- during the initial three months of lockdowns.
carbon electricity prevailed during these extraordinary Market conditions in the United States, India, Brazil
circumstances. In the first weeks of the lockdowns, or the Ukraine were noticeably favourable to solar and
the contribution of renewable electricity rose in many wind generation (Fig. 9, top panel). Severe restrictions
countries thanks to low operating costs, priority on movement in China during early February led to
dispatch and favourable weather conditions (Fig. 8). an overall 6.8% contraction in activity during the first
Along with other measures, including curtailment of quarter, forcing power production to dip by more than
renewable generation in some cases, this has enabled 8% year on year: coal power decreased by nearly 9%
grid operators to maintain a reliable system and largely and hydropower by 12% due to a dry season (Tan and
avoid supply disruptions despite the challenging Cheng, 2020).
conditions, while also accommodating increased
Nuclear power generation also proved to be
shares of low-cost, variable renewable generation.
resilient, reliable and adaptable. The nuclear
The contraction in electricity demand during the industry rapidly implemented special measures to
first lockdown accelerated recent reductions in cope with the pandemic, avoiding plant shutdowns
electricity prices, below already economically- due to COVID-19, despite impacts on workforce and
unsustainable levels. The most noticeable impacts other supply chain challenges. With an average 2%
of the pandemic on the power sector occurred during reduction only during the lockdown, nuclear has proved
Figure 8 – Weekly change in electricity demand relative to 2019 (left panel) and relative to week prior lockdown (right panel) in selected
jurisdictions (Mar. 15–Jun. 6) 9
Weekly change in electricity demand relative to 2019 Weekly change in electricity demand relative to week
(March 16-June 7) prior lockdown (March 16-June 7)
Week 10
Week 11
Week 10
Week 12
Week 11
Week 12
Week 1
Week 2
Week 1
Week 3
Week 2
Week 4
Week 3
Week 5
Week 4
Week 6
Week 5
Week 7
Week 6
Week 8
Week 7
Week 9
Week 8
Week 9
Average Average
change change
1 Ukraine 1 USA
2 Sweden 2 India
3 Korea 3 Korea
4 Ontario 4 Ontario
5 USA 5 Germany
6 Germany 6 Brazil
7 Brazil 7 Sweden
8 UK 8 UK
9 France 9 Ukraine
10 India 10 France
-28% 12% -31% 15%
12 generation (March 16–June 7) relative to 2019
Weekly change in low carbon electricity
Nuclear electricity generation Solar and wind electricity generation Other renewable electricity generation
10
11
10
12
11
10
12
11
12
k0
k1
k0
k2
k1
k0
k1
k3
k2
k4
k3
k2
k5
k4
k3
k6
k5
k4
k7
k6
k5
k8
k7
k6
k9
k8
k7
k9
k8
k9reliable globally. Nonetheless, nuclear generators swiftly of 2020, the US EIA’s Short-Term Energy Outlook saw
adapted to the changed market conditions. Faced with the share of nuclear generation increasing by more than
significant decreases in demand, nuclear generators one percentage point compared to 2019, despite the
curtailed output to maintain the grid stability. Along general disruptions from the crisis. The performance
with other measures, this has enabled grid operators of nuclear power demonstrates how it can support
to maintain a reliable system and largely avoid supply the transition to a resilient, clean energy system well
disruptions Weekly despite
changethe challenging
in electricity conditions,
demand relative to 2019 beyond thechange
Weekly COVID-19 recovery
in electricity phase.
demand relative to week
(March 16-June 7) prior lockdown (March 16-June 7)
while also accommodating increased shares of low-
Despite the demonstrated performance of a
Week 10
Week 11
Week 10
Week 12
Week 11
Week 12
cost, variable renewable generation. In France, EDF
Week 1
Week 2
Week 1
Week 3
Week 2
Week 4
Week 3
Week 5
Week 4
Week 6
Week 5
Week 7
Week 6
Week 8
Week 7
Week 9
Week 8
Week 9
Average cleaner energy system through the crisis to provide
Average
increased
change
the periodicity of its load following operations change
competitive, reliable, low carbon electricity when
to accommodate Ukraine variable renewable generation (EDF, USA
1 1 needed, challenges remain in both mid and long
2020).
2 In the UK, nuclear played a big part in almost
Sweden 2 India
terms. Combined with the broader financial fallout
eliminating
3 coal generation for over two months (Fig. 9,
Korea 3 Korea
of the crisis on national and corporate budgets, as
mid 4panel) (Cockburn,
Ontario 2020). EDF Energy was able to 4 Ontario
well as latent risks associated with supply chain
respond
5 to the USAneed of the grid operator by curtailing 5 Germany
reorganizations, current conditions could impede the
sporadically
6
the generation of its Sizewell B reactor to
Germany 6 Brazil
7 7
required investments in the clean energy transition,
ensure stability of the electricity grid. In the Republic of
Brazil Sweden
8 UK 8 with longer
UK term consequences on the achievement of
Korea, the share of nuclear generation rose by almost 9
9 France 9 climate goals.
Ukraine
percentage points during the pandemic. For the whole
10 India 10 France
Figure 9 – Weekly change in low carbon electricity generation (March 15–June 6) relative to 2019 in selected jurisdictions (Top panel);
Change in nuclear, solar-28%
and wind generation market shares since
12%
start of lockdowns -31%
(mid panel); Average impact on 2020 15%
electricity
prices vs 2019 before and after lockdown starts10
Weekly change in low carbon electricity generation (March 16–June 7) relative to 2019
Nuclear electricity generation Solar and wind electricity generation Other renewable electricity generation
Week 10
Week 11
Week 10
Week 12
Week 11
Week 10
Week 12
Week 11
Week 12
Week 0
Week 1
Week 0
Week 0
Week 2
Week 1
Week 3
Week 2
Week 1
Week 4
Week 3
Week 2
Week 5
Week 4
Week 3
Week 6
Week 5
Week 4
Week 7
Week 6
Week 5
Week 8
Week 7
Week 6
Week 9
Week 8
Week 7
Week 9
Week 8
Week 9
Average
change
1 Ukraine
2 Brazil
3 Korea
4 Sweden
5 UK
6 France
7 India
8 Ontario
9 Germany
10 USA
-50% 211%
5%
Lower nuclear and Higher nuclear
Change share of wind & solar
Ukraine
generation (% -age points)
higher wind & solar and wind & solar
Brazil
3% USA
Indi
India
France Korea, Rep. of
0%
Germany
UK
Ontario
-3%
Lower nuclear Sweden Higher nuclear and
and wind & solar lower wind & solar
-5%
-10% -8% -5% -3% 0% 3% 5% 8% 10%
Change share of nuclear generation (% -age points)
Average electricity price in 2020 vs 2019
0%
After lockdown
start
-20%
-40%
Before lockdown
start
-60%
-80%
S. California Mid-Atlantic UK (GB) Ontario Germany France Sweden
(SP-15) (PJM) (SE1)
13MORE FLEXIBLE SYSTEMS TO ENABLE THE TRANSITION
Tomorrow’s electricity systems, the backbone In France, flexible operations of the extensive
of broader energy networks, will require flexible nuclear fleet accommodate the variability of other
oversight to maintain reliable and clean power electricity sources, a growing trend among nuclear
services. Electricty systems will be inherently more nations (Patel, 2019). Between 9-12 May 2020, nuclear
distributed, embedding both large and smaller production varied by 10 GW, mobilizing 44% to 60%
production units tapping the full potential of local and of its installed capacity, far from nominal power (Fig.
clean energy sources – By 2070, 3 600 GW of rooftop 10, ). Similar patterns albeit with smaller amplitude
solar PV coud be integrated into buildings envelopes emerge from nuclear plants in e.g. Germany, Slovakia,
(IEA, 2020e) – and using long distance transmission Czech Republic, Belgium, Finland, Switzerland,
networks to monitor system imbalances (Oudalov, Hungary and the United States. Exports are minimized
2020). Digital technologies will be increasingly when electricity spot prices are the lowest (Fig. 10, ).
important to monitor the system complexity, incl. real- Gas peaking units are sporadically mobilized when
time consumer behavior and flexible storage. higher levels of demand kick in (Fig. 10, ).
A closer look at electricity mixes in France and Portugal’s system flexibility and its security of
Portugal shines a light on two polar approaches to supply hinge on large pumped storage capacities
system flexibility. Mix compositions differ, but both and its integration with the Spanish grid. On 9 May
countries already feature large shares of dispatchable 2020, a surge of wind and solar generation and cheap
low carbon electricity sources. Both countries also aim imports supplied large electricity needs (Fig. 10, ).
for further integration of variable sources of electricity. As wind died down, solar power plummeted, and trade
France’s carbon intensity of electricity is under 50 gCO2 cut off by high import prices, hydropower took over at
per kWh, i.e. ten times less than the G20 average while full capacity (Fig. 10, ). On May 12, a new peak in
Portugal’s lies at around 250 gCO2 per kWh, close to demand was met with hydropower and fossil fuel units
the European Union’s average (ICTP, 2018; EDP, 2018). operating at full capacity (Fig. 10, ).
Figure 10 – Power generation mixes and spot prices of electricity France (left panel) and Portugal (right panel), 9-12 May 202011
30 30
20 20
EURO per MWh
EURO per MWh
10 10
0 0
-10 -10
France Portugal
60 8
Net Imports
Gigawatts
Gigawatts
30 Maximum 4
Minimum nuclear
nuclear generation
generation 37GW
27GW
0 0
Net Exports
Net Exports
Max Energy stored
Min
nuclear gen
nuclear gen
37GW
27GW
9 May 20 10 May 20 11 May 20 12 May 20 9 May 20 10 May 20 11 May 20 12 May 20
00:00 - 01:00
06:00 - 07:00
12:00 - 13:00
18:00 - 19:00
00:00 - 01:00
06:00 - 07:00
12:00 - 13:00
18:00 - 19:00
00:00 - 01:00
06:00 - 07:00
12:00 - 13:00
18:00 - 19:00
00:00 - 01:00
06:00 - 07:00
12:00 - 13:00
18:00 - 19:00
00:00 - 01:00
06:00 - 07:00
12:00 - 13:00
18:00 - 19:00
00:00 - 01:00
06:00 - 07:00
12:00 - 13:00
18:00 - 19:00
00:00 - 01:00
06:00 - 07:00
12:00 - 13:00
18:00 - 19:00
00:00 - 01:00
06:00 - 07:00
12:00 - 13:00
18:00 - 19:00
Thermal (fossil and Energy storage (Pumped
Hydropower Nuclear Solar Wind Regional electricity trade
biomass) hydro)
14The Iberian Peninsula grid operates in relative also operated in continental Europe. The International
isolation due to a lack of interconnectors with the Hydropower Association sees potential for a 50%
rest of continental Europe. The proposed Biscay increase in pumped storage capacity within ten
Gulf interconnector is expected to fill this gap, at an years. Such projects developments and their uneven
estimated cost of EUR1.9 billion and annual benefits geographical distribution remain insufficient to
in the order of EUR250-290 million (EC, 2016). The absorb future demand shocks, avoid curtailment, and
innovative Frades II pumped storage station also accommodate the system integration of fast-growing
plays a key role in the system stability: Variable speed non-dispatchable capacities.
turbines allow for frequency regulation (Larson, 2018).
The ongoing physical and digital transformations
A large pumped-hydro project under construction on
require the development of additional flexibility
the Tâmega river will alleviate the reliance on coal by
options. Solution developers are now turning
2023 and will help achieve the swift decarbonization of
to innovative energy storage solutions. The US
the Portuguese electricity sector.
Department of Energy recorded almost 1,300 projects
As shown by the previous examples, historically, worldwide covering a wide array of technological
network operators have ensured market clearance options, 80% of which are operational (Fig. 11, right
thanks to regional interconnectors, dispatchable panel). With more than 40% of the counts, lithium-
power generation units, including natural gas ion battery designs have become the most common
assets, but also pumped storage hydropower source of storage capacity. They now offer a full range
plants. Hydropower plants equipped with pumped of services across various timescales. Their flexibility
storage have long been instrumental to match and their ability for quick smoothing and firming of
available sources of electricity supply with customers’ electricity production have raised interest among
needs. Almost 170GW of pumped storage capacity operators of variable renewables sources. Lithium-ion
is operated worldwide, storing up to 9,000 gigawatt batteries are also becoming increasingly capable of
hours of electricity each year, equivalent to a third of performing scheduled time shifting of renewables over
global generation (Fig. 11, left panel). Almost half of longer durations, depending on economic conditions
these power plants are located in China, the United and local regulations.
States and Japan. Smaller yet significant capacities are
Figure 11 – Global mapping of energy storage capacities (left panel); Project developments of emerging storage technologies (right
panel)12
Other countries
Other storage
United States
Korea, South
Total number of projects: 1,269
Switzerland
Germany
Electro-Chemical
France
Japan
China
Compressed Air
Spain
India
Italy
Other Ba�ery
Molten Salt
100%
Lithium-Ion
Flywheel
Ba�ery
Other
(22%)
(13%)
(15%)
(42%)
(1%)
(4%)
(3%)
Technology breakdown
75%
50%
Operational Under Contracted Announced
(1030) construction (76) (152)
Avg. (11)
project 6 MW 56 MW 9 MW 13 MW
25%
size
Project destination
0%
0% 16% 31% 45% 67% 94% 100%
High Upper Lower Low
Pumped storage global capacity 190GW 9GW Income Middle Middle Income
(89%) Income Income (2%)
■ Contracted ■ Under ■ Announced ■ Operational
(7%) (2%)
Construction
15The fast-evolving energy storage landscape hundred gigawatts of hydropower capacity built since
suggests significant potential for scalability. The 2010 and fifty nuclear reactors under construction
average project size of lithium-ion battery projects corresponding to fifty-three gigawatts of new capacity)
(6MW) remains small compared with other types will strengthen the security of supply.
of storage technologies. But utility-scale lithium-
The innovation path and the falling cost of battery
ion systems with capacities greater than 10 MW and
systems give room for exponential growth in the
increasing storage durations have been commissioned
coming years. In a decade, the cost of a lithium-ion
worldwide in recent years. Some plants in California
1 kWh battery pack — enough capacity to propel an
can run up to four hours (Research Interfaces, 2018).
electric vehicle for six kilometers — saw more than a
Compressed air solutions and molten salt thermal
7-fold decrease, down to $156. The storage capacity
storage, a highly efficient process for 10-hour storage
installed globaly ramped up from 1 GW to over 10 GW in
or more, and best combined with large solar farms, are
less than three years. Bloomberg New Energy Finance
fewer but much larger in scale, in the order of 60-70
sees the $100 per kWh threshold reached within the
MW (Dieterich, 2018). Overall, the average capacity
next three years (BNEF, 2019). However, standalone
of the storage projects announced is more than 50%
applications remain costly to run outside peak hours.
larger the operational projects.
Once combined with solar PV systems, the levelized
Energy storage is vital for the cost-effective cost of electricity — a suitable metric to assess the
transition towards decarbonized electricity competitiveness of baseload generation sources —
systems. Battery storage installations are expected falls under $100 per MWh (Fig. 12, right panel). Against
to become standard components of energy this backdrop, the International Energy Agency projects
infrastructures. As illustrated in previous sections, around 220 GW of capacity installed globally by 2030
clean and non-dispatchable electricity has gained a lot of to accompany the aggressive deployment of solar and
ground globally in ten years, driven by strong innovation wind and meet the Paris Agreement objective. This is
and various schemes to guarantee operators’ revenues. half of the 2030 requirements in pumped-hydro capacity
One thousand gigawatts of new capacity have been alone (IRENA, 2020b). Some projects recently stalled
connected to the grid since 2010, with strides also made due to the pandemic but market interest remains strong.
off the grid in South Asia and Africa (Fig. 12, left panel). Wood Mckenzie, among other observers, predicts that
Variable renewables, now on par with conventional wind and solar, backed with storage solutions, are
sources of power, have established themselves as low- poised to dominate Europe’s power grid by 2030 thanks
risk options for governments and investors to realize to attractive risk/return profiles and despite increasing
their decarbonization objectives. They will live up to exposure to power market conditions (Wood Mckenzie,
their promise only with competitively priced storage 2020). The electrification of mobility services will also
solutions that can maintain overall system reliability. boost the emergence of the storage industry, beyond
The progression in dispatchable electricity (incl. three stationary applications in the power sector.
Figure 12 – Market dynamics for batteries and other low carbon options, 2010-201913
Dispatchable Non-dispatchable
Nuclear renewables renewables Unsubsidized levelized cost of storage
2019
1200 Commercial &
Industrial
(Standalone)
392GW 1,325GW 1,209GW
900
US Dollar per MWh
Residential
(PV+Storage)
2010
600
Commercial &
Industrial
(PV+Storage)
375GW 1011GW 223GW LCOE Hydro Wholesale
300 LCOE Gas
Nuclear Hydro Onshore wind Wholesale
LCOE Nuclear (LTO) (PV+Storage)
Biomass Offshore wind
Other Solar photovoltaic 0
Concentrating
2019 2020 2019 2020 2019 2020 2019 2020 2019 2020
solar power
16You can also read


