WESTERN UNION FINANCIAL SERVICES (CANADA), INC. AGENT ANTI-MONEY LAUNDERING COMPLIANCE MANUAL
←
→
Page content transcription
If your browser does not render page correctly, please read the page content below
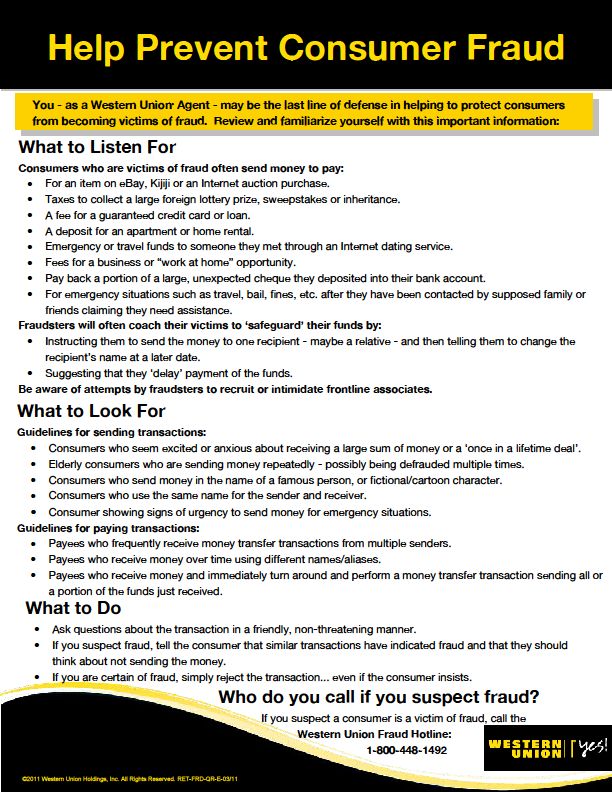
WESTERN UNION FINANCIAL SERVICES
(CANADA), INC.

AGENT ANTI-MONEY LAUNDERING
COMPLIANCE MANUAL

May 2012

The WESTERN UNION name, logo and related trademarks and service marks, owned by Western Union
Holdings, Inc., are registered and/or used in the U.S. and many foreign countries. This material is
confidential and is proprietary to Western Union and is not to be reproduced, disclosed, or used except in
accordance with program license or other written authorization of Western Union. Any use, copying,
manipulation, or reproduction of Western Union trademarks, logos, or material created by Western Union,
its subsidiaries, affiliates or its business units, in whole or in part in any medium for any purpose
whatsoever, is strictly prohibited without the prior written permission of Western Union.
Table of Contents

Overview of Policies, Procedures and Requirements .............................................................. 4
Compliance Officer Responsibilities ....................................................................................... 5
AML Compliance Policies and Procedures .............................................................................. 7
  AML Compliance Policy ............................................................................................................... 7
  Suspicious Transaction Referral/Report Policy ........................................................................... 8
  Employee Training Policy .......................................................................................................... 10
  Identification and Record Keeping Requirements .................................................................... 11
  Compliance Monitoring Policy .................................................................................................. 13
  Splitting Transaction Policy ....................................................................................................... 14
  Government Sanctions and Interdiction Policy ........................................................................ 15
AML Compliance Training .................................................................................................... 16
  Introduction .............................................................................................................................. 16
  Overview of Money Laundering and Terrorist Financing ......................................................... 17
  What Is Money Laundering? ..................................................................................................... 17
  The Risks of Money Laundering ................................................................................................ 17
  The Basic Stages of Money Laundering: ................................................................................... 18
  What Is Terrorist Financing? ..................................................................................................... 19
  Penalties for Money Laundering ............................................................................................... 19
  Tipping Off................................................................................................................................. 19
  Key Points on Money Laundering and Terrorist Financing ....................................................... 20
  Proceeds of Crime (Money Laundering) and Terrorist Financing Act ...................................... 20
  General Requirements: ............................................................................................................. 21
  How These Requirements Apply to You: .................................................................................. 21
  Key Points - Proceeds of Crime (Money Laundering) and Terrorist Financing Act .................. 22
  Record Keeping Requirements ................................................................................................. 22
   Record Keeping Requirements for Money Transfers ........................................................ 22
Record Keeping Tips ............................................................................................................ 24
Acceptable Forms of Identification ...................................................................................... 24
  Key Points – Recording Keeping Requirements ........................................................................ 25
  Reporting Requirements ........................................................................................................... 26
Reporting Requirements ...................................................................................................... 26
Suspicious Transaction Referrals/Reports ............................................................................ 26
  What Is Suspicious Activity? ..................................................................................................... 27
Red Flags............................................................................................................................. 27
   Structuring: ................................................................................................................. 29
  Completing a Suspicious Transaction Referral/Report ............................................................. 30
  Helpful Tips about the Information for Suspicious Transaction Referrals/Reports ................. 30

© 2008-2010 Western Union Holdings, Inc. All Rights Reserved. Confidential and Proprietary                                                     2
Submitting and Keeping Suspicious Transaction Referrals/Reports ........................................ 31
  Monitoring Responsibilities ...................................................................................................... 31
  Monitoring Hints ....................................................................................................................... 32
  Key Points – Reporting Requirements ...................................................................................... 33
Fraud Prevention ................................................................................................................. 33

© 2008-2010 Western Union Holdings, Inc. All Rights Reserved. Confidential and Proprietary                                                 3

Overview of Policies, Procedures and Requirements
This Agent Anti-Money Laundering Compliance Manual ("Manual") is issued on behalf of
Western Union Financial Services (Canada), Inc. (“Western Union”). Western Union is
mentioned throughout this manual. The Manual describes the anti-money laundering
compliance requirements applicable to Western Union in Canada. The Manual also includes a
quick reference card with a summary of the identification, record keeping and reporting
requirements. The quick reference card is included and intended to be a guide that is kept in a
safe, convenient place for easy reference.
The Manual is organized into four sections that you need to be aware of as an Agent. The
sections are as follows:
Responsibilities:
o Each Agent location must designate a person responsible for overseeing the
implementation and adherence of the policies, procedures and requirements set forth
in this Manual. This person is referred to as the Compliance Officer.
Policies and Procedures:
o Policies are general statements of broad intent and direction, whereas procedures are
more detailed instructions for day-to-day activities. Policies and procedures may be
updated from time to time as the result of changes in laws, regulations, business
operations, or Western Union policy.
Training:
o The Compliance Officer must ensure that all employees who handle transactions are
trained on anti-money laundering as well as policies and procedures included in this
Manual. The training section has been designed to help you provide the required
training to your employees.
Forms:
o This Manual includes report referral forms, a monitoring log and a training log. These
can be removed and copied by the Agent as needed. If additional copies of these forms
are required by the Agent, they can be obtained by contacting your local representative
or by calling Western Union at 1-800-235-0000
This Manual outlines the requirements of an Agent. Your Agent location may choose to
implement additional internal requirements in keeping with the best practices of your business,
so long as such requirements are not inconsistent with those set forth in this Manual.
© 2008-2010 Western Union Holdings, Inc. All Rights Reserved. Confidential and Proprietary 4
Compliance Officer Responsibilities

        The Compliance Officer is the person responsible for compliance in your Agent location. This
        person is responsible for overseeing and monitoring adherence by your location with the
        policies, procedures and requirements set forth in this Manual.

        The duties and responsibilities of the Compliance Officer are outlined below and may be in
        addition to the other duties and responsibilities of the appointed individual.

        The Compliance Officer will work in collaboration with Western Union and has the following
        specific responsibilities:

        Training

        1. Ensures that new employees complete anti-money laundering compliance training.

        2. Ensures that all employees receive, at minimum, annual refresher training on anti-money
           laundering compliance, including report referrals and identification requirements.

        3. Ensures that all employees review compliance training and educational materials provided
           periodically by Western Union.

        4. Provides supplemental training to employees as needed to address compliance deficiencies
           with the policies and procedures that are noted through monitoring, regulatory
           examinations or compliance reviews.

        5. Ensures that initial and ongoing training efforts are documented for each employee. A
           Training Log has been provided and is available in this Manual as an example of training
           documentation.

        Monitoring

        1. Ensures that employees follow policies and procedures at all times when engaging in
           Western Union transactions.

        2. Periodically reviews daily reports, the Compliance Monitoring Report, forms and/or printed
           receipts to ensure proper completion and accurate entry of consumer information as well as
           proper identification acceptance by Agent employees.

        3. Ensures that employees identify and refer/report suspicious activity to Western
           Union/FINTRAC using the Suspicious Transaction Referral/Report process for both

© 2008-2010 Western Union Holdings, Inc. All Rights Reserved. Confidential and Proprietary             5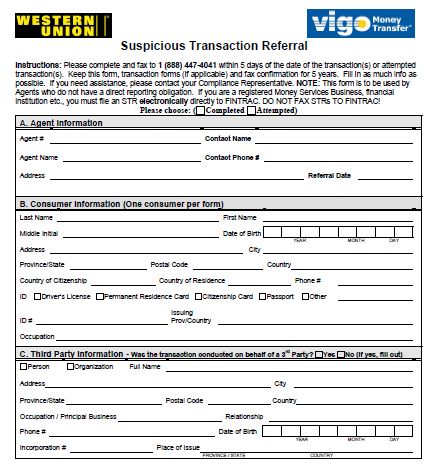
completed and attempted transactions. (Note: If you are an MSB or other reporting entity,
            you must complete a Suspicious Transaction Report and file electronically with FINTRAC.

        4. Reviews all Suspicious Transaction Referrals/Reports for accuracy, completeness and timely
           submission.

        5. Develops and implements appropriate corrective action for any deficiencies identified
           during the monitoring process.

        6. Educates staff on observable behaviours that could warrant Suspicious Transaction
           Referrals/Reports.

        Record Keeping

        1. Ensures that the Manual is maintained in an accessible location and that any updates
           received from Western Union are incorporated into the Manual.

        2. Maintains the AML-related monitoring and training records.

        3. Ensures that all required reports/referrals and supporting documents are retained for 5
           years.

        4. Ensures all completed transaction forms and receipts are kept for a minimum of 6 months
           and then destroyed unless the forms were involved in a STR report.

        Other

        1. Serves as the primary contact with Western Union Compliance Department and with
           Canadian governmental officials and staff during regulatory audits or compliance
           examinations (if applicable).

        2. Serves as the primary contact for Agent Compliance Reviews, responds to compliance
           review findings, and implements any required corrective actions.

        3. Coordinates the process for identifying suspicious activity, completing Suspicious
           Transaction Referrals/Reports for completed or attempted suspicious transactions and
           maintaining supporting documentation for 5 years.

        4. Ensures that every employee who conducts money transfer transactions has a separate and
           unique user ID and password and that password are kept confidential.

© 2008-2010 Western Union Holdings, Inc. All Rights Reserved. Confidential and Proprietary              6
AML Compliance Policies and Procedures
AML Compliance Policy
Agents and their employees must comply with anti-money laundering policies
and procedures, which may be updated from time to time.
All employees conducting transactions must know and comply with the policies, procedures
and requirements set forth in this Manual, as updated from time to time.
All employees conducting transactions must have and use their own separate user ID and
password for the money transfer system. Employees may not share user IDs or passwords
or conduct transactions using another employee’s user ID.
Records of completed employee training and compliance monitoring must be documented
and retained for a minimum of 5 years.
Suspicious activity identified during interactions with a consumer must be referred to
Western Union or reported directly to FINTRAC for MSBs and other reporting entities as
described herein. Western Union will file reports with FINTRAC based on such referrals as it
deems necessary and appropriate. Agents are required to keep copies of referrals/reports
submitted and any supporting documentation including proof of submission for 5 years.
© 2008-2010 Western Union Holdings, Inc. All Rights Reserved. Confidential and Proprietary 7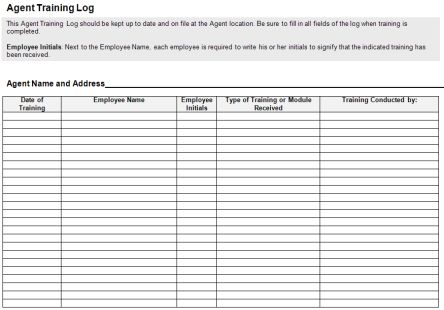
Suspicious Transaction Referral/Report Policy
Agents and their employees will take reasonable steps to identify suspicious activity and
submit Suspicious Transaction Referrals/Reports to Western Union/FINTRAC as appropriate.
The Agent should attempt to get as much information as possible about the consumer(s);
however, the Agent shall not inform a consumer that a Suspicious Transaction
Referral/Report is being completed. If the Agent thinks that asking for additional information
will tip off a consumer about a report, do not ask for further information. This requirement
applies to completed as well as attempted transactions that are suspicious.
SUSPICIOUS TRANSACTION REPORT REFERRAL PROCEDURE:
A Suspicious Transaction Referral/ Report must be submitted to Western Union/FINTRAC for
any completed or attempted transaction for which there is a reasonable basis to suspect
that the transaction or attempted transaction is related to a money laundering or terrorist
financing offence. A copy of the Suspicious Transaction Referral form is located in the Forms
section of this Manual. (Registered MSBs and other reporting entities would be required to
file an STR directly with FINTRAC. AGENTS THAT ARE NOT REPORTING ENTITIES (ie grocery
stores, convenience stores, any location that does not offer a regulated product of their
own) MUST NOT FAX OR SUBMIT INFORMATION DIRECTLY TO FINTRAC. THIS
INFORMATION MUST COME TO WESTERN UNION FOR REVIEW AND SUBMISSION.
Suspicious activity includes possible attempts to launder money, structure transactions to
avoid reporting or record keeping requirements, and/or terrorist financing activities.
Employees must take reasonable measures to obtain as much information as possible for
completion of the Suspicious Transaction Referral/Report, keeping in mind that you do not
want to tip off the consumer that a referral is being completed. If you think that the
consumer will be tipped off to your suspicions, do not ask additional questions.
Under no circumstances may an employee inform a consumer that a Suspicious Transaction
Referral/Report is being submitted.
Suspicious Transaction Referrals/Reports are to be reviewed for completeness and accuracy
prior to submission to Western Union. The referral form may be amended from time to time
by Western Union as it deems necessary to meet its regulatory and legal obligations.
The Compliance Officer will fax the completed Suspicious Transaction Referral form to
Western Union at 1-888-447-4041 as soon as possible and within 5 days of detecting the
suspicious activity. Registered MSBs and other reporting entities should file the report
directly with FINTRAC electronically within 30 days of identifying the suspicious activity.
© 2008-2010 Western Union Holdings, Inc. All Rights Reserved. Confidential and Proprietary 8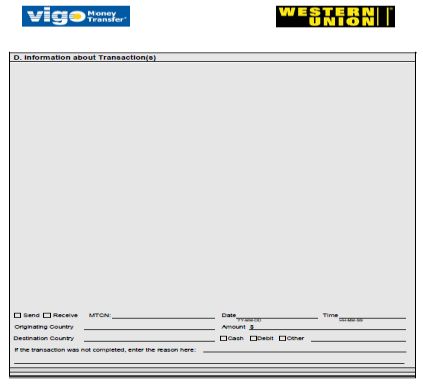
The Compliance Officer will serve as the contact person should Western Union have any
questions about Suspicious Transaction Referrals/Reports.
Copies of Suspicious Transaction Referrals/Reports and evidence of submission to Western
Union/FINTRAC, along with all supporting information, must be retained for a period of 5
years.
Examples of Suspicious Activity:
The consumer displays unusual behaviour or provides potentially improper documentation. For
example, if the consumer:
is nervous, rushed or aggressive
is reluctant to show identification
provides identification that seems unusual, false or altered
presents different identification or address each time they complete a money transfer
spells their name differently or uses a different name each time they complete a money transfer
Transactions that do not make economic sense:
A sender regularly sends money home once a month and suddenly begins sending larger
amounts every week to other people
A sender comes in more than once during the same day or over several days and sends amounts
just under the identification threshold to different people who are in the same geographic area
Large and regular transactions that cannot be identified as legitimate, especially if sent to
countries associated with the production or processing of narcotics or other illegal drugs
A consumer who receives a number of small transactions on the same day, or within several
days, and subsequently sends one or more transactions of about the same total amount to
another person
Refusing Transactions:
If you are uncomfortable about a transaction, ask for help from a more experienced associate, your
manager or Compliance Officer. You have the right to refuse a transaction. Whether a transaction is
completed or attempted, it is always best to report your concerns/suspicions using the Suspicious
Transaction Referral/Report)
© 2008-2010 Western Union Holdings, Inc. All Rights Reserved. Confidential and Proprietary 9Employee Training Policy
All Agent employees who conduct transactions must receive Anti-Money
Laundering training.
EMPLOYEE TRAINING PROCEDURE:
Western Union will provide AML training materials for Agents and their employees on:
o Money laundering, terrorist financing and laws and regulations designed to combat
them, including applicable sections of the PCMLTFA and its implementing regulations.
o Suspicious activity identification and the Suspicious Transaction Referral process
o Identification and record keeping requirements
o Western Union policies and procedures
Initial AML compliance training for current employees must occur promptly upon your becoming an
Agent and prior to employees conducting transactions.
New employees must receive AML compliance training prior to conducting money transfer
transactions.
At least annually, all employees who conduct money transfer transactions should receive AML
refresher compliance training.
Ongoing additional AML compliance training should occur as new information or requirements
become available or if compliance issues are identified. In addition, Western Union may periodically
provide educational materials, such as newsletters and bulletins that discuss compliance
requirements or anti-money laundering issues that should be communicated to staff at Agent
locations and documented.
Evidence of completed AML compliance initial and refresher training must be documented, and such
documentation must be retained by the Agent location for 5 years. A training log is included in the
Forms section of this Manual for documenting training.
© 2008-2010 Western Union Holdings, Inc. All Rights Reserved. Confidential and Proprietary 10Identification and Record Keeping Requirements
Agents and their employees must obtain and record all consumer information
required by identification and record keeping policies and procedures. All such
information obtained by the Agent will be retained by Agent. This includes all
forms and receipts, referrals/reports and any supporting documentation.
All such information obtained by Agent will be retained by Agent. Unless otherwise specified, money
transfer transaction forms (“To Send Money,” “To Receive Money” and “Quick Collect”) and receipts are
to be retained for a period of 6 months and then destroyed. However, if a money transfer transaction
form relates to a report/referral, the form should be retained for 5 years along with the referral/report
itself.
ACCEPTABLE FORMS OF IDENTIFICATION:
When you are required to verify a consumer’s identity by reviewing an identification document, AML
policy requires that the identification document:
Is government issued
Includes a photo of the consumer
Is current (not expired)
Examples of acceptable forms of identification include a provincial driver’s license, a Canadian or foreign
passport, a Permanent Resident Card, or a Quebec Issued Health Card. (Note: Social Insurance Number
and Health Cards from Ontario, Manitoba and PEI are specifically NOT accepted.) On the following page
is a list of the information required at various thresholds:
DATA PROTECTION/CUSTOMER PRIVACY
In addition to meeting your recordkeeping requirement, you should protect your customer data.
Protecting customer data includes:
Shredding forms or any documents containing customer and/or transaction information
after the required retention period ends.
Maintaining customer records in a secure location. This can include forms, Suspicious
Transaction referrals and monitoring information that includes customer data.
© 2008-2010 Western Union Holdings, Inc. All Rights Reserved. Confidential and Proprietary 11IDENTIFICATION AND RECORD KEEPING REQUIREMENTS:
Employees conducting Money Transfer transactions must obtain and record all information required by
identification and record keeping policies and procedures. Employees must ensure that all required
information is contained on the appropriate money transfer transaction form (“To Send Money,” “To
Receive Money” or “Quick Collect”), receipts and/or entered into the Money Transfer system.
It is important to make sure the information contained in the ID documents matches that provided by
the consumer. If information does not match, a second piece of ID should be requested. If not available
or does not provide confirmation, the transaction should be refused.
MONEY TRANSFER
Identification and Record Keeping Requirements
Dollar Threshold Requirement
Less than $1,000 send Send transactions: Obtain and record the name,
address and telephone number of the Sender.
and
Receive transactions: Obtain and record the name,
below $300 receive address and telephone number of the Receiver. In
addition, either review the Receiver’s Photo ID or obtain
the answer to the test question.
$1,000 or more for SEND transactions or Record the Sender’s or Receiver’s name and address,
over $300 for RECEIVE transactions telephone number, date of birth, country of birth and
occupation.
Verify the identity of the Sender or Receiver by
reviewing current, government-issued, photo
identification (ID) – such as a driver’s license or passport.
Write down the ID type, number, place of issuance and
expiry date (if applicable)
In addition to the $1,000 requirements above, the Sender
$7,500 or more in single SEND must complete an interview with a Western Union
transaction Customer Service Operator:
The interview process is very important as it protects the
consumer against possible fraudulent transactions and
also collects information required.
Transactions should never be “split” to avoid the
interview process.
© 2008-2010 Western Union Holdings, Inc. All Rights Reserved. Confidential and Proprietary 12Compliance Monitoring Policy
The Compliance Officer will periodically monitor compliance with the policies,
procedures and requirements set forth in this Manual.
COMPLIANCE MONITORING PROCEDURE:
The Compliance Officer must monitor and document a review of transaction activity
conducted at his or her location to verify that:
1. Where appropriate, Suspicious Transaction Referrals/Reports were completed
correctly and submitted to Western Union/FINTRAC within the required timeframe,
and copies along with any supporting documentation were retained at the Agent
location.
2. Information and identification requirements were met and identification policies
were followed.
3. Where applicable, Send and Receive Forms and receipts were completed correctly
and information on the forms matched the printed money transfer receipts.
4. All record keeping requirements have been complied with.
5. Existing employees received Western Union refresher training and new employees
successfully completed Western Union compliance training.
6. All employees have and are properly using separate user IDs and passwords for
conducting Western Union money transfer transactions.
7. Monitoring daily activity reports in conjunction with reconciliation of money
transfers and identifying and reporting suspicious activity on the Suspicious
Transaction Referral/Report when applicable. Initialing or signing the reports as
evidence of review.
If monitoring discloses potential compliance issues, the Compliance Officer will identify the
cause of the potential issue and determine the appropriate corrective measures, if any, such
as additional training or clarification of procedures.
Evidence of monitoring Must be documented and retained for at least 5 years. You may use
the Monitoring Log attached to this manual to record your monitoring activities.
© 2008-2010 Western Union Holdings, Inc. All Rights Reserved. Confidential and Proprietary 13Splitting Transaction Policy
Agents and their employees must follow procedures for handling suspicious activity as
outlined in this Manual if it is determined that a consumer is splitting a transaction for
illegitimate reasons.
SPLITTING TRANSACTION PROCEDURE:
This splitting policy provides guidance regarding the handling of two or more transactions that, whether
intentionally or unintentionally, avoid record keeping requirement or identification thresholds.
The term “split” is defined as:
A transaction that is broken apart for the purpose of decreasing the amount of each single transaction.
The activity of splitting or separating one transaction into two or more transactions can be done for
legitimate reasons or it can be done for illegitimate reasons.
Example of splitting transactions:
Joe, the sender, wishes to send $3,000 to a criminal associate in Europe; however Joe is advised he
needs to provide photo identification and address information in order for the transaction to be
processed. Subsequently, Joe sends three separate transactions for $999 each, and therefore avoids
showing any identification documents.
If a sender chooses to split a transaction so that is below the identification threshold, or the sender
comes in regularly to send funds just below the identification threshold, you may prompt the System
using the “Consumer ID” button in the Translink system or by selecting the “Show Compliance” link in
WUPOS and collect the consumer’s identification details. This should always be used if the sum of the
consumers transactions in a single visit total $1000 or more.
As an Agent, you can witness the consumer’s actions and are in a position to make a decision as to
whether the splitting is for a legitimate reason or not. Remember, you are able to ask for ID at any
amount and if it is felt that the purpose for splitting is for illegitimate reasons an STR should be filed.
.
© 2008-2010 Western Union Holdings, Inc. All Rights Reserved. Confidential and Proprietary 14Government Sanctions and Interdiction Policy
Various governments and governmental organizations prohibit businesses, including
money transfer service providers, from engaging in transactions with listed
individuals, entities or countries. Western Union screen transactions against
applicable lists of individuals and entities provided by such governments and
organizations. Western Union also screens transactions against lists of individuals
and entities with whom it has determined not to do business for a variety of reasons.
GOVERNMENT SANCTIONS AND INTERDICTION PROCEDURE:
The Western Union systems screen money transfer transactions against applicable lists of
people and entities with whom we are prohibited from doing business, as well as lists of people
and entities with whom we have determined not to business for various reasons.
If a match is identified, Western Union must research the transaction in more detail. In many
cases, consumers are required to provide additional identification or information about the
transaction. The required research may delay the release of the transaction for payment.
If you or a consumer has questions about this topic, please contact Western Union.
LAW ENFORCEMENT REQUESTS:
From time to time Western Union receives requests from Law Enforcement Agencies. If an Agent’s
employees receive such a request, they must forward it to their Compliance Officer or directly to the
Western Union Compliance Department.
© 2008-2010 Western Union Holdings, Inc. All Rights Reserved. Confidential and Proprietary 15AML Compliance Training Training is a critical component of an Anti-Money Laundering (AML) Compliance program. The following questions and answers will help you understand the training requirements. Who should take AML training? Every employee who is involved in money transfer transactions. Before selling any services, each employee should read the Anti-Money Laundering Training Modules included in this folder and correctly answer all of the AML Compliance Quiz questions. The Compliance Officer should use the answer key located at the back of the Training section for scoring each employee’s quiz. How often should employees be trained? As a part of ongoing training, employees should be retrained at least annually. How do I document employee training? We recommend that the Compliance Officer have each employee sign and date their Quiz and file them for future reference. The Agent Training Log should be used to document all employee Compliance training. This includes both the Quiz and any ongoing training, such as reading compliance articles in newsletters and other publications. How long do I have to keep employees training records? Training materials must be kept with your Compliance records for at least 5 years. Introduction This training is an important part of the Anti-Money Laundering (AML) Compliance Program. We provide the training to assist you in adhering to the requirements of our Compliance Program and to help you and your employees better understand how to protect your business operations from being used for illicit purposes. In addition to periodic training, the Compliance Program requires your following our policies and procedures and designating a Compliance Officer who is responsible for overseeing AML compliance at your Agent location. Training Modules: This packet contains four separate training lessons to assist you in training employees. The format allows training to be conducted in a group or individually. © 2008-2010 Western Union Holdings, Inc. All Rights Reserved. Confidential and Proprietary 16
Each lesson presents a different aspect of Anti-Money Laundering Compliance: Lesson One: Overview of Money Laundering and Terrorist Financing Lesson Two: Proceeds of Crime (Money Laundering) and Terrorist Financing Act Lesson Three: Record Keeping Requirements Lesson Four: Reporting Requirements Agent Training Log: This log will help you track and record your training. The log should be kept current and on file at your location. Be sure each employee initials the training log after completing the training. Overview of Money Laundering and Terrorist Financing What Is Money Laundering? Money laundering is the process of disguising the source of money that was obtained illegally in order to make it appear legitimate. Many types of criminal activity, such as drug trafficking, generate money for the criminal and his organization. In order to use that money without being detected, the criminal must disguise its origins and make it appear legitimate. Money laundering is the process by which the criminal does this. If successful, the criminal is able to use the criminal proceeds freely. How big a problem is money laundering? The International Monetary Fund estimates that C$900 billion to C$2.25 trillion of illegal money is circulating worldwide each year. So, you can see why Western Union devote significant resources to comply with the anti-money laundering regulations everywhere they do business. The Risks of Money Laundering It hurts our communities and our country. It damages our business reputation. It allows criminals and terrorists to use our financial system for illegal purposes. © 2008-2010 Western Union Holdings, Inc. All Rights Reserved. Confidential and Proprietary 17
The              Basic Stages of Money Laundering:

         Placement              Placement is the attempt to place illegally obtained funds in the
                                financial system without attracting attention.

                                A send transaction could be the placement of cash with an Agent
                                (e.g. Money from the sale of stolen goods/drug money). This is the
         Example of             initial stage and is very hard to establish. Western Union
         Placement              recommends that if you are suspicious of any activity at your
                                location, you should report it. Details of reporting Suspicious Activity
                                are covered later in this Manual.

                                Layering is the second stage of the money laundering process where
                                funds are moved around to hide them from their source. This
         Layering               “movement” often involves a complex series of transactions in order
                                to create confusion and complicate the paper trail.

                                A consumer might go into several different Agent Locations and
         Example of             complete the same or similar transactions in the hope of not being
         Layering               detected. If you notice this behaviour, you should bring it to the
                                attention of your Compliance Officer and Western Union by
                                completing a Suspicious Transaction Referral/Report.

                                Integration is the ultimate goal of the money laundering process.
                                Once the illegal funds are placed into the financial system and are
         Integration            insulated through the layering stage, they are used to buy goods and
                                services that appear as “legitimate” wealth.
         Example of
                                One or more consumers send several transactions to one receiver.
         Integration            This receiver collects the transactions and subsequently sends
                                another transaction or tries to invest in a legitimate product.

© 2008-2010 Western Union Holdings, Inc. All Rights Reserved. Confidential and Proprietary                 18
What Is Terrorist Financing? Over the last several years, combating terrorist financing has become an important part of most anti- money laundering efforts. Terrorists, like most criminals, try to conceal their activities (including their financing) to avoid detection. Terrorist financing is a little different than traditional money laundering because terrorists often finance their activities with money that was obtained legally. Terrorists know if they use illegally obtained money, they are more likely to be caught before they can use their money to fund their terrorist activity. What terrorists try to hide is the connection between themselves, their financing, and their terrorist activity. Let’s look at some examples to demonstrate the difference between money laundering and terrorist financing. Example of Money Laundering: Joe, by selling illegal drugs, generated a large sum of money. Now he must find a way to use the funds without attracting attention to his criminal activity. Joe attempts to hide the unlawful funds by transferring small amounts of money to various individuals who deposit it in bank accounts that Joe controls. Example of Terrorist Financing: A foreign organization on a government watch list needs to provide funds to its operatives for a terrorist act in Canada. The funders understand that sending large amounts of money, even legal money, will arouse suspicion. Therefore, they divide a large sum of into smaller amounts, which they transfer to associates claiming to be foreign college students living in Canada. These individuals posing as students then get the money to the operatives. Penalties for Money Laundering Ignoring “red flags” and not completing a Suspicious Transaction Report (STR) that indicates that funds could involve illegal activities can potentially expose a person or business to criminal penalties under a legal doctrine known as “willful blindness.” It is a crime to engage in a financial transaction knowing that it involves the proceeds of drug trafficking, tax evasion, terrorist activities or other illegal activities. Tipping Off It is a crime to advise an individual that you have filed a Suspicious Transaction Report based on their transaction activity or attempted transaction activity or other factors that make the activity suspicious. © 2008-2010 Western Union Holdings, Inc. All Rights Reserved. Confidential and Proprietary 19
Key Points on Money Laundering and Terrorist Financing
Money Laundering:
Begins with funds gained from crime
Attempts to wash dirty money so that it cannot be easily traced
Moves money through the financial system so it can later be used for
legitimate purposes
Terrorist Financing:
Often uses money acquired through legal means
Attempts to hide the connection between the funders of terrorism, their
money, and terrorist activity
Proceeds of Crime (Money Laundering) and Terrorist Financing Act
Both money laundering and the financing of terrorist activities are criminal offences under Canada’s
Criminal Code. However, the primary law governing the anti-money laundering and terrorist financing
obligations of financial institutions in Canada is the Proceeds of Crime (Money Laundering) and Terrorist
Financing Act (the “PCMLTFA”).
The PCMLTFA was originally enacted in 1991 to deal with money laundering by providing law
enforcement with a “paper trail” of certain financial transactions, such as those involving large amounts
of cash. In 2001, it was amended to deal with terrorist financing activities as well. In 2007, it was
expanded to bring Canada more fully in line with international anti-money laundering and terrorist
financing guidelines.
The PCMLTFA has three key objectives:
To detect and deter money laundering and the financing of terrorist activities and to facilitate
investigations and prosecution of the related offences;
To respond to the threat posed by organized crime by providing law enforcement officials with the
information they need to deprive criminals of the proceeds of their criminal activities;
To help fulfill Canada’s international commitments to fight multinational crime.
© 2008-2010 Western Union Holdings, Inc. All Rights Reserved. Confidential and Proprietary 20General Requirements:
In general, the PCMLTFA requires financial institutions, including “money services businesses,” to:
Establish and maintain an anti-money laundering compliance program,
File certain reports with the government
Maintain records of certain transactions, and
Ascertain client identity in certain situations.
The primary reports required by the PCMLTFA are (i) reports of suspicious transactions and attempted
suspicious transactions, (ii) reports of large cash transactions, and (iii) reports of large electronic funds
transfers.
Compliance with these requirements is overseen by the Financial Transactions and Reports Analysis
Centre (FINTRAC), which operates as part of the Ministry of Finance. In addition, FINTRAC collects and
analyzes these reports and refers cases of possible money laundering and terrorist financing to law
enforcement. Law enforcement uses information provided by FINTRAC to investigate and prosecute
those who may have engaged in illegal activity.
How These Requirements Apply to You:
As a money services business, Western Union is required to have an anti-money laundering compliance
program and to comply with the record keeping, reporting and client identification requirements of the
PCMLTFA. Agents must provide products and services in a manner that enables Western Union to meet
its legal obligations. Specifically, each Agent location is required to follow
operational and compliance policies and procedures which include, among other
things:
Obtaining and recording certain information when a consumer conducts
a money transfer. In many cases, compliance with these requirements
involves recording complete and accurate information according to
prompts on the transaction screen for money transfers.
Verifying the identity of consumers who are subject to the money transfer record keeping
requirements listed on the ID summary card provided to you.
Submitting a Suspicious Transaction Referral/Report to Western Union/FINTRAC for completed
or attempted transactions of any type that you believe are suspicious. (Note: If you are a
registered Money Services Business or other reporting entity you would be required to file a
Suspicious Transaction Report directly to FINTRAC.)
These requirements are discussed in more detail in the following training modules.
© 2008-2010 Western Union Holdings, Inc. All Rights Reserved. Confidential and Proprietary 21Key Points - Proceeds of Crime (Money Laundering) and
Terrorist Financing Act
The PCMLTFA sets record keeping, reporting and customer
identification requirements on money services businesses such
as Western Union.
Agents must follow Western Union’s policies and procedures so
that we all comply with requirements of the PCMLFTA.
Agents are required to obtain and record certain information
and review identification documents for money transfer
transactions at or above certain dollar amounts as indicated on
the ID Summary card.
Suspicious Transactions (Completed or Attempted) must be
referred to Western Union using the Suspicious Transaction
Referral. If you are a registered Money Services Business or
other reporting entity you would be required to file a Suspicious
Transaction Report directly to FINTRAC.
Record Keeping Requirements
Record Keeping Requirements for Money Transfers
Money Transfer Sends of less than $1000 and Receives under $300.
When you conduct a Money Transfer SEND transaction of less than $1000 or a Receive under $300, you
need to obtain and record the following information from the sender or receiver:
Name and address
Telephone number
In addition, for receive transactions you must review the Receiver’s Photo ID or obtain the
answer to the test question.
Money Transfer Sends of $1,000 or More and Receives over $300
When you conduct a Money Transfer SEND transaction of $1,000 or more, or RECEIVE over $300, you
need to obtain and record certain information and confirm the consumer’s identity by reviewing a
current, government-issued photo identification (ID) - such as a driver’s license. Specifically, you need
to see the ID and record the following information from the sender or receiver:
© 2008-2010 Western Union Holdings, Inc. All Rights Reserved. Confidential and Proprietary 22 Name and address
Telephone number
Date of birth
Country of birth
Occupation
The type of identification, its number, place of issuance and expiration date (if there is one)
In most cases, you can meet these requirements by making sure that you obtain all of the information
called for on the To Send or To Receive forms or by the money transfer system.
Money Transfers of $7,500 or More
When you conduct a Money Transfer SEND transaction of $7,500 or more, in addition to obtaining the
information mentioned above, the consumer will be interviewed by a Customer Service Operator during
which additional information will be obtained and updated into the Western Union system.
Summary
The following table summarizes the record keeping requirements for money transfers.
MONEY TRANSFER
Identification and Recordkeeping Requirements
Dollar Threshold Requirement
Less than $1,000 send Send transactions: Obtain and record the name, address and telephone
number of the Sender.
and
Receive transactions: Obtain and record the name, address and telephone
below $300 receive number of the Receiver. In addition, either review the Receiver’s Photo ID
or obtain the answer to the test question.
$1,000 or more for SEND Record the Sender’s or Receiver’s name and address, telephone number,
transactions or over date of birth, country of birth and occupation.
$300 for RECEIVE
transactions Verify the identity of the Sender or Receiver by reviewing current,
government-issued, photo identification (ID) – such as a driver’s license or
passport.
Write down the ID type, number, place of issuance and expiry date (if
applicable)
© 2008-2010 Western Union Holdings, Inc. All Rights Reserved. Confidential and Proprietary 23In addition to the $1,000 requirements above, the Sender must complete an
$7,500 or more in single interview with a Western Union Customer Service Operator:
SEND transaction The interview process is very important as it protects the consumer against
possible fraudulent transactions and also collects Third Party Determination
information required.
Transactions should never be “split” to avoid the interview process.
Record Keeping Tips
When obtaining information about a consumer’s occupation, make sure you get a specific occupation.
Answers such as “business,” “self employed,” or “manual labor” are not acceptable. You should ask for
more details, such as “owner of convenience store” or “self employed plumber.”
When obtaining a consumer’s address, do not accept a P.O. Box. Instead, you should obtain street
address information, including lot and concession (if applicable).
Acceptable Forms of Identification
As described above, you must review an acceptable form of identification when making money transfer
or money order transactions over certain dollar amounts. An acceptable form of identification is a:
Driver’s license
Passport
Quebec-Issued Health Insurance Card (only if offered by the consumer)
Other current Photo ID issued by provincial, territorial or the federal government
The identification document must be an original – a copy is not acceptable – and must contain a
photograph of the individual. In addition, it must be currently valid. For example, an expired driver’s
license would not be acceptable. A social insurance card is specifically NOT acceptable as an
identification document.
When you look at an ID, you should make sure the information is consistent with the information
provided by the Sender or Receiver (i.e., name, address, age). You should also compare the photograph
on the ID with the person in front of you. If the ID does not match or appears to be a forgery, you
should not accept it. If you don’t feel comfortable with the ID provided, ask for a second piece of ID to
confirm the consumer’s identity.
© 2008-2010 Western Union Holdings, Inc. All Rights Reserved. Confidential and Proprietary 24Key Points – Recording Keeping Requirements
The record keeping requirements for Money Transfers include obtaining
and recording information about consumers sending $1,000 or more and
receiving over $300.
Western Union will conduct an interview for money transfer transactions
that are $7,500 or more.
Acceptable IDs must be original, currently valid government issued
documents with a photograph, such as a driver’s license or passport.
© 2008-2010 Western Union Holdings, Inc. All Rights Reserved. Confidential and Proprietary 25Reporting Requirements
Reporting Requirements
One of the ways the PCMLTFA combats money laundering and terrorist financing is to
require financial institutions and other entities to take reasonable measures to detect and
report suspicious transactions and attempted transactions. Another is to require certain
entities to report receiving $10,000 or more in cash or for sending $10,000 or more out of
Canada or for receiving $10,000 or more in Canada from another country. In order for
Western Union to meet these requirements, Agents need to enter accurate information
into their money transfer system, and also to monitor their transactions and either refer
certain transactions to Western Union for reporting or in the case of a registered MSB or
other reporting entity, to file electronically to FINTRAC directly.
In this lesson, you will learn what kind of transactions must be referred, what forms to use,
and how you can effectively monitor daily transactions.
Suspicious Transaction Referrals/Reports
Structured transactions or
transactions that could involve
money laundering, terrorist
financing or other illegal activity
involving the use of or movement
of funds are considered suspicious
activity. Under the PCMLTFA,
certain entities including Western
Union must report suspicious
activity to FINTRAC. To help us
meet this obligation, Agents that
only offer Western Union services are required to submit Suspicious Transaction Referrals
for any completed or attempted transaction that the Agent considers suspicious. If you are
a registered Money Services Business or other reporting entity you would be required to file
a Suspicious Transaction Report directly to FINTRAC.
The Suspicious Transaction Referral is a tool for identifying and reporting
transactions or attempted transactions that could be related to money laundering
or terrorist financing. You need to be specific when providing your narrative about
the transaction - What did you see? What did you hear? What made you
suspicious of the transaction? You need to refer any transactions or attempted
transactions you consider suspicious to Western Union by:
Completing a Suspicious Transaction Referral for any transaction or pattern of
transactions – completed or attempted – that is suspicious.
© 2008-2010 Western Union Holdings, Inc. All Rights Reserved. Confidential and Proprietary 26Fax the completed form – to 1-888-447-4041 within 5 days from the date you saw the suspicious
activity. DO NOT FAX ANY FORMS DIRECTLY TO FINTRAC. If you are a registered Money Service
Business or other reporting entity submit your report following your established process.
You may be wondering how you know if a transaction or attempted transaction is suspicious. Let’s
examine what might be suspicious activity.
What Is Suspicious Activity?
Spotting suspicious activity is the first phase of the referral process. In general, a transaction or
attempted transaction is suspicious when you have reason to believe that it is being used to launder
money or finance terrorism, avoid reporting or record keeping requirements or be part of other illegal
activity.
We understand that you may not be certain if a consumer is making a transaction for a criminal purpose.
You are only required to identify transactions that are “suspicious,” that is, activity that could involve
illegal or criminal activity. To help you identify these transactions, there are a number of key signals –
commonly referred to as “red flags” – that may indicate suspicious activity. Red flags generally consist
of certain behaviour or characteristics about a consumer and the transaction that could cause you to be
concerned and suspicious.
Financial Agents
Through websites or emails criminals try to recruit account holders in your country in order to misuse
them and their accounts for so called financial agent activity. The recruited Financial Agents are asked
to receive a credit transfer on their bank account from an unknown person. Then they are instructed by
mail, telephone or SMS to withdraw the cash and send it via Western Union to another person in a
foreign country they do not personally know. As a reward, the Financial Agent is allowed to keep a
certain percentage of the transferred money. The funds the Financial Agent moves usually originate
from cybercrime activities (hacked bank accounts, etc.). The Financial Agent commits the offence of
money laundering. You as an Agent are obliged to do your part to prevent the misuse of tour system by
Financial Agents. Every suspicion that leads in this direction must be reported to Western Union by
completing a Suspicious Transaction Referral, or if you are a registered Money Services Business or other
reporting entity you would be required to file a Suspicious Transaction Report directly to FINTRAC.)
Red Flags
When one or more factors signal that a transaction is unusual and possibly suspicious, it is called a “red
flag.” Observing a red flag should trigger some questions, such as:
Is the amount of the transaction unusually large for the typical consumer?
Does the consumer make the same or similar transactions more frequently than normal?
Does the type of transaction seem unusual for the consumer?
Other examples of red flags include:
© 2008-2010 Western Union Holdings, Inc. All Rights Reserved. Confidential and Proprietary 27 Consumer uses a fake ID, or multiple IDs on different occasions (name, address, or
identification number may be different)
Two or more consumers use the same or similar ID (photo or name may be different).
Consumer changes a transaction after learning that he or she must show ID.
Consumer conducts transactions so that they fall just below amounts that require reporting or
record keeping.
Two or more consumers, trying to evade report or record keeping requirements, seem to be
working together to break one transaction into two or more transactions.
You know or have reason to suspect that the transaction involves funds from illegal activity.
The transaction does not appear to have a lawful purpose.
Be aware of consumers who:
Are hurried, nervous or evasive
Are aggressive or uncooperative
Are reluctant to provide ID or information
Appear at store opening, closing or peak times
Try to impress you with substantial future business or wealth
Offer you a tip, bribe or other inappropriate gift
Provide inconsistent information when asked questions
Come in several times in one day to conduct transactions that are just below the amounts that
require recording
Are not concerned about price or are too familiar with the reporting rules
Be alert for transactions that:
Are just below the threshold amount for reporting (such as a $9,900 cash transaction), or record
keeping/identification ($950-$999 for money transfers)
Are changed frequently by the consumer at the desk
Are conducted by familiar consumers who have a sudden change in pattern
Have inconsistent or non-existent relationship between the sender and the receiver or payee
Are conducted by multiple individuals who appear to know each other outside the premises, but
ignore each other while they are inside the business
Keep in mind, a consumer with any of the red flag behaviours should not automatically be considered a
money launderer or terrorist. However, one or more red flags should put you on alert to look for other
clues that something could be wrong with the transaction. Also keep in mind that by submitting a
Suspicious Transaction Referral/Report, you are not accusing the consumer of being involved in criminal
© 2008-2010 Western Union Holdings, Inc. All Rights Reserved. Confidential and Proprietary 28activity. You are only reporting activity that appears suspicious. Western Union will decide whether the
activity warrants the filing of a Suspicious Transaction Report for those Agents submitting referrals.
If you are suspicious about a transaction, ask about the intent of the transaction and familiarity with the
other party. If there are clear signs that the transaction is connected with illegal activity, refuse or do
not complete the transaction. Whether the transaction is completed or refused, file a Suspicious
Transaction Referral/Report with the information available to you.
Structuring:
In order to avoid record keeping, reporting or ID requirements, a money launderer may break up a large
amount of money into a number of smaller transactions. For example, in order to avoid having to show
an ID, a consumer may send four $900 money transfers rather than a single money transfer for $3,600.
This is commonly referred to as “structuring.” This should be reported to Western Union/FINTRAC using
the Suspicious Transaction Referral/Report.
The following are examples of possible structuring:
A consumer wants to make a money transfer for $2,500. When he learns that he must provide
information and show an ID, he asks to send three separate money transfers to the same
receiver, each for less than $1,000.
Three people come into your location and you see them split money between them. Each then
makes a money transfer of less than $1,000 to the same receiver.
Basic Rules:
Before looking at how to complete a Suspicious Transaction Referral/Report, let’s review some basic
rules.
Never tell a consumer that you are going to submit a Suspicious
Rule #1 Transaction Referral/Report to Western Union/FINTRAC. In addition,
be careful not to tell – or “tip off” – the consumer that you are going
to do so.
If you strongly suspect that a transaction involves illegal activity, do
Rule #2 not complete the transaction. However, you may complete the
transaction if you believe you or your employee would be in danger
by refusing to do so.
A Suspicious Transaction Referral/Report should be submitted even if
Rule #3 you don’t complete a suspicious transaction – for example, if you
refuse to complete a transaction because the consumer has
presented an obviously forged ID.
© 2008-2010 Western Union Holdings, Inc. All Rights Reserved. Confidential and Proprietary 29You can also read


