Experiences drive visitors - Jonathan Fauver - The role of DMOs in booking in-destination products and services - ITB Convention
←
→
Page content transcription
If your browser does not render page correctly, please read the page content below
Experiences drive visitors
The role of DMOs in booking in-destination products and services

                         Jonathan Fauver
                CEO and Co-Founder, TrekkSoft, Switzerland
              jon@trekksoft.com |   @jonfauver | www.trekksoft.com   1
Who we are
                                                          BOOKING SOLUTION

TrekkSoft is the leading online         PAYMENT GATEWAY
booking platform to build,
manage, market, connect and
sell activity experiences.
                                                               WEBSITE BUILDER

                                      CHANNEL MANAGER

                                                                   MOBILE APP

                                  RESOURCE MANAGER

                                                                                 2
Why are we interested in DMOs

                              EXPERIENCES ARE A VITAL PART OF THEIR STRATEGY

                                                  57%

                              PROVIDERS OFFER ONLINE BOOKING GLOBALLY

                             DMO OFFERS REAL-TIME BOOKING FOR EXPERIENCES

                            16%

TrekkSoft research, 2017.                                                      3
Evolution of DMOs

1   Experiences are the main driver of travel

2   Tour & Activity industry is still in the stone age

3   DMOs are uniquely positioned to facilitate evolution

                                                           4
Evolution of DMOs

Do DMOs need to evolve
  to avoid becoming
       obsolete?

                         5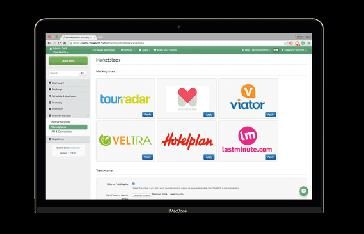
Evolution of DMOs

  1800                1900              1950            Internet          Mobile

Driver: Advancement of transportation          Driver: Advancement of technology

                                                                                   6
Change in traveler behavior
Mobile-driven change in consumer booking habits
40% of U.S. travel site visits come from mobile
but the time spent browsing those sites has
shrunk by 5% (Think with Google, 2016)
35 % of travellers use a mobile device more
on vacation than they do at home
(Expedia/Egencia, 2016)
7Control of information flow
Travellers consider their smartphones to
be the single most indispensable item
they carry with them when they travel
(Expedia/Egencia, 2016)
They created a better user
experience and disrupted the
industry by controlling the
information flow.
8Travel planning is dominated by online resources
9But mostly for flights & beds
Activities Account for 9% of the 129 Billion Global Travel Market
Global Travel Market Share by Segment, 2016
33%
Activities are growing faster than
9% the total market. Shares will
40%
exceed 10% by 2020
9%
9% Airlines Hotels Activities Rail Other
Source: Phocuswright’s Global Travel Activities 2014-2020: Tours & Attractions Come of Age
© 2017 Phocuswright Inc. All Rights Reserved.
10But mostly for flights & beds
Online Shares Well Behind Hotels
Online Penetration for Hotels and Tours & Attractions by Region, 2016
Hotels Tours & Attractions
40% 37%
32%
25% 24%
12%
APAC US Western Europe
Source: Phocuswright’s Global Travel Activities 2014-2020: Tours & Attractions Come of Age
© 2017 Phocuswright Inc. All Rights Reserved.
11But mostly for flights & beds
Online resellers only account for 4% of the global Tours & Attractions Sales
How reseller bookings are handled
11%
11%
Reservations from distribution partners
are largely managed manually, making 35%
instant booking confirmations a 13%
challenge. Only 13% of reservations
are via real-time connectivity.
Email Extranet from online seller
14%
XML feed from online seller Real-time online activity 16%
Phone Other
Source: Phocuswright’s Global Travel Activities 2014-2020: Tours & Attractions Come of Age
© 2017 Phocuswright Inc. All Rights Reserved.
12Ask yourself the
question
If an official DMO website was down for a
month, would that city actually get less
visitors? A hotel less bookings?
13TrekkSoft research results
Dec 2016 - Jan 2017
43%
57%
ORGANISATIONS COUNTRIES
51 15 North America Europe
TrekkSoft research, 2017. 14TrekkSoft research results
Dec 2016 - Jan 2017
8%
NATIONAL
44%
REGIONAL
48%
LOCAL
20% 80% 15
PRIVATE PUBLIC
TrekkSoft research, 2017. 15TrekkSoft research results
Dec 2016 - Jan 2017
What % of your program budget do you spend on
online/digital activities compared to offline activities?
43%
57%
Offline Online
TrekkSoft research, 2017. 16TrekkSoft research results
Dec 2016 - Jan 2017
What is bookable on your website?
ACCOMMODATION
43
ACTIVITIES PACKAGES RESTAURANTS
%
57 17
31 26
% %
%
%
69 74
% % 83
%
No Yes
TrekkSoft research, 2017. 17TrekkSoft research results
Dec 2016 - Jan 2017
Which part of the travel customer journey is most important?
20%
10%
48%
13%
Dreaming
Planning
Booking
10% Experiencing
Sharing
18TrekkSoft research results
Dec 2016 - Jan 2017
EXPERIENCES ARE A VITAL PART OF THEIR STRATEGY
57%
MARKETING SPEND
73% 27%
EXPERIENCES ACCOMMODATION
EXPERIENCES ACCOMMODATION
16% 57%
ABILITY TO BOOK ON THE WEBSITE IN REAL-TIME
TrekkSoft research, 2017. 19 19Consider the entire Buying Cycle
20Key takeaways for experiences
TECHNOLOGY
IS THE
1 Education CONTENT ENABLER
2 Products
PRODUCT
3 Content is king
EDUCATION OF SUPPLIERS
21Education of
suppliers
“Our role is to be the digital mentors in
the industry”
Katrine Mosfjeld, Visit Oslo
“The most important task of DMOs is
educating and consulting with their
members to help them stay up to date:
helping them get on mobile, help them
get their information displayed in the
right way on the right sites, prioritising
agility to bring change to a region.”
Philippe Ries, Industry leader, Travel, Google
22Zermatt Tourism
Board
E-fitness program for educating local
suppliers on best practices.
23Products
“Our organizations are best positioned to
track and evaluate trends to ensure that
what we offer is what visitors want”
Jennifer Wesselhof, CEO Visit Sedona
“Let’s not talk about tourism, tourism is
the effect. Let’s first focus on what it is
really about”
Peter Romer Hansen, Romer Agency
24Case study: Visit Dolomiti Paganella Bike
22
17
25 25Case study: Copenhagen Food Tourism
21
17
26 26Content is king
“Oslo as a destination is more important
than Visit Oslo the organization”
Katrine Mosfjeld, Visit Oslo
“Consumers market the destination
more effectively than the organization”
Peter Romer Hansen, Romer Agency
27Content first strategy
• Track content distribution
• Content-specific API
28Case study: Le Voyage à Nantes
“Let’s not talk about tourism, tourism is the effect, let’s focus on what it is really about”
#LVAN
29Make it bookable
“Technology is the enabler, not the solution”
• Put customer experience first
• Focus strengths
• Make it measurable
30Case study: Interlaken
31 31Case study: Interlaken - Statistics
Adventure Statistics of Interlaken
Activities Booked by Segments, 2014-2016
70.000
62062
53800
52.500
39790
35.000 33642
30873 30842
26688 26434
20826
17.500
0
Earth Water Air
32Case study: Interlaken - Statistics
Passengers booked
5000
4000
3000
3.834
2000
3.352
2.744
1000
0
2014 2015 2016
33Case study: Fjord Norway
• Experience storytelling first
• Project to make sure that all the
suppliers activities are bookable
• Project to make sure that the
experiences are bookable on
their own website
34 34NATIONAL
REGIONAL
LOCAL
35Live Inventory
1 Direct Bookings
2 Distribution
3 Cross Selling
36HOW TREKKSOFT
MAKES THIS
EASIER
POS Desk &
Agents
Channel Manager
Partner Network
Regional Marketplaces
37POS DESK & AGENTS
Build a network of agents to sell for
you and let them book directly into
your system on any mobile device.
38CHANNEL MANAGER
Distribute and sell your tours and activities across multiple channels from a single
platform and exercise full control over your bookings through OTAs and
Marketplaces.
39TREKKCONNECT
• Cross selling with other
activity providers
• Cross selling with
accommodation
providers
40TREKKCONNECT
• Creating dynamic multi-
element, multi-company
packages
41REGIONAL MARKETPLACES
• Experiences and storytelling
marketing
• Create local, regional and national
marketplaces
42Conclusion
1 Education and development to lift up the region
2 Content first
3 Make sure it is bookable, suppliers need to evolve
43Thank You!
44Join us at our stand!
HALL 4.1 STAND
244a
JOIN US FROM 15:30 - TO HEAR MORE ABOUT
FJORD NORWAY AND INTERLAKEN!
Jonathan Fauver
CEO and Co-Founder, TrekkSoft, Switzerland
jon@trekksoft.com | @jonfauver | www.trekksoft.com
45 45Questions?
Jonathan Fauver
CEO and Co-Founder, TrekkSoft, Switzerland
jon@trekksoft.com | @jonfauver | www.trekksoft.com
46 46You can also read


