Non-Wires Alternatives - CASE STUDIES FROM LEADING U.S. PROJECTS NOVEMBER 2018 - E4TheFuture
←
→
Page content transcription
If your browser does not render page correctly, please read the page content below

Non-Wires
  Alternatives
 CASE STUDIES FROM
LEADING U.S. PROJECTS

      Load Management Leadership

           NOVEMBER 2018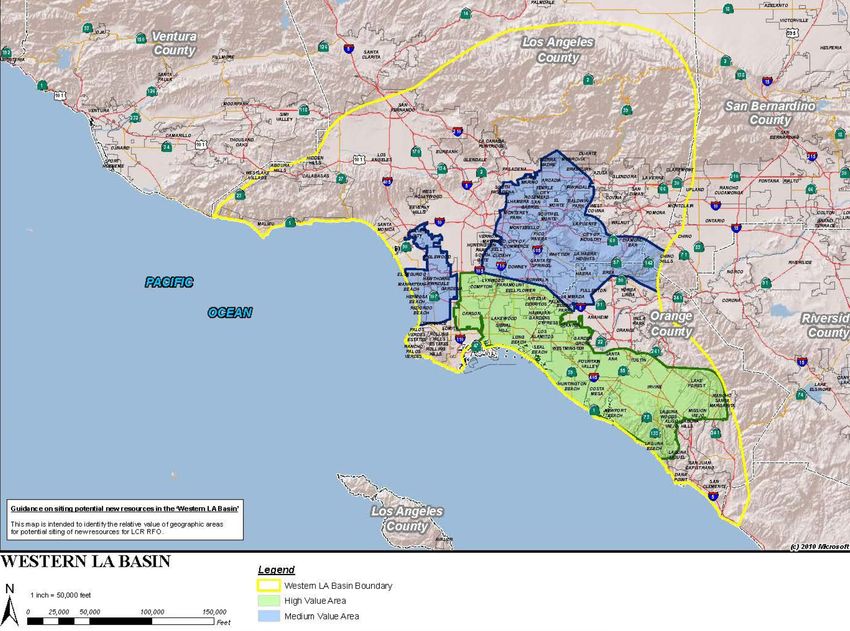
NON-WIRES ALTERNATIVES

TABLE OF CONTENTS
ABOUT THE REPORT....................................................................................................................................................................4
EXECUTIVE SUMMARY.................................................................................................................................................................7
INTRODUCTION......................................................................................................................................................................... 10
BACKGROUND............................................................................................................................................................................ 11
      §§ State of the Non-Wires Alternatives Market......................................................................................................... 12
      §§ Featured Case Studies.................................................................................................................................................. 14
      §§ Case Study Overview and Commonalities............................................................................................................. 15
      §§ Case Study Summaries................................................................................................................................................. 19
KEY INSIGHTS AND CHALLENGES........................................................................................................................................ 28
      §§ Planning and Sourcing.................................................................................................................................................. 29
      §§ Project Implementation............................................................................................................................................... 30
      §§ Technology Implementation...................................................................................................................................... 32
      §§ NWA Project Findings.................................................................................................................................................... 35
CONCLUSION.............................................................................................................................................................................. 38
      §§ Areas for Further Discussion and Research.......................................................................................................... 38
APPENDIX: CASE STUDIES....................................................................................................................................................... 41
      §§ Arizona Public Service (APS)—Punkin Center....................................................................................................... 42
      §§ Bonneville Power Administration—South of Allston......................................................................................... 45
      §§ Central Hudson Gas & Electric—Peak Perks Targeted Demand Management........................................ 49
      §§ Con Edison—Brooklyn Queens Demand Management................................................................................... 52
      §§ Consumers Energy—Swartz Creek Energy Savers Club................................................................................... 56
      §§ GridSolar, LLC—Boothbay........................................................................................................................................... 59
      §§ National Grid—Old Forge............................................................................................................................................ 63
      §§ National Grid—Tiverton NWA Pilot.......................................................................................................................... 65
      §§ Southern California Edison (SCE)—Distribution Energy Storage Integration (DESI) 1........................... 67
      §§ SCE—Distributed Energy Storage Virtual Power Plant (VPP).......................................................................... 70

2                                                                                                                                    E4THEFUTURE | PLMA | SEPA
Load Management Leadership

LIST OF FIGURES
FIGURE 1: MAP OF TOP SELECTED NWA CASE STUDIES.............................................................................................. 14
FIGURE 2: CASE STUDY PROJECT TIMELINES................................................................................................................... 17
FIGURE 3: SOUTH OF ALLSTON 2017 SUMMER PEAK FLOWS................................................................................... 20
FIGURE 4: EXAMPLE OF HOURLY LOAD REDUCTION PROVIDED BY DIFFERENT NWA RESOURCES............ 21
FIGURE 5: PROJECT AREA, BOOTHBAY PENINSULA....................................................................................................... 23
FIGURE 6: SITING LOCATION MAP FOR CONSTRAINED AREA, WESTERN LOS ANGELES BASIN................... 27

LIST OF TABLES
TABLE 1: STATE-LEVEL REGULATORY PROCESSES FOR NWAs................................................................................... 13
TABLE 2: NON-WIRES ALTERNATIVES CASE STUDIES BY PROJECT SIZE, STATUS, AND TECHNOLOGIES........16
TABLE 3: T&D CHALLENGES, DRIVERS, AND SOURCING............................................................................................. 18
TABLE 4: SUMMARY OF COST EFFECTIVENESS FOR THE TIVERTON NWA PILOT PROJECT............................. 25
TABLE 5: SUMMARY OF KEY INSIGHTS AND CHALLENGES......................................................................................... 28
TABLE 6: ENERGY EFFICIENCY AND DEMAND RESPONSE: LESSONS LEARNED.................................................. 33
TABLE 7: ENERGY STORAGE—IMPLEMENTATION CHALLENGES............................................................................. 34
TABLE 8: SUMMARY FINDINGS FOR NWA CASE STUDIES........................................................................................... 36

NON-WIRES ALTERNATIVES: CASE STUDIES FROM LEADING U.S. PROJECTS		                                                                                          3

NON-WIRES ALTERNATIVES

                                About the Report
COPYRIGHT                                              ABOUT PLMA
© Smart Electric Power Alliance, Peak Load             PLMA (Peak Load Management Alliance) is a
Management Alliance, and E4TheFuture, 2018.            non-profit organization founded in 1999 as the
All rights reserved. This material may not be          voice of load management practitioners. PLMA’s
published, reproduced, broadcast, rewritten,           over 140 member organizations share expertise
or redistributed without permission.                   to educate each other and explore innovative
                                                       approaches to demand response programs, price
AUTHORS                                                and rate response, regional regulatory issues,
Brenda Chew, Research Analyst, Smart Electric          and technologies as the energy markets evolve to
Power Alliance                                         represent a broad range of energy. Learn more at
Erika H. Myers, Research Director, Smart Electric      www.peakload.org.
Power Alliance                                         ABOUT E4THEFUTURE
Tiger Adolf, Member Services Director, Peak Load       E4TheFuture is a nonprofit organization advancing
Management Alliance                                    clean, efficient energy solutions. Advocating for
Ed Thomas, Executive Director, Peak Load               smart policy with an emphasis on residential
Management Alliance                                    solutions is central to E4TheFuture’s strategy.
                                                       “E4” means: promoting clean, efficient Energy;
ABOUT SEPA                                             growing a low-carbon Economy; ensuring low-
The Smart Electric Power Alliance (SEPA) facilitates   income residents can access clean, efficient,
the electric power industry’s smart transition to a    affordable energy (Equity); restoring a healthy
clean and modern energy future through education,      Environment for people, prosperity and the
research, standards and collaboration. SEPA is an      planet. Dedicated to bringing clean, efficient
unbiased, industry-trusted source for insights and     energy home for every American, E4TheFuture’s
knowledge on clean energy and grid modernization.      endowment and primary leadership come from
Learn more at www.sepapower.org.                       Conservation Services Group whose operating
                                                       programs were acquired in 2015 by CLEAResult.
                                                       Visit www.e4thefuture.org.

4                                                                         E4THEFUTURE | PLMA | SEPA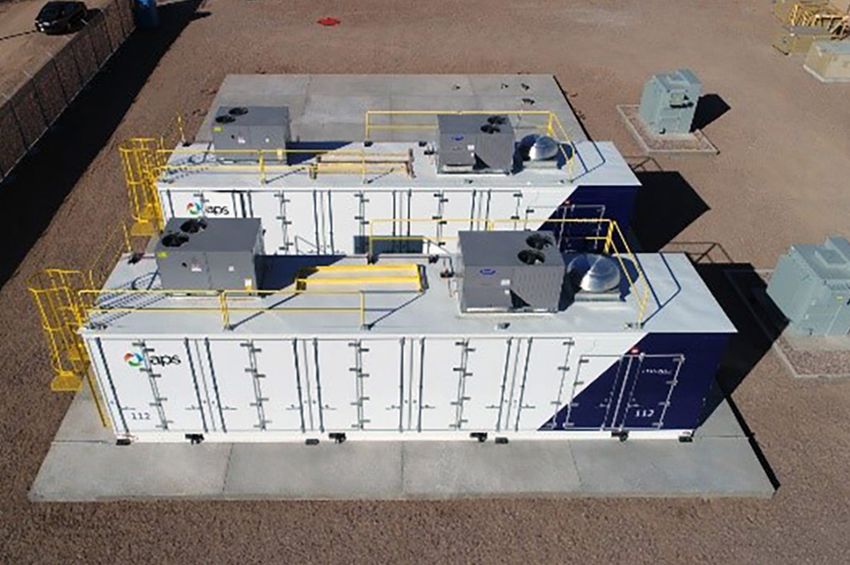
Load Management Leadership

ACKNOWLEDGEMENTS
The development of this report was the result of significant time and input from a large number of industry
peers. SEPA and PLMA would first like to thank Steve Cowell and Julie Michals for their efforts
at E4TheFuture to drive this important joint research effort forward.
PLMA staff performed the work of soliciting abstracts, establishing the peer review team, administering the
abstract scoring for selected case studies, and interviewing authors to develop case studies. This effort was
led by Tiger Adolf and Ed Thomas. Case studies developed for this report would not be possible without the
input from the following representatives:
Alan Harbottle,                     Damei Jack,                                    Matthew Chase,
Arizona Public Service              Consolidated Edison                            National Grid
Tom Spence,                         Mark Luoma,                                    Grant Davis,
Arizona Public Service              Consumers Energy                               Southern California Edison
Lee Hall,                           Kitty Wang,                                    Loic Gaillac,
Bonneville Power Administration     Energy Solutions                               Southern California Edison
Sarah Arison,                       Rich Silkman,                                  Polly Shaw,
Bonneville Power Administration     GridSolar, LLC                                 Stem
Mark Sclafani,                      George Cruden,
Central Hudson Gas & Electric       National Grid

Beyond case study participants, this research effort also included input from a number of peer review team
members and external reviewers:
Bruce Humenik,                      Steve Fine,                                    Jason Prince,
Applied Energy Group                ICF                                            Rocky Mountain Institute
Alexander Núñez,                    Andrea Simmonsen,                              Jeff Waller,
Baltimore Gas and Electric          Idaho Power                                    Rocky Mountain Institute
Frank Brown,                        Henry Yoshimura,                               Mark Dyson,
Bonneville Power Administration     ISO New England                                Rocky Mountain Institute
Derek Kirchner,                     Jason Cigarran,                                Ross Malme,
DTE Energy                          Itron                                          Skipping Stone
Rich Philip,                        Bill Steigelmann,                              Eric Winkler,
Duke Energy                         Lockheed Martin                                Winkler Consulting
Ryan Brager,                        Brett Feldman,                                 Joe Peichel,
Eaton                               Navigant                                       Xcel Energy
Ron Chebra,                         Ashley Van Booven,                             Dave Hyland,
Enernex                             New Braunfels Utilities                        Zen Ecosystems
Keith Day,                          Elizabeth Titus,                               Eric Smith,
E.ON                                Northeast Energy Efficiency Partnerships       Zome
Ric O’Connell,                      Michael Brown,
GridLab                             NV Energy
Rich Barone,                        Ahmed Mousa,
Hawaiian Electric                   Public Service Enterprise Group

Additional staff at SEPA helped to review and develop this report: K Kaufmann, Maclean Keller, Tanuj Deora,
Sharon Allan, Medha Surampudy, Nick Esch, Ian Motley, Maliya Scott, Chris Schroeder, Robert Tucker,
Jeffrey Fromuth, Erika Tomatore, Kate Strickland, Jared Leader, and Sharon Thomas.

NON-WIRES ALTERNATIVES: CASE STUDIES FROM LEADING U.S. PROJECTS		                                               5
NON-WIRES ALTERNATIVES

    METHODOLOGY

    In April of 2018, the Smart Electric Power Alliance   nn Challenges identified and lessons learned:
    (SEPA) and PLMA (Peak Load Management                    How compelling or unique are the challenges
    Alliance) received funding from E4TheFuture              encountered in any one project, and the
    for a study on the current status of non-wires           resulting lessons learned, which could be
    alternatives (NWA) projects across the United            shared across the industry?
    States. In particular, the goal of the study was      nn Cross-sectional representation: How do the
    to identify 10 representative projects and share         projects contribute to a well-rounded set of
    the lessons that utilities and other industry            case studies representing different geographic
    stakeholders have learned from the process of            locations, utility or project lead types, and
    developing and, in some cases, completing and            project sizes?
    operating these projects. To select the projects,     Once the 10 case studies were selected, we
    SEPA and PLMA issued an industry-wide call            conducted follow-up interviews with the utilities
    for NWA case studies, and ultimately received         and other project developers. The responses
    papers on more than 25 such projects, either in       were put into a case study template, which was
    development or in operation, from across the          then reviewed by the individual utilities and
    country. A peer review team of 29 volunteers          project developers. This report is based on the
    scored the papers, ultimately selecting the           original case studies submitted, and the in-depth
    10 case studies with the highest rankings.            information and insights gathered through the
    Selection was based on three key criteria:            interviews. Available data (e.g., cost data and
    nn Applicability: How relevant to other utilities     information on project challenges and solutions)
       and technology developers are the lessons          collected through this process varied depending
       learned from this NWA project? How can this        on the sensitivities and willingness of project
       project best inform utilities and be replicated?   participants to share information.

6                                                                             E4THEFUTURE | PLMA | SEPA
Load Management Leadership

                                       Executive Summary
In today’s electricity market, projects such as Con
Edison’s Brooklyn Queens Demand Management                                  CASE STUDIES
(BQDM) initiative are capturing public attention and
inspiring decision makers to examine the potential                          Case studies (listed alphabetically by utility or
of non-wires alternatives (NWAs).1 As interest in                           key project implementer2 if different from the
NWAs grows, industry practitioners are seeking out                          utility, followed by project name):
more information and lessons learned from past                              1. Arizona Public Service (APS)—Punkin Center
and existing efforts. To help shed light on a broader
                                                                            2. Bonneville Power Administration (BPA)—
set of NWA projects in the U.S., E4TheFuture
                                                                               South of Allston
provided funding to the Smart Electric Power
Alliance (SEPA) and PLMA (Peak Load Management                              3. Central Hudson Gas & Electric—Peak Perks
Alliance) to select 10 NWA case studies and share                              Targeted Demand Management Program
insights from these projects with the public.                               4. Con Edison—Brooklyn Queens Demand
Using help from 29 volunteer Peer Review Team                                  Management (BQDM) Program
members, the 10 case studies summarized in this
                                                                            5. Consumers Energy—Swartz Creek Energy
report were selected based on their applicability,
                                                                               Savers Club
lessons learned, and cross-sectional representation
(see Methodology for more details). These projects                          6. GridSolar—Boothbay
represent a range of technology and program                                 7. National Grid—Old Forge
solutions, project sizes, and geographies.
                                                                            8. National Grid—Tiverton NWA Pilot
There are over 100 NWA projects in various
                                                                            9. Southern California Edison (SCE)—
planning stages today. They account for over
                                                                               Distribution Energy Storage Integration
three-quarters of total planned and completed
                                                                               (DESI) 1
NWA capacity in the U.S.3 A smaller subset of NWA
projects have moved into implementation stages,                             10. SCE—Distributed Energy Storage Virtual
and an even smaller set of projects have reached                                Power Plant (VPP)
completion. The 10 case studies examined in this
report reflect the early stages of NWA development
across the U.S. One project is still in the
procurement phase, seven projects are currently
active, and two projects have reached completion.
Across these 10 case studies, key lessons learned
and challenges surfaced along three main
categories, as detailed in the table on page 8.

1   Non-wires alternatives are defined as “an electricity grid investment or project that uses non-traditional transmission and distribution
    (T&D) solutions, such as distributed generation (DG), energy storage, energy efficiency (EE), demand response (DR), and grid software
    and controls, to defer or replace the need for specific equipment upgrades, such as T&D lines or transformers, by reducing load at a
    substation or circuit level,” (Navigant, 2017).
2   Key project implementer is the key project sponsor indicated in case study submissions. Most projects were led by utilities.
3   Greentech Media, A Snapshot of the US Gigawatt-Scale Non-Wires Alternatives Market, August 2017. Available at:
    https://www.greentechmedia.com/articles/read/gtm-research-non-wires-alternatives-market#gs.lytvWGw.

NON-WIRES ALTERNATIVES: CASE STUDIES FROM LEADING U.S. PROJECTS		                                                                              7
NON-WIRES ALTERNATIVES

1. Planning and Sourcing—A number of utilities,                            not materialize. These projects pointed to the
   during the initial planning and procurement                             uncertainty of forecasting load growth and the
   phases, noted the importance of having a deep                           benefit NWAs provide in substantially reducing
   understanding of their service territories and                          potential stranded costs from investing in
   grid conditions to help inform their program                            unnecessary infrastructure upgrades.
   and technology procurement processes.                               2. Project Implementation—For the majority of
   Utilities use a “benefit to cost” assessment to                        the project teams, implementing the NWA effort
   evaluate NWA and other design options in                               meant navigating through uncharted territory.
   order to determine the least cost alternative                          As these teams tested out new technologies
   for consumers. In all cases, safety, reliability,                      and programs novel to utility customers, it was
   customer experience and affordability should                           necessary to plan for internal development,
   be foundational pillars for decisions on NWA                           reach out to local communities, and engage
   options.4 Utilities noted the importance of                            customers through a multipronged approach.
   building in more time for the sourcing process,                        Performance risks associated with new
   and the benefits of having an open and                                 technologies justify the use of demonstrations
   technology-agnostic approach.                                          and pilots to better understand performance
    For at least two projects, NWA opportunities                          and customer impacts, as well as exploring
    originally emerged as a result of high load                           mechanisms for prudent sharing of risks
    growth forecasts; however, load growth did                            between participants.

    SUMMARY OF KEY INSIGHTS AND CHALLENGES

                                                                               IMPLEMENTATION
     PLANNING AND SOURCING
                                                                                                 TECHNOLOGY-SPECIFIC
                                               PROJECT IMPLEMENTATION
                                                                                                   IMPLEMENTATION
     Open and technology-agnostic               Plan for internal development             Launching energy efficiency first allows
       approaches can help with                                                         longer lead times for other DER solutions
           project success
       Procurement processes and                 Community outreach helps                    Demand response encompasses
    bidding responses require more             overall reception and likelihood              a wide range of technologies and
     time than originally anticipated                 of project success                       was met with varying levels of
                                                                                              success across six case studies
       Uncertainty of load growth                 Recruitment and customer                   Energy storage implementation
        is a challenge for utilities               engagement requires a                   has its share of obstacles, including:
        but a strength for NWAs                    multipronged approach                       siting, reliability requirements,
                                                                                           interconnection, and system impact
    Know as much about your service
                                                                                                challenges. These challenges
      territory as possible to inform
                                                                                              are largely due to the nascency
           program recruitment
                                                                                                   of storage technologies
     Utilities often use a benefit-to-
      cost assessment to evaluate
            NWA opportunities
Source: SEPA, PLMA, and E4TheFuture, 2018.

4   Note: In many states, environmental impacts must also now be considered a foundational pillar for future investments.

8                                                                                                 E4THEFUTURE | PLMA | SEPA
Load Management Leadership
3. Technology-Specific Implementation— significant role in the varying levels of success
Projects in this study included a mix of of energy efficiency (EE) and demand response
technology solutions.5 Case study participants (DR) programs included in NWA solutions. For
noted that different technologies, their six of the case study participants leveraging
market maturity, and customer recruitment electric storage, the nascency of electric storage
opportunities all factored into the varying and the inexperience of project teams led
levels of success when implementing these to significant lessons being learned for this
NWA projects. Customer engagement played a technology type.
SUMMARY OF FINDINGS
While the majority of case studies examined in Edison’s BQDM and BPA’s SOA demonstrated
this report are still active or in the early stages of significant cost savings in implementing their
sourcing, a number of high-level findings became NWAs in comparison to the originally proposed
apparent: infrastructure investment. A major obstacle
nn Successful delays and deferrals of and opportunity is overcoming the traditional
infrastructure upgrades—The majority of rate-based cost recovery model and evolving
the 10 case studies demonstrated success the utility business model to provide alternative
in helping to delay or permanently defer revenue streams and incentives for utilities
infrastructure upgrades. to explore benefits from DER technologies. It
should be acknowledged that in many cases,
nn Flexibility—NWA projects offer the ability this requires an update of the traditional utility
to implement solutions incrementally and in compact and revenue recovery model while
phases as load grows. This allows opportunities maintaining the commitment to providing the
to approach load growth uncertainty flexibly customer safe, reliable and affordable choices.
and help avoid large up-front costs. Central Hudson’s Peak Perks Program showed
nn Cost Savings and Allocations—While many success with the development of a unique
of the case studies were unable to report incentive-based compensation model rewarding
cost data and analysis, projects such as Con both utilities and customers.
AREAS FOR FURTHER RESEARCH
As interest in NWAs continues to expand, many nn NWA benefit-to-cost analysis (BCA) and new
issues will require further utility research and incentive models for utilities;
discussion, including: nn Beneficial electrification, its impact on the grid,
nn NWA sourcing best practices; and the role of NWAs.
nn Ownership and control of NWAs;
nn Utility contracting benchmarks with technology
providers and third party owners;
nn Navigating multiple value streams of, and cost
recovery approaches for, DERs serving as NWAs;
5 Case study technology solutions included: energy efficiency (EE), demand response (DR), rooftop solar photovoltaics (PV), combined heat
and power (CHP), conservation voltage optimization, thermal storage, generators, electric storage, and generation redispatch.
NON-WIRES ALTERNATIVES: CASE STUDIES FROM LEADING U.S. PROJECTS 9NON-WIRES ALTERNATIVES
Introduction
A significant shift is taking place in the electric be addressed before NWAs can become more
power sector today. Regulators, policy makers, mainstream.
and utilities are beginning to investigate and As noted in the Methodology section of this report,
deploy alternatives to traditional transmission and the NWA projects discussed here were selected
distribution assets—that is, building power plants based on their applicability, lessons learned, and
and other traditional electric infrastructure as has cross-sectional representation. For each case
been done for the past 100 years. They are instead study, key personnel at utilities and at third-
looking at non-wires alternatives, or NWAs.6 party organizations shared insights regarding
A number of factors have contributed to the planning, procurement, and implementation
the changes now underway. The large-scale stages of their projects, as well as the technical and
deployment and increasing cost-effectiveness regulatory challenges they faced.
of distributed energy resources (DERs) is fueling The report is broken down into four key sections:
interest in NWAs. Navigant Research forecasts
global spending on NWAs will grow from $63 nn Background provides the history, a policy
million in 2017 to $580 million in 2026.7 In review, and a summary of the overall state of
California, New York and a number of other NWAs today. This section also includes short
regions, efforts are underway to examine the descriptions of the 10 NWA case studies.
potential benefits DERs and their use in NWAs can nn Key Insights and Challenges delves into
provide to transmission and distribution systems. the key lessons learned and findings from the
However, the growing interest in NWAs has 10 case studies. Insights are shared at the
revealed a major gap in current knowledge, planning, procurement and implementation
specifically, the lack of publicly available phases.
information describing challenges and lessons nn Conclusion explores areas for further
learned from NWA projects. To meet this need, discussion and research.
E4TheFuture provided funding to the Smart nn Appendix provides the 10 NWA case studies in
Electric Power Alliance (SEPA) and PLMA (Peak their entirety, and resources for further reading.
Load Management Alliance) to select 10 case
studies of NWA projects and share information
and insights regarding these initiatives with a
broad range of industry stakeholders.
For many utilities and third parties leading these
projects, NWAs proved to be the testing ground for
new technologies, programs, and methods. These
projects challenged traditional utility business
models and shed light on the legislative, regulatory,
and customer experience barriers that need to
6 NWAs are generally defined as the use of non-traditional solutions (e.g., distributed energy resources) to help defer or replace traditional
infrastructure investments (see next section for a full definition).
7 Non-Traditional Transmission and Distribution Solutions: Market Drivers and Barriers, Business Models, and Global Market Forecasts,
Navigant, 2017. Available at: https://www.navigantresearch.com/reports/non-wires-alternatives.
10 E4THEFUTURE | PLMA | SEPALoad Management Leadership
Background
While NWAs have recently become a focus of
discussions across the electric power industry, the DEFINING NON-WIRES ALTERNATIVES
concept of non-wires alternatives has been around
for over three decades.8 Earlier opportunities for Non-wires alternatives is one of several terms
NWA development were often talked about as now used to refer to the use of DERs in place
“targeted demand-side management” or other of traditional power plants and infrastructure.
aliases, the objective of which was to offset Other terms include non-wires solutions (NWS)
distribution investment. Bonneville Power Authority and non-transmission alternatives (NTA). NWA
(BPA) started exploring NWA opportunities in the remains the most commonly used term, which
Pacific Northwest as early as 1987 and has since is our main reason for using it in this report.
considered over 150 potential NWA projects.9 To Our working definition of NWAs comes from
date, however, BPA has implemented just three Navigant:
of these projects. In California, Pacific Gas and
Electric (PG&E) developed its first NWA in 1991 as Non-wires alternatives is defined as “an
a targeted demand-side management measure.10 electricity grid investment or project that uses
non-traditional transmission and distribution
Renewed interest in NWAs is taking place today in (T&D) solutions, such as distributed generation
large part due to the widespread deployment of (DG), energy storage, energy efficiency (EE),
DERs and the potential to leverage their multiple demand response (DR), and grid software
capabilities. Efforts to reform the traditional and controls, to defer or replace the need for
utility business model, respond to forecasted specific equipment upgrades, such as T&D
load growth, and integrate DERs are leading to lines or transformers, by reducing load at a
a growing number of of opportunities for NWA substation or circuit level.” 11
projects. In some instances, these projects are
being driven by state-level regulatory processes;
in others, utilities and other industry stakeholders
are independently assessing and testing strategic,
locational deployment of DERs.
8 Most utilities currently consider new technologies and applications through a BCA formula that considers foundational pillars of safety,
reliability customer experience, affordability and more recently environmental impacts.
9 BPA, Non-Wires Alternatives to Transmission, 2003. Available at: https://aceee.org/files/pdf/conferences/eer/2003/Hoffman-CPAw.pdf.
10 The PG&E Model Energy Communities Program: Offsetting Localized T&D Expenditures with Targeted DSM, 1992. Available at:
https://aceee.org/files/proceedings/1992/data/papers/SS92_Panel5_Paper17.pdf.
11 Navigant, Non Wires Alternatives, 2017.
NON-WIRES ALTERNATIVES: CASE STUDIES FROM LEADING U.S. PROJECTS 11NON-WIRES ALTERNATIVES
NWAs: HOW ARE THEY DIFFERENT FROM VIRTUAL POWER PLANTS AND MICROGRIDS?
The difference between NWAs, virtual power report is referred to as a virtual power plant. VPPs
plants (VPPs) and microgrids remains a point of and microgrids also have the potential to reduce
some confusion within the industry. constraints on existing T&D infrastructure and
nn VPPs rely on software and advanced help avoid the needs for system upgrades.
communication systems to aggregate, control, However, a distinction can be drawn based on
dispatch, plan, and optimize a suite of DERs the purpose and goals of a project. The NWAs
to provide services similar to a conventional discussed in this study were developed explicitly
power plant.12 to defer or replace grid infrastructure upgrades,
nn Microgrids are comprised of a group of while VPPs and microgrids are traditionally
interconnected loads and DERs within clearly developed for a variety of other purposes.
defined electrical boundaries. A microgrid can
act as a single controllable entity with respect SEPA, PLMA, and E4TheFuture look forward to
to the grid, and can connect or disconnect from working with industry peers to align terminology
the grid to operate in both grid-connected and to prevent confusion among stakeholders and
“island” mode.13 provide clear distinctions between the purposes
for each end use of DER technologies.
Certainly, some NWA projects include VPPs and
microgrids. In fact, one of the case studies in this
STATE OF THE NON-WIRES ALTERNATIVES MARKET
Global spending on NWAs is forecasted to grow (GW) of cumulative distributed solar capacity
from $63 million in 2017 to $580 million in 2026, in the state.15 CPUC’s guidance for developing
according to Navigant Research.14 While some U.S. distribution resource plans (DRPs) requires
utilities are choosing to explore NWA opportunities utilities to assess the grid impacts of DERs
on their own, a significant number of projects are and optimize utility operations and planning
the result of state-level regulatory processes and processes.
public-private partnerships, as outlined in Table 1. nn In New York, the REV initiative is in the process
Regulatory processes have had the biggest impacts of overhauling the traditional utility business
in California and New York—states which have long model so that utilities will become distribution
provided models for industry-wide changes later system platform providers.16 In addition, the
adopted in many other states. REV has made utility planning processes
nn In California, high levels of DER penetration more transparent. As of May 2018, New York
have begun to cause operational grid issues. As utilities had 41 current and upcoming NWA
of the end of 2017, there was over 7 gigawatts procurements listed on the REV Connect site.17
12 SEPA, Virtual Power Plants: Buzzword or Breakthrough?, November 2016. Available at: www.sepapower.org.
13 U.S. Department of Energy definition, https://building-microgrid.lbl.gov/microgrid-definitions. See also SEPA and EPRI, December
2016, Microgrids: Expanding applications, implementations, and business structures, www.sepapower.org.
14 Navigant, Non-Wires Alternatives, 2017. Available at: https://www.navigantresearch.com/reports/non-wires-alternatives; see also
https://www.utilitydive.com/news/non-wires-alternatives-whats-up-next-in-utility-business-model-evolution/446933/.
15 SEPA, 2018 Utility Solar Market Snapshot, 2018. Available at: https://sepapower.org/resource/2018-utility-solar-market-snapshot/.
16 ScottMadden, California and New York Demonstration Projects, 2017.
17 NYREV, accessed 9/12/2018, available at: https://nyrevconnect.com/non-wires-alternatives/.
12 E4THEFUTURE | PLMA | SEPALoad Management Leadership
TABLE 1: STATE-LEVEL REGULATORY PROCESSES FOR NWAs
CALIFORNIA The California Public Utilities Commission (CPUC) has approved a number of NWA-related
actions, including:
§§ Providing guidance to the state’s investor-owned utilities (IOUs) regarding development of
distribution resource plans (DRPs) that “identify optimal locations for the deployment of
distributed resources.”18
§§ Approving a pilot regulatory incentive mechanism that awards a 3-4% pre-tax incentive
to utilities deploying cost-effective DERs that defer or displace traditional distribution
investments.19
§§ Directing California IOUs to procure at least 150 MW of “preferred resources,” such as EE,
solar PV, or energy storage resources.20
NEW YORK In 2014, New York launched a set of regulatory proceedings and policy initiatives known as
Reforming the Energy Vision (REV). One of REV’s key goals is to incentivize utilities to leverage
the deployment of DERs to address problems traditionally handled by new investments in
centralized generation, transmission, and distribution infrastructure.21
RHODE ISLAND In 2006, Rhode Island enacted a requirement for utilities to file annual System Reliability
Procurement reports. As part of this process, utilities have to consider NWAs. The state’s major
distribution utility is also allowed to recover costs of investments in system reliability.22
VERMONT The Vermont Public Utility Commission enacted legislation in 2015 requiring the Vermont
System Planning Committee to identify deferral projects when considering new transmission.23
MAINE The state’s Smart Grid Policy Act Directive requires regulators to consider NWAs before
approving T&D projects. As of 2016, Maine has also designated a non-transmission alternative
(NTA) coordinator to establish an independent investigator responsible for identifying cost-
effective projects.24
Source: SEPA, PLMA, and E4TheFuture, 2018.
18 CPUC Public Utilities Code Section 769 issued on August 14, 2014.
19 Decision Addressing Competitive Solicitation Framework and Utility Regulatory Incentive Pilot, Decision 16-12-036, CPUC, December 15,
2016.
20 Order Instituting Rulemaking to Integrate and Refine Procurement Policies and Consider Long Term Procurement Plans, California Public
Utilities Commission, 2014. Available at: http://docs.cpuc.ca.gov/PublishedDocs/Published/G000/M089/K008/89008104.PDF.
21 Proceeding on Motion of the Commission in Regard to Reforming the Energy Vision, New York Department of Public Service, 2014.
Available at: http://www3.dps.ny.gov/W/PSCWeb.nsf/All/C12C0A18F55877E785257E6F005D533E?OpenDocument.
22 Rhode Island Office of Energy Resources, System Reliability Program. Available at: http://www.energy.ri.gov/reliability/.
23 Northeast Energy Efficiency Partnerships, EM&V Forum and Policy Brief: State Leadership Driving Non-Wires Alternative Projects and
Policies, 2017. Available at: https://neep.org/sites/default/files/resources/NWA%20brief%20final%20draft%20-%20CT%20FORMAT.pdf
24 Maine Public Utilities Commission, Docket No. 2016-00049, Commission Initiated Investigation into the Designation of a Non
Transmission Alternative Coordinator, March 2016. Available at: https://mpuccms.maine.gov/CQM.Public.WebUI/Common/
CaseMaster.aspx?CaseNumber=2016-00049.
NON-WIRES ALTERNATIVES: CASE STUDIES FROM LEADING U.S. PROJECTS 13NON-WIRES ALTERNATIVES
The NWA market is still nascent, but the number to looking at non-traditional options. From their
of proposed or potential projects is growing. perspective, it is an obstacle to look beyond current
Some stakeholders see NWAs as a cost effective practices unless there are updates to the regulatory
opportunity to help meet the power needs of compact and associated revenue recovery
a region and provide environmental benefits. models that reward performance and establish
However, utilities have long relied on traditional accountability for customer satisfaction.
solutions. They may be skeptical and resistant
FEATURED CASE STUDIES
FIGURE 1: MAP OF TOP SELECTED NWA CASE STUDIES
BPA—SOUTH OF ALLSTON
ALLSTON, WA
SCE—VIRTUAL POWER PLANT
LOS ANGELES, CA
SCE—DESI 1
ORANGE, CA
APS—PUNKIN CENTER
PUNKIN CENTER, AZ
CONSUMERS ENERGY—
SWARTZ CREEK ENERGY SAVERS
SWARTZ CREEK, MI
NATIONAL GRID—OLD FORGE
OLD FORGE, NY
CENTRAL HUDSON GAS &
ELECTRIC—PEAK PERKS PROGRAM
MID-HUDSON RIVER, NY
CON ED—BROOKLYN QUEENS
DEMAND MANAGEMENT
BROOKLYN, NY
NATIONAL GRID—TIVERTON
NWA PILOT
TIVERTON/LITTLE COMPTON, RI
GRIDSOLAR—BOOTHBAY PILOT
Source: SEPA, PLMA, and E4TheFuture, 2018. BOOTHBAY PENINSULA, ME
SELECTED NON-WIRES PROJECTS
Case studies (listed alphabetically by utility and 5. Consumers Energy—Swartz Creek Energy
key project implementer if different from the Savers Club
utility, followed by project name): 6. GridSolar—Boothbay
1. Arizona Public Service (APS)—Punkin Center 7. National Grid—Old Forge
2. Bonneville Power Administration (BPA)— 8. National Grid—Tiverton NWA Pilot
South of Allston (SOA)
9. Southern California Edison (SCE)—Distribution
3. Central Hudson Gas & Electric—Peak Perks Energy Storage Integration (DESI) 1
Targeted Demand Management Program
10. SCE—Distributed Energy Storage Virtual
4. Con Edison—Brooklyn Queens Demand Power Plant
Management (BQDM) Program
14 E4THEFUTURE | PLMA | SEPALoad Management Leadership
CASE STUDY OVERVIEW AND COMMONALITIES
The case studies profiled in this study encompass Table 2 provides a detailed list of each project’s
a broad range of project types and characteristics: size, status, and technology portfolio.
nn Project sizes include transmission-level NWAs Each of these projects has unique elements, based
providing 100 megawatts (MW) of load relief, as on regulatory environment, service territory, and
well as distribution-level NWAs ranging from 330 specific grid constraints and conditions. However,
kilowatts (kW) to 85 MW. a handful of key commonalities became evident
nn Status of projects ranges from complete, among many of them:
currently active, and early procurement phases. nn Regulatory mandates played a large role in
nn Technologies and programs include a mix over half of the 10 case studies. For projects
of behind-the-meter and front-of-the-meter in states such as New York and California,
solutions. Behind-the-meter solutions include broader policy initiatives, such as New York’s
EE, DR, rooftop solar PV, combined heat and REV and California’s DRPs, are challenging
power (CHP), conservation voltage optimization, traditional utility business models and pushing
thermal storage, generators, and electric utilities to look at ways to leverage DERs to
storage. Front-of-the-meter solutions include optimize operations and planning processes.
energy storage and generation redispatch. For a few case studies, direct regulatory
(See Table 2 or Appendix). mandates came as a result of a third-party
nn Results and Outcomes of these projects challenging a utility’s rate case filing and winning
were positive for the most part. They commission approval to explore clean energy
successfully helped delay or permanently defer and NWA opportunities.
infrastructure upgrades.
ALTERNATIVE UTILITY REVENUE STREAMS AND INCENTIVES FOR NWAs:
PROVIDING CERTAINTY IN AREAS OF UNCERTAINTY
For many NWA efforts taking place across environmental impact, reliability, or resiliency,
the U.S., overcoming the traditional utility that potentially could yield more revenue
compensation model of obtaining an established than a fixed rate of return (i.e., higher risk, but
rate of return on traditional capital investments higher reward);
is a major hurdle. Further, NWA projects require nn Utility revenue-sharing on NWA savings;
more effort to design and execute than most
traditional upgrades. In order for the utility nn Providing greater clarity regarding utility
industry to be motivated to explore NWA ownership or compensation for NWAs,
opportunities, alternative revenue streams and particularly in deregulated states, so that
incentives, opportunities for demonstrations and financial compensation opportunities are
testing, consideration of new service offerings more transparent;
and clear understanding of procedural and nn Addressing concerns associated with revenue
performance responsibilities are needed. Some opportunities in areas of the country where
examples include: high levels of DR and EE investments already
nn Performance-based regulation that could exist. This could be done by developing
include some financial incentive, for example policies and regulations that account for these
associated with congestion-cost management, limitations as part of the incentive design.
NON-WIRES ALTERNATIVES: CASE STUDIES FROM LEADING U.S. PROJECTS 15NON-WIRES ALTERNATIVES
TABLE 2: NON-WIRES ALTERNATIVES CASE STUDIES BY PROJECT SIZE, STATUS, AND TECHNOLOGIES
COMBINED HEAT AND POWER
CONSERVATION VOLTAGE
BACKUP GENERATORS
DEMAND RESPONSE
ENERGY EFFICIENCY
ENERGY STORAGE
OPTIMIZATION
GENERATION
FUEL CELLS
SOLAR PV
UTILITY, KEY PROJECT
IMPLEMENTER—PROJECT
NAME PROJECT SIZE STATUS NOTES
ARIZONA PUBLIC
SERVICE—PUNKIN 2 MW, 8 MWh A: Q1 2018
CENTER
BONNEVILLE POWER 200 MW Inc.
A: July 2017
ADMINISTRATION— 200 MW Decr.
T: Sept. 2018
SOUTH OF ALLSTON 100 MW Relief
CENTRAL HUDSON
GAS & ELECTRIC—
16 MW A: 2016
PEAK PERKS DEMAND
MANAGEMENT PROGRAM
CON EDISON—
BROOKLYN QUEENS
52 MW A: 2014
DEMAND MANAGEMENT
(BQDM) PROGRAM
CONSUMER ENERGY—
SWARTZ CREEK ENERGY 1.4 MW A: Oct. 2017
SAVERS CLUB
Thermal
GRIDSOLAR— A: Q4 2013
1.85 MW and electric
BOOTHBAY T: Q2 2018
storage
NATIONAL GRID— 19.8 MW, In
OLD FORGE 63.1 MWh development
NATIONAL GRID—
330 kW A: 2012
TIVERTON NWA PILOT
SOUTHERN CALIFORNIA
EDISON—DISTRIBUTION 2.4 MW,
A: May 2015
ENERGY STORAGE 3.9 MWh
INTEGRATION (DESI) 1
Storage
SOUTHERN CALIFORNIA
systems
EDISON—VIRTUAL 85 MW A: Dec. 2016
applied as
POWER PLANT (VPP)
DR
Note: Status indicates when project started. A: Active; T: Terminated.
Source: SEPA, PLMA, and E4TheFuture, 2018.
16 E4THEFUTURE | PLMA | SEPALoad Management Leadership
CASE STUDY PROJECT TIMELINES
Projects’ timelines for NWA projects varied based For some utilities with larger portfolios of
on the scale of the project and the technologies solutions or customer programs (e.g., DR and
or programs selected to implement. For a number EE), the procurement process was an iterative
of cases, a significant amount of time was spent one, occurring alongside implementation.
ideating and examining the viability of an NWA Implementation was, in some cases, much clearer
solution. Similarly, the planning phases ranged when installing a battery, whereas it took longer
from four months to 38 months. Procurement when requiring customer recruitment for DR
fell on average from three months to 11 months. programs.
FIGURE 2: CASE STUDY PROJECT TIMELINES
ARIZONA PUBLIC SERVICE (APS)—PUNKIN CENTER
BONNEVILLE POWER ADMINISTRATION (BPA)
—SOUTH OF ALLSTON (SOA)
CENTRAL HUDSON GAS & ELECTRIC
—PEAK PERKS PROGRAM
CON EDISON—BROOKLYN QUEENS
DEMAND MANAGEMENT (BQDM) PROGRAM*
CONSUMERS ENERGY—SWARTZ
CREEK ENERGY SAVERS CLUB
GRIDSOLAR—BOOTHBAY
NATIONAL GRID—OLD FORGE*
NATIONAL GRID—TIVERTON NWA PILOT
SOUTHERN CALIFORNIA EDISON (SCE)—
DISTRIBUTION ENERGY STORAGE INTEGRATION (DESI) 1
SCE—DISTRIBUTED ENERGY STORAGE
VIRTUAL POWER PLANT
0 1 2 3 4 5 6 7 8 9
YEARS
IDEATION PLANNING PROCUREMENT/SOURCING IMPLEMENTATION
Note: Project timeline information and detail varied widely across the 10 case studies. This figure was developed with input from utilities
to provide a high level picture of project timelines. More detailed project timelines are available upon request.
*Additional notes: For BQDM, multiple programs contribute to the BQDM portfolio, and thus timelines for procurement and
implementation are ongoing. National Grid’s Old Forge is currently in the planning and procuring phases. BPA’s South of Allston,
GridSolar’s Boothbay and National Grid’s Tiverton NWA Pilot are the only three projects of the 10 that have been fully wrapped up.
Definitions for timeline phases:
§§ Ideation: The more informal period of discussing and exploring potential for NWA solutions to address reliability concerns,
increased load forecasts, or deferment of new transmission and distribution investments.
§§ Planning: The time involved in identifying needs of the system and developing criteria for a non-wires project and preparing for
sourcing solutions.
§§ Procurement/Sourcing: The time needed to develop, release, and conclude negotiations for proposals of a non-wires alternative
project, primarily through competitive solicitation or a customer program.
§§ Implementation/Construction: The time needed to recruit customers for EE and DR programs, as well as deploy new assets (e.g.,
electric storage).
Source: SEPA, PLMA, and E4TheFuture, 2018.
NON-WIRES ALTERNATIVES: CASE STUDIES FROM LEADING U.S. PROJECTS 17NON-WIRES ALTERNATIVES
nn Internal management decisions also played explore alternatives to large-scale generation or
a significant role in NWA projects. A number grid upgrade projects.
of projects came to fruition due to an internal nn Sourcing across the 10 case studies was
management decision influenced by regulatory predominantly through direct procurement,
mandates (e.g., CPUC’s preferred resources either single-source or competitive bidding
pilot). Other NWA opportunities were primarily processes.
driven by internal management decisions to
TABLE 3: T&D CHALLENGES, DRIVERS, AND SOURCING
UTILITY, KEY PROJECT
T&D CHALLENGE DRIVERS SOURCING
IMPLEMENTER—PROJECT NAME
Regulatory Mandate,
ARIZONA PUBLIC SERVICE— Thermal constraint Direct procurement
Internal Management
PUNKIN CENTER on feeder (competitive bidding)
Decision
BONNEVILLE POWER ADMINISTRATION— Transmission grid Internal Management
Direct procurement
SOUTH OF ALLSTON constraint Decision
CENTRAL HUDSON GAS & ELECTRIC—
Distribution
PEAK PERKS DEMAND MANAGEMENT Regulatory Mandate Customer Program
constraint
PROGRAM
CON EDISON— Sub-transmission Regulatory Mandate,
BROOKLYN QUEENS DEMAND feeder constraint at Internal Management Customer Program
MANAGEMENT (BQDM) PROGRAM substation Decision
Regulatory Mandate,
CONSUMERS ENERGY— Distribution
Internal Management Customer Program
SWARTZ CREEK ENERGY SAVERS CLUB constraint
Decision
Distribution Regulatory Mandate, Direct procurement
GRIDSOLAR—
constraint and Internal Management (competitive bidding,
BOOTHBAY
reliability Decision, Public Input sole-sourced)
Distribution Direct procurement
NATIONAL GRID— Internal Management
constraint and (competitive bidding,
OLD FORGE Decision
grid resiliency sole-sourced)
NATIONAL GRID— Feeder substation Internal Management
Customer Program
TIVERTON NWA PILOT upgrade deferral Decision
SOUTHERN CALIFORNIA EDISON— Direct procurement
Distribution Internal Management
DISTRIBUTION ENERGY STORAGE (competitive bidding,
constraint Decision
INTEGRATION (DESI) 1 sole-sourced)
Internal Management Direct procurement
SOUTHERN CALIFORNIA EDISON— Long term local
Decision with (competitive bidding,
VIRTUAL POWER PLANT (VPP) capacity constraints
Regulatory Mandate sole-sourced)
Note: In a majority of case studies, NWA solutions were procured through competitive solicitations (e.g., RFI and RFPs). A subset of these
case studies leveraged existing customer programs (e.g., EE and DR) to help meet NWA objectives.
Source: SEPA, PLMA, and E4TheFuture, 2018.
18 E4THEFUTURE | PLMA | SEPALoad Management Leadership
CASE STUDY SUMMARIES
APS—PUNKIN CENTER
At Punkin Center, Arizona, APS was faced with
the traditional option of rebuilding 17 miles of
distribution lines over rough terrain to address
load growth and consequent thermal constraints
on the feeder. After reviewing the growing
community’s needs, APS determined that adding
battery storage could address the problem at
a lower cost. The utility deployed a 2 MW, 8
megawatt-hour (MWh) battery system that has
been in daily operation since March 2018.
The Punkin Center project required high Source: Arizona Public Service, 2018.
reliability, which led APS to plan the deployment
and operation of the battery system to provide line. The success of the project demonstrates
several layers of redundancy and flexibility for the capability of this NWA solution to serve the
future expansion. Spares of critical items with residents of Punkin Center for a decade and
long procurement lead-times, such as an extra possibly longer depending on the load growth.
transformer, were kept on-site. The site was
configured to connect a diesel generator in case BPA—SOUTH OF ALLSTON
of a contingency event. In addition, the project Faced with projections of growing demand on its
was designed with additional concrete pads for transmission system, BPA originally proposed the
the future addition of battery capacity to meet I-5 Corridor Reinforcement Project in 2009. At that
load growth. APS also ran up against a number time, the plan involved construction of an 80-
of challenges during the first operating summer, mile, 500 kilovolt (kV) transmission line that would
including the development of a battery dispatch stretch from Castle Rock, Washington to Troutdale,
method for peak shaving, the impact of battery Oregon and cost more than $1 billion. This
ramp limitations due to the Integrated Volt/VAR transmission project faced community opposition
Control (IVVC) voltage control scheme and high and heightened legislative scrutiny due to its high
feeder impedance, and operational considerations cost and local impacts.
for reverse power flow situations. Overall, APS
considered this effort as proof that cost-effective After taking a comprehensive look at the local
NWA projects using energy storage can be impacts of the build-out and other project details,
successful and should be in the utility planner’s such as load forecasts and project costs, the BPA
toolbox. Administrator decided not to carry out the I-5
project and instead embraced a more flexible,
Outcome: The Punkin Center battery project scalable, economically and operationally efficient
successfully provided reliable peak shaving service approach to managing the transmission system.
on the thermally constrained feeder during the The NWA project included two basic types of
summer of 2018. The project proved to be a solutions: DR centered on a large commercial
cost-effective solution for APS to serve the rural and industrial (C&I) end user, and generation
community, compared to reconductoring of the redispatch.25
25 Generation redispatch at BPA consisted of bilateral purchases of incremental and decremental capacity from existing commercial
generators to alleviate congestion by reducing power transmitted along a path and increasing the amount of generation closer to load.
NON-WIRES ALTERNATIVES: CASE STUDIES FROM LEADING U.S. PROJECTS 19NON-WIRES ALTERNATIVES
FIGURE 3: SOUTH OF ALLSTON 2017 SUMMER PEAK FLOWS
2017 PEAK FLOWS
3,300
100
3,100
2,900 80
DEGREES FAHRENHEIT
2,700
60
MWs
2,500
40
2,300
20
2,100
1,900 0
JULY 31 AUG 1 AUG 2 AUG 3 AUG 9 AUG 10 AUG 11 AUG 22 AUG 28 AUG 29
HE15 HE15 HE15 HE15 HE15 HE15 HE15 HE15 HE15 HE15
CONTROL DAY
COMMERCIAL TOTAL FORECAST FLOW ACTUAL FLOW POTENTIAL FLOW PORTLAND, OREGON
TRANSFER CAPABILITY W/O REDISPATCH TEMPERATURE
Note: HE15: Hour Ending 15 (the hour from 14:00 to 15:00)
Source: Bonneville Power Administration, 2018.
The South of Allston (SOA) pilot ran for two years CENTRAL HUDSON GAS & ELECTRIC—
and operated on a day-ahead, pre-schedule basis PEAK PERKS PROGRAM
on weekdays in the summer months of July, August Central Hudson’s Peak Perks Targeted Demand
and September to balance roughly 200 MW of Management Program was designed in
increased generation south of the transmission conjunction with the New York Public Service
line and 200 MW of reduced load north of the line Commission’s REV initiative. The program seeks
to reduce transmission constraints. to defer the need for new infrastructure in three
Outcome: The SOA project met BPA’s original targeted zones for five to 10 years, reduce future
objective to demonstrate that flows across SOA bill pressure for customers, and create additional
can be reduced during summer peak periods earnings opportunities for the utility.
through bilateral contracts. The 2017-2018 SOA The program consists of residential direct-load
project expenses were each within the $5 million control using two-way Wi-Fi thermostats and
per year transmission budget amount (compared one-way load control switches. A special initiative
to the originally proposed $1 billion transmission focused on industrial facilities and others that
line). BPA plans to leverage lessons learned from could make curtailment commitments and shut
the SOA Pilot to inform future longer-term, non- down their facilities when needed. Residential
wires program plans. customers with electric generators fueled by
propane and natural gas also received annual
payments to switch to their generators during
20 E4THEFUTURE | PLMA | SEPALoad Management Leadership
peak events. Itron provided participant recruitment to 52 MW of traditional and non-traditional
and program administration support, as well as resources. This project was designed to help delay
its cloud-based IntelliSOURCE software as the the construction of a new substation beyond initial
foundation for the project. load relief projections. This project on its own has
Outcome: In the first six months of the program, been a driver and leader for NWAs as other utilities
Central Hudson achieved over 30% participation and regulators learn more about the benefits
of eligible customers within Fishkill, the targeted resulting from this project and begin to explore
zone with the greatest capacity need. The utility opportunities themselves.
also exceeded the total first-year MW target for all Con Edison’s traditional approach to potential
three zones, achieving 5.9 MW of load reduction overload conditions would have been to construct
compared to the original target of 5.3 MW. a new area substation, establish a new switching
station, and construct sub-transmission feeders.
CON EDISON—BROOKLYN QUEENS Instead, Con Edison filed a petition with the New
DEMAND MANAGEMENT PROGRAM York Public Service Commission in July 2014
The Brooklyn Queens Demand Management proposing to implement the BQDM Program,
Program (BQDM) is one of the largest and most which would consist of 11 MW of non-traditional
well-known NWA projects in the U.S, with close utility-side solutions and 41 MW of traditional
FIGURE 4: EXAMPLE OF HOURLY LOAD REDUCTION PROVIDED BY DIFFERENT NWA RESOURCES
70
60
50
PEAK LOAD, MW
40
30
20
10
0
1 2 3 4 5 6 7 8 9 10 11 12 13 14 15 16 17 18 19 20 21 22 23 24
TIME OF DAY, HOUR ENDING
ENERGY NEW YORK STATE ENERGY RESEARCH NEW YORK CITY RESIDENTIAL FUEL
STORAGE AND DEVELOPMENT AUTHORITY HOUSING AUTHORITY LIGHTING PROGRAM CELLS
COMBINED HEAT AND POWER
MULTI-FAMILY ENERGY COMMERCIAL UTILITY-SIDED FORECASTED
EFFICIENCY ADDER PROGRAM DIRECT INSTALL SOLUTIONS NEED 2018
Source: Con Edison, 2018.
NON-WIRES ALTERNATIVES: CASE STUDIES FROM LEADING U.S. PROJECTS 21You can also read


