Swedbank Economic Outlook - January 2018 - "Swedbank" Žinių terasa
←
→
Page content transcription
If your browser does not render page correctly, please read the page content below
Swedbank Economic
Outlook
 January 2018

                      Completed: January 23, 2018, 17:00 CET
                    Disseminated: January 24, 2018, 08:00 CET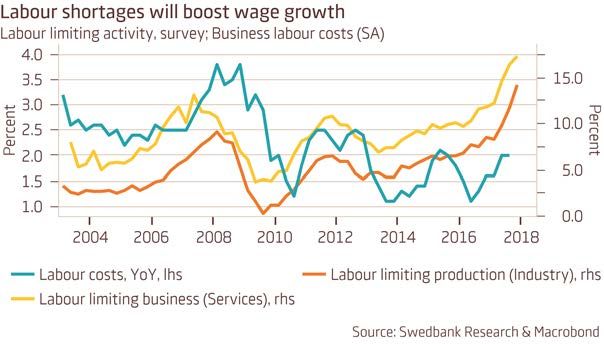
Welcome to Swedbank
Economic Outlook!
Swedbank Economic Outlook presents the latest economic forecasts for
Sweden, the Baltics and the major global economies. In a series of in-
depths, current issues that have a bearing on the economic developments
are analysed.

Swedbank Economic Outlook is a product made by Swedbank Macro Research.

Swedbank Research
Olof Manner
olof.manner@swedbank.se
Head of Research
+46 8 700 91 34

Macro Research

Sweden                           Maija Kaartinen                                Lija Strasuna
                                 maija.kaartinen@swedbank.se                    lija.strasuna@swedbank.lv
Anna Breman
                                 Research Assistant                             Senior Economist
anna.breman@swedbank.se
                                 +358 50 4688 759                               +371 6744 5844
Group Chief Economist
+46 70 314 95 87
                                 Jörgen Kennemar                                Linda Vildava
                                 jorgen.kennemar@swedbank.se                    linda.vildava@swedbank.lv
Oscar Andersson
                                 Senior Economist                               Junior Economist
oscar.andersson@swedbank.se
                                 +46 8 700 98 04                                +371 6744 42 13
Junior Economist
+46 8 700 92 85
                                 Ingrid Wallin Johansson                        Lithuania
                                 ingrid.wallin-johansson@swedbank.se            Nerijus Mačiulis
Martin Bolander
                                 Economist                                      nerijus.maciulis@swedbank.lt
martin.bolander@swedbank.se
                                 +46 8 700 92 95                                Chief Economist Lithuania
Senior Economist
+46 8 700 92 99                                                                 +370 5258 22 37
                                 Estonia

Cathrine Danin                   Tõnu Mertsina                                  Laura Galdikiené
cathrine.danin@swedbank.se       tonu.mertsina@swedbank.ee                      laura.galdikiene@swedbank.lt
Economist                        Chief Economist Estonia                        Senior Economist
+46 8 700 92 97                  +372 888 75 89                                 +370 5258 22 75

                                 Liis Elmik                                     Vytenis Šimkus
Jana Eklund
                                                                                vytenis.simkus@swedbank.lt
jana.eklund@swedbank.se          liis.elmik@swedbank.ee
                                                                                Economist
Senior Econometrician            Senior Economist
                                                                                +370 6945 71 95
+46 8 5859 46 04                 +372 888 72 06
                                                                                Norway
                                 Marianna Rõbinskaja
Josefin Fransson                                                                Øystein Børsum
                                 marianna.robinskaja@swedbank.ee
josefin.fransson@swedbank.se                                                    ob@swedbank.no
                                 Economist
Assistant                                                                       Chief Economist Norway
                                 +372 888 79 25
+46 8 5859 03 05                                                                +47 99 50 03 92

Åke Gustafsson                   Latvia
                                                                                Ingvild Almestad Aasen
ake.gustafsson@swedbank.se       Mārtiņš Kazāks                                 ingvild.aasen@swedbank.no
Senior Economist                 martins.kazaks@swedbank.lv                     Economist
+46 8 700 91 45                  Deputy Group Chief Economist/Chief Economist   +47 48 12 63 30
                                 Latvia
Knut Hallberg                    +371 6744 58 59                                Kjetil Martinsen
knut.hallberg@swedbank.se                                                       kjetil.martinsen@swedbank.no
Senior Economist                 Agnese Buceniece                               Senior Economist
+46 8 700 93 17                  agnese.buceniece@swedbank.lv                   +47 92 44 72 09
                                 Economist
Alexandra Igel                   +371 6744 58 75
alexandra.ext.igel@swedbank.se
Research Assistant
+46 73 999 42 15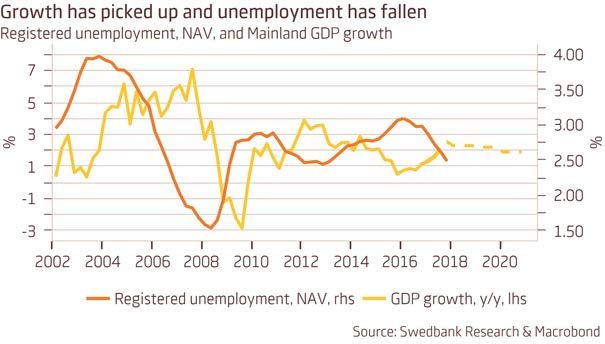
Table of content
Summary____________________________________________________________________________              4

Regions
United States_________________________________________________________________________ 6
Europe ______________________________________________________________________________ 7
Asia/Emerging markets_________________________________________________________________ 9
Sweden _____________________________________________________________________________ 11
Nordics ______________________________________________________________________________ 14
Baltics_______________________________________________________________________________ 17

Interest and exchange rate forecasts______________________________________________________ 20

In-depths
Sustainability Indicators________________________________________________________________ 22
Sweden vs. Norway housing – similar yet different___________________________________________ 24
Demographics and the reversal of falling interest rates________________________________________ 26

Appendices: Forecast tables _____________________________________________________________ 28
Information to client ___________________________________________________________________ 30

Recording date of price data 2018-01-18
The Swedbank Economic Outlook is available at: www.swedbank.com/seo.

                                                                     Cover image: Getty Images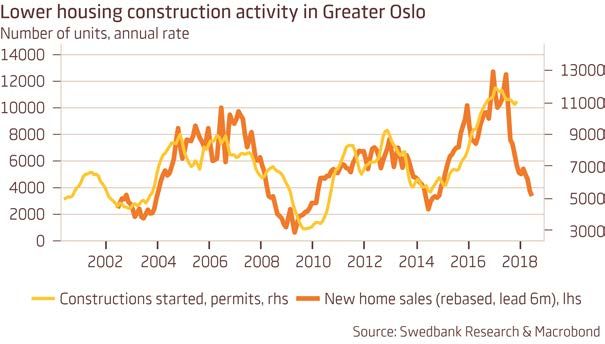
LEADER AND SUMMARY

               Global growth – impressive so far, pitfalls ahead
               As we enter 2018, the outlook for global growth is on a stronger footing. Euro
               area growth keeps improving, while the US has kept up speed. Emerging mar-
               kets are enjoying a positive momentum. The global cyclical upswing benefits the
               Nordic and Baltic economies. Political risks have abated somewhat, in particular
               in Europe. The rise of populism, however, still warrants concern as increased
               protectionism and geopolitical instability pose a risk to the short-run outlook.
               In the long run, populist policies could undermine political and economic
               institutions that are crucial for long-run growth prospects.

               Euro area coming out of a 10-year    The euro area recovery is gaining speed. Households have deleveraged
               slump                                after the financial crisis and the euro crisis. They are enjoying a firming
                                                    labour market. Employment is growing at 1.7% in annual terms, which helps
                                                    boost disposable incomes and household consumption. Firms are investing,
                                                    and exports have picked up markedly. France, Spain, and Germany are all
                                                    expected to deliver growth at 2% or above in 2018. The firming labour
                                                    market has been slow to deliver higher wages, and core inflation remains
                                                    low. Still, the ECB is sending increasingly upbeat signals, and asset purchases
                                                    have been scaled back. Towards the end of the year, we expect QE to stop,
                                                    and rate hikes to start in the second quarter of 2019.

               Federal Reserve raises rates as US   The US labor market remains robust, and the temporary factors that pushed
               business cycle is maturing           down inflation in 2017 will be reversed in 2018. This year, Jerome Powell,
                                                    nominated to replace Yellen as Chair of the Federal Reserve, is expected
                                                    to stay on course and deliver three rate hikes. The US midterm elections
                                                    towards the end of the year ensure that politics will remain in focus. The US
                                                    administration’s attacks on the judicial system, the democratic process, and
                                                    the free press in the United States risk harming the political and economic
                                                    institutions important to growth.

               Emerging markets show better         Growth is rebounding in several of the larger emerging economies. In Brazil,
               growth prospects                     the economic recovery, supported by higher global commodity prices, is
                                                    expected to continue in 2018-2019. The Russian economy stalled in the
                                                    second half of 2017, mostly due to weak manufacturing. The upward trend
                                                    in the oil price, however, is benefitting Russia, and we expect growth to
                                                    reach about 2% in 2018-2019. In India, the temporary negative effects of
                                                    reforms in 2017 have seemingly begun to wear off, and growth is set to
                                                    rebound in 2018-2019. In China, growth is stabilising around 6.5% as the
                                                    country benefits from stronger export growth; meanwhile, the transition
                                                    towards a more services- oriented economy is progressing.

               Nordics and Baltics enjoy strong     The Nordics are all benefitting from stronger growth in the euro area. In
               export demand, but domestic fac-     addition, trade flows among the Nordic and Baltic countries are strong,
               tors pose a risk
                                                    reinforcing a positive feedback loop. Notably, Finland is growing at a ro-
                                                    bust 3%. Denmark is still lagging somewhat, with growth expected to be

4
LEADER AND SUMMARY

                                     about at 2% in 2018-2019. Sweden and Norway are enjoying high levels
                                     of growth, but both countries face risks in terms of the cooling down of
                                     the housing market. The Baltics are benefitting from high productivity
                                     growth, strong exports, and high domestic demand. This bodes well for
                                     these countries, which are progressing well to catch up with the Nordics
                                     in terms of GDP per capita. For the Baltics and Sweden, Swedbank’s new
                                     Sustainability Indicators (see p.22) provide a comprehensive review of
                                     structural preconditions for medium-term growth and progress towards the
                                     UN Sustainable Development Goals.

Risks to global outlook still stem   The risks to the economic outlook stem predominantly from political fac-
from political factors and high      tors. High indebtedness and asset price correction, e.g., in the US, follow-
indebtedness
                                     ing years of low interest rates, also pose a risk. Many European countries
                                     remain heavily indebted. In China, it is the corporate sector that needs to
                                     deleverage, whereas in Sweden and Norway household debt has risen, a risk
                                     to growth if the labour market were to unexpectedly weaken and the fall
                                     in housing to accelerate. We expect, however, the current downturn in the
                                     housing market to stay contained to the larger cities in both Norway and
                                     Sweden and have limited effects on overall growth (see p.24).

                                     In terms of political uncertainties, heightened geopolitical tensions, such
                                     as an escalation of the US-North Korea tensions, or in the Middle East,
                                     pose a risk. Turkey is in a geographically sensitive area, and an escalation
                                     of conflicts in this region could affect stability in Europe. The Italian elec-
                                     tion in March could cause market turmoil, but, overall, we judge that the
                                     risks related to the election have diminished. Another risk is populism and
                                     potentially weaker institutions in the US and parts of Europe; this could shift
                                     global power towards less democratic nations. This will not slow near-term
                                     growth, but it remains a threat to long-run prospects for well-being.

                                     Swedbank’s global GDP forecast1/ (percentage change)
                                                               2016            2017F         2018F           2019F
                                     US                         1.5          2.3   (2.2)   2.6   (2.2)    2.0      (1.7)
                                     EMU countries2/            1.8          2.5   (2.3)   2.3   (2.1)    1.9      (1.8)
                                          Germany               1.9          2.5   (2.3)   2.4   (2.2)    2.0      (1.8)
                                          France                1.1          1.9   (1.8)   2.1   (1.8)    1.9      (1.9)
                                          Italy                 1.1          1.5   (1.5)   1.4   (1.3)    1.2      (1.1)
                                          Spain                 3.3          3.1   (3.1)   2.7   (2.6)    2.2      (2.3)
                                          Finland               1.9          3.1   (2.8)   2.5   (2.2)    1.9      (1.8)
                                     UK                         1.9          1.8   (1.6)   1.6   (1.5)    1.6      (1.6)
                                     Denmark                    2.0          2.0   (2.4)   2.0   (2.2)    2.0      (2.0)
                                     Norway (mainland)          0.9          1.9   (1.8)   2.1   (1.8)    1.5      (1.4)
                                     Japan                      0.9          1.8   (1.6)   1.4   (1.3)    0.9     (0.8)
                                     China                      6.7          6.9   (6.7)   6.6   (6.6)    6.3     (6.3)
                                     India                      7.9          6.5   (6.3)   7.3   (7.3)    7.6     (7.9)
                                     Brazil                     -3.5         1.1   (0.9)   2.5   (2.7)    2.4     (2.4)
                                     Russia                     -0.2         1.6   (2.0)   2.3   (2.3)    2.0     (2.0)
                                     Global GDP in PPP 3/       3.3          3.7   (3.6)   3.9   (3.8)    3.7     (3.7)
                                     1/
                                        Previous forecast in parentheses.
                                     2/
                                        Calendar adjusted.
                                     3/
                                        IMF PPP weights (revised Oct 2017)

                                                                                                 Sources: IMF and Swedbank

                                                                                                                                     5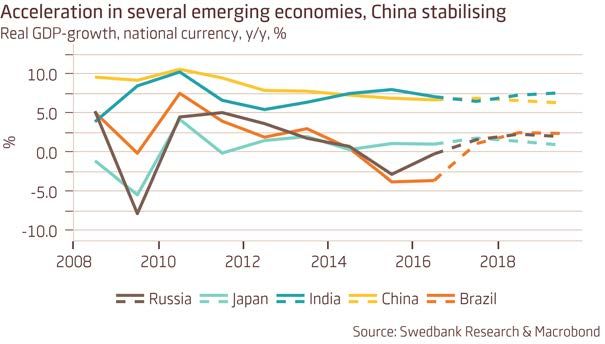
UNITED STATES

                    US – Tax reform gives short-term boost
                    The economy is enjoying a strong momentum with cheerful consumers and
                    investment plans suggesting that growth will turn higher. Tax reform provides a
                    further stimulus. The Fed will be raising its policy rate at a slightly quicker pace.
                    Political uncertainty remains, especially leading up to the midterm election.

                Growth forecast revised higher,       As expected, US growth turned higher in 2017 after a weak start. For 2017
                but tax reform will produce only a    as a whole it is expected to reach a healthy 2.3%. We have revised our
                short-term stimulus                   growth forecast notably higher in coming years, partly because 2018 has
                                                      begun with a tailwind. The tax reform that Congress passed just before the
                                                      holidays should, moreover, provide a fiscal stimulus in 2018. The tax cuts
                                                      boost our 2019 GDP forecast as well. On the other hand, the medium-term
                                                      impact of the reforms is likely to be negative, partly because the reforms
                                                      exacerbate the already large fiscal challenges.

                Consumption and investment are        Consumer spending, which represents about two-thirds of US GDP, has
                jointly driving the US economy        continued to grow at a good speed, and consumer confidence remains high.
                                                      Growth will probably hold steady in the light of wage increases and tax
                                                      cuts, although rising inflation and interest rates will be mitigating factors.
                                                      Changes to social programmes (“entitlements reform” in US parlance) are
                                                      a risk factor. Business investment picked up in 2017, and investment plans
                                                      remain expansive. The tax reform, which includes lower corporate tax
                                                      rates, is likely to provide further support. We see investment contributing
                                                      more to GDP growth going forward.

                A tight job market and rising         Full employment has essentially been reached in the US. According to many
                inflation will encourage the Fed to   indicators, one would have to go back to the early 2000sto find a similar
                continue with policy tightening       situation in the labour market. Unemployment has hit a 17-year low, while
                                                      the job vacancy rate remains at levels also not seen since 2001. Companies
                                                      are having a hard time recruiting at the same time even though they
                                                      want to hire. While it is true that jobs are still being created at a high pace,
                                                      labour shortages will become a more pronounced concern in the not too
                                                      distant future. The missing link is low wage inflation. While there are signs
                                                      of acceleration, this is from a low rate. Inflation was also low throughout
                                                      2017, though it, too, seems to be gradually rising. We believe that the
                                                      PCE (personal consumption expenditure) deflator, the Federal Reserve’s
                                                      preferred measure of inflation, will clearly rise, starting this spring. Growth
                                                      is also expected to speed up. Against this backdrop, we now expect the
                                                      Federal Reserve to raise the target interval for the federal funds rate three
                                                      times in 2018.

                Political uncertainty remains as      Uncertainty revolving around US politics, including economic policy,
                attention turns to the midterm        remains high. Controversy continues over the possible collusion of the
                election this autumn                  President and his close associates with Russia, and over how business is
                                                      being handled at the White House. The recent government shutdown is
                                                      a further symptom of the political polarisation. On top of this, a midterm
                                                      election will be held in November. The entire House of Representatives and
                                                      one- third of the Senate are up for re-election. While indications are that
                                                      the Democrats will see gains, this does not necessarily mean there will be a
                                                      power shift on Capitol Hill.

6
EUROPE

Euro area glitters while UK sputters and stutters
Strong and broad-based expansion in the euro area (EA) was a welcome
surprise last year. The economy is expected to sustain the momentum this
year, before decelerating in 2019. The ECB will end its asset purchases in
September and will start hiking rates gradually in 2019. Brexit uncertainties
continue to loom over the UK economy, but the Bank of England (BoE) will
again react to the persistently overshooting inflation and hike rates.

                                    Euro area
EA economy – firing on all cylin-   The economy is firing on all cylinders and continues to surprise positively.
ders                                Annual GDP growth accelerated to 2.6% (seasonally and calendar adjust-
                                    ed) in the third quarter of 2017 – the fastest growth rate in more than 6
                                    years. Leading indicators are pointing towards continued strong growth
                                    momentum this year. The composite PMI increased to 58.1 in December–
                                    the highest level in almost 7years, while the economic sentiment indicator
                                    reached its highest level in 17 years.

Export growth will ease             Growth last year was supported by recovering global demand and, thus,
somewhat on the back of appre-      strong export growth. Rising trade volumes boosted industrial confidence
ciating euro and serious capacity   to all-time highs in December. Export order-book levels continued rising
constraints                         despite the recent euro appreciation; however, “Ifo” export expectations
                                    moderated somewhat towards the end of last year. We expect export
                                    growth to ease somewhat this year, not least due to deteriorating price
                                    competitiveness, but also due to looming capacity constraints and, especi-
                                    ally, large labour shortages in numerous EA countries.

Picking up investment growth        After a temporary setback, growth in investment picked up in the third
– additional pillar to economic     quarter. Productive investments, like those in machinery and equipment,
growth                              exhibited the fastest growth. Supported by improved corporate balance
                                    sheets, still-cheap credit, high global demand, and high capacity utilisa-
                                    tion rates, growth in business investments is expected to accelerate this
                                    year. However, unexpected turns in political events remain the main risk to
                                    higher investment growth.

                                                                                                                            7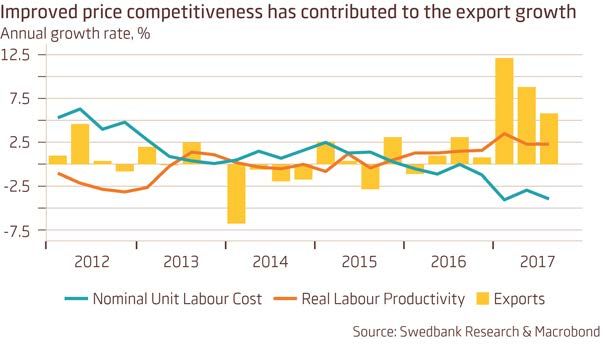
EUROPE

             Households are ripe for a splurge;    Household consumption picked up as well, supported by an improving la-
             wage growth to pick up                bour market and rising consumer sentiment. Growth in private expenditure
                                                   is expected to rise further this year - the lack of labour will finally translate
                                                   into higher wage growth, while the continued economic recovery will boost
                                                   employment growth. Meanwhile, reduced leverage and increased housing
                                                   wealth will limit consumers’ caution when opening their wallets.

             No asset purchases beyond             Considering all the aforementioned factors, core inflation is expected to
             September; expect first hikes next    pick up to 1.2% this year, while higher oil and other commodity prices will
             year                                  help push headline inflation to 1.6%. Inflation will be much closer to the
                                                   ECB’s target; thus, the governing council will not have enough arguments
                                                   to extend asset purchases beyond this September. This intention can
                                                   already be witnessed in comments by some high ECB officials. The ECB
                                                   may formally drop a pledge to keep QE open-ended as early as the March
                                                   meeting. We forecast that core inflation will increase to 1.6% in 2019 and
                                                   the ECB will gradually start raising its main refinancing rate in the second
                                                   quarter of 2019.

                                                   United Kingdom
             BoE responds to overshooting          After an initial setback in 2017, growth regained strength but is still below
             inflation and will hike rates again   previous years’. Private consumption rebounded in the third quarter, but
             despite Brexit worry                  the data probably are erratic, and the underlying pattern of a slowdown,
                                                   given weak real income, persists. Despite moving forward in Brexit nego-
                                                   tiations companies’ expectations have fallen, and business investments
                                                   may be modest due to remaining uncertainties. Stronger global demand
                                                   and a weak sterling; however, support export growth and dampen the
                                                   investment downturn. At present, Brexit negotiations are protracted, and
                                                   it seems that some former supporters have doubts and regrets. The best
                                                   and most likely outcome for the UK is a transition period during which it
                                                   will stay an EU member. However, we expect the deals to be agreed upon
                                                   in the last minute, and the UK will probably have to give in to EU demands.
                                                   Assuming an orderly Brexit and persistently overshooting inflation, the BoE
                                                   will hike the Bank rate again this year.

8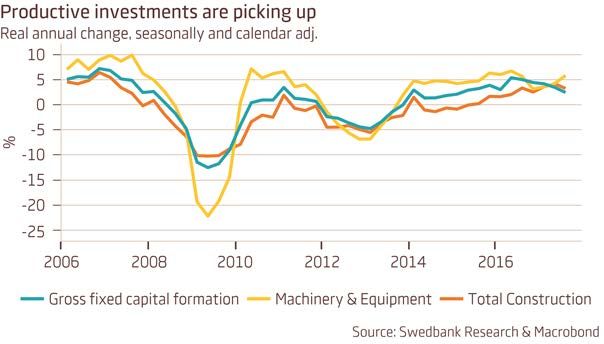
ASIA AND EMERGING MARKETS

Asia/Emerging Markets – Stabilisation in China
Growth is returning in several of the larger emerging economies. In China,
growth is stabilising near the new, more sustainable growth target. Economic
recovery continues in Brazil and Russia. In Japan, growth will continue above
potential, though at a slower rate in 2019 as compared with 2017. In India, the
temporary negative effects of reforms in 2017 have seemingly begun to wear
off. The possibility of renewed US-China trade frictions and the situation with
North Korea pose a risk, along with the outlook for Chinese financial stability.

                                      Japan
Growth in Japan will slow in 2019     Economic growth will remain above potential in 2018-2019, supported
as compared with 2017                 by healthy global growth and an expansive monetary policy. Exports and
                                      investment will remain supportive and consumption should strengthen,
                                      once real wages start growing. Economic growth is expected to slow as
                                      compared with 2017 due to capacity constraints. In 2019, retail sales will
                                      be affected by a planned sales tax hike. Inflation is slowly accelerating but
                                      is not even half way towards the central bank’s target; therefore, a hike in
                                      interest rates remains distant.

                                      China
Growth stabilising in China           Growth stabilised in 2017, and it is expected to gradually fall going into
with new sustainable focus, but       2018-2019. We also expect that the renminbi will stabilise in 2018 and app-
financial stability still a risk      reciate in 2019. As exports turned higher in 2017, China’s need for a weaker
                                      renminbi decreased. In the longer term, China aims to increase the global
                                      use of its currency, as well as its capital inflows. The Chinese leadership is
                                      therefore pleased with the stabilised renminbi.

                                      Supply-side reforms that resulted in increased industrial profits translated
                                      into a stabilisation of total credit growth in 2017. The Financial Stability
                                      and Development Committee held its first meeting in November, addressing
                                      the priority task of risk prevention. Total debt stabilised during 2017 and
                                      deleveraging is progressing, though this remains at an early stage. The new
                                      aim is to direct credit towards more productive sectors. The formerly over-
                                      heated housing market has cooled. Growth rate targets are now slightly
                                      compromised in favour of more sustainable growth.

                                      With the trade surplus against the US once again trending upwards, the risk
                                      for renewed trade frictions has returned in 2018, especially given the app-
                                      roaching midterm elections in the US, where this development may serve as
                                      an electoral issue. Currently, this issue, as well as the situation with North
                                      Korea, poses a risk, in addition to the evolving outlook on financial stability
                                      in the Chinese economy. President Xi Jinping further consolidated his power
                                      at the 19th National Congress of the Communist Party of China in October
                                      2017.

                                      India
Growth returning in India after ne-   We expect that the growth dampening in 2017 will be reversed in 2018-
gative effects of reforms in 2017,    2019. Third-quarter data showed that growth had returned, suggesting
but credit growth is still weak       that, the temporary negative effects of tax and demonetisation reforms
                                      in the beginning of 2017 have begun to wear off. Inflation seems to have

                                                                                                                                9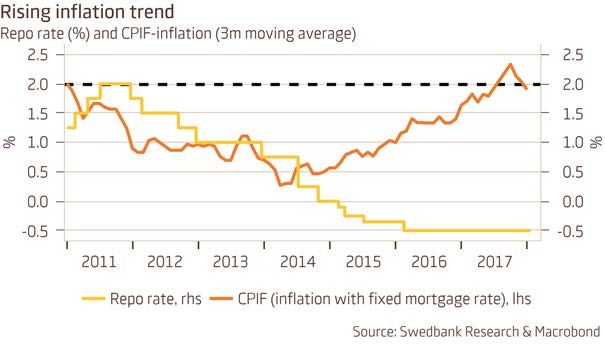
ASIA AND EMERGING MARKETS

                                                  bottomed out. The Reserve Bank of India, therefore, kept its policy rate
                                                  unchanged at the latest meeting in December. On the positive side, the
                                                  government proposed a plan in October to recapitalise the fundamentally
                                                  weak banking sector, aimed at addressing the limited lending capacity and
                                                  weak credit growth. Furthermore, the credit rating institute Moody’s un-
                                                  expectedly increased its rating for India in November. On the negative side,
                                                  the recovering oil price is weakening India’s terms of trade.

                                                  Brazil
             Recovery on the way in Brazil, but   The recovery that began in 2017 was supported by higher global commo-
             the general election in October      dity prices, and we expect that it continues in 2018-2019. In 2017, exports
             poses a risk to growth               turned up, which supported industrial production and growth. At the same
                                                  time, fiscal cuts addressing the growing public debt have further weakened
                                                  households in an economy with high unemployment and falling wages. Low
                                                  inflation has raised real wages, though, offering households and private
                                                  consumption some support. However, with an overall lower domestic de-
                                                  mand, investments have declined. To address the low inflation and further
                                                  boost a weak but recovering economy, the Central Bank of Brazil lowered
                                                  its policy rate by 6.75 percentage points in 2017. Political turbulence stem-
                                                  ming from political leaders’ involvement in corruption scandals remains; this
                                                  continues to halt the reforms, e.g., the budget-heavy pension reform, requi-
                                                  red to meet the budget deficit target. With the general election coming in
                                                  October, the challenge of passing necessary and efficient reforms will likely
                                                  increase, presenting a risk to growth.

                                                  Russia
             Russian recovery stalled in second   The recovery stalled in the second half of 2017, mostly due to weak manu-
             half of 2017, but to resume in       facturing. Hence, we cut the 2017 real GDP growth estimate to 1.6% (from
             2018                                 2%) but retain 2-2.3% growth for 2018-2019. Other sectors are slowly im-
                                                  proving: construction is bottoming out, the investment rebound continues,
                                                  and the tighter labour market supports retail. With inflation at a historic
                                                  low of 2.5%, the Central Bank of Russia will continue to ease, cutting its
                                                  policy rate from the current 7.75% to 6.5% by end-2018. The banking
                                                  troubles have so far had a minor impact on other sectors. Watch out for the
                                                  risk of new, individually targeted sanctions after the US Treasury report in
                                                  February. Putin will be re-elected President - no change in foreign policy
                                                  expected.

10
SWEDEN
Sweden – Soft landing due to strong exports
Last year ended with positive economic signals from outside the country and
rising global growth - both of which are benefitting Sweden. The industrial pro-
duction has accelerated at the same time as the services sector is staying strong.
Yet, 2018 contains several domestic uncertainties. Will the Riksbank raise the repo
rate this year? What will happen to the housing market? 2018 is also an election
year – how will that affect financial markets and the economy?
The Swedish economy stands Prospects for Swedish growth are good in the short term. Employment con-
strong, and a notable slowdown in tinues to rise, fiscal policy is expansionary, with hefty spending on families
housing investment is not antici- with children and pensioners, and the global economy continues to make
pated to have a significant effect progress. This suggests that the Swedish growth rate will stay high this
this year year, even as housing investment declines.
Lower house prices of late and general uncertainty about the housing mar-
ket are expected to continue. A large supply of new housing in 2018 and the
stricter amortisation requirements mainly affect metropolitan areas, whe-
re prices could fall further, mainly for tenant-owned flats. But with a solid
increase in disposable incomes and a strong job market, we see house prices
stabilising for Sweden as a whole in 2018. For single-family homes outside
metropolitan areas, we expect a slight price increase this year.
Lower housing investment is com- A subdued housing market is affecting GDP growth through fewer housing
pensated for by robust business starts. The decline in housing investment is cushioned, however, by in-
and public investment vestments in renovations and the completion of building projects begun in
2016-2017, which are generating investment throughout the construction
process. It is not until 2019, therefore, that we will see the impact of lower
construction, when we estimate housing investment will drop by nearly
2% on an annual basis. The Swedish economy has thus timed the global
economic turnaround well, especially since it supports business invest-
ment, which had already turned higher last year – a trend we anticipate will
continue.
11SWEDEN
Exports turn higher thanks to Stronger global economic conditions and a favorable mix of investment and
improved global demand and intermediate goods will pave the way for higher export growth in 2018.
favourable mix of goods In 2018 and 2019, foreign trade is expected to positively contribute to
GDP, as exports grow for more sectors, while domestic demand slows. The
challenge for exporters will be to address likely higher unit labour costs and
a slightly stronger krona in 2019, which will make them less competitive.
The heyday for consumers is not In the annual budget, spending increases were targeted at, among oth-
over yet – good disposable income, ers, pensioners and families with children – i.e., households with a high
partly thanks to strong labour propensity to consume. In combination with a strong labour market and
market inflation that is staying just above target, we expect a generally strong
trend in disposable incomes this year. We see good consumer spending
growth, which shifts over to housing and “necessities”; at the same time,
service consumption will stay robust. Instead, it is spending on durables
that will lose ground, with car sales leading the way. Another reason for
the slowdown is the very high savings rate. An increase in amortisations,
high contractual savings, given the labour market’s strength, and an aging
population will support savings in the near term.
Internal and external security, Despite the expansionary fiscal policy this year, Sweden has a large budget
education, and health care will surplus. We expect public investment to stay at high levels as defense
top the agenda in this year’s spending grows. In addition, demographic factors and a population increase
parliamentary election are contributing to continued high investment in municipalities and county
councils. These entities are also expected to continue raising their spen-
ding, since most new immigrants who arrived in 2015 have by now been
placed in municipalities. Public services catering to this group will therefore
count as municipal consumption rather than central government consump-
tion.
A fragmented parliament and dif- A parliamentary election will be held in September. Recent polls indicate
ficulty forming a strong govern- that voters are split. A complicated outcome is likely. In light of the govern-
ment are a likely outcome after ment’s strong finances, this could mean more expansionary fiscal policy
the election than usual after an election.
To achieve sustainable develop- The turmoil around the world in recent years has proved that political
ment, Sweden has to speed up its events can be just as important to the financial markets as statistics and
reform process rate decisions. The Swedish election is not expected, however, to provi-
de the same drama as those in the UK and the US. In the short term, it is
12SWEDEN
unlikely that the Swedish election will affect economic development or the
financial markets at all. Instead, the risk is that a divided parliament will
not be able to get the needed reforms done. A poorly functioning housing
market, slow integration of immigrants, and an education system that does
not match the needs of a competitive economy are all major challenges.
Swedbank’s new “Sustainability Indicators” (see page 22) clearly show that
Sweden has to speed up the reform process to achieve sustainable develop-
ment.
Repo rate hike in sight
The Riksbank is likely to announce The rest of the world is firing on more cylinders, at the same time that do-
its first rate hike in July mestic resources are being stretched. Compared with the picture the Riks-
bank painted a year ago, when risks were mainly negative, this is entirely
different. Wage increases picked up slightly last year and will continue to
rise in 2018 and 2019. The combination of an increase in other labour costs
with a labour force that is getting only marginally more productive means
that unit costs will rise in coming years. This increase, combined with higher
oil prices, will contribute to rising price pressure in 2019. We estimate that
inflation will reach 2% at the end of next year after falling in 2018 due the
comparatively high inflation during the same months in 2017.
We think the Riksbank is ready to raise the repo rate even if inflation this
spring temporarily stays a bit below the 2% target. An upward inflation
trend, coupled with cautious tightening by global central banks, supports
this course of action. Taken together, we therefore see the repo rate being
raised in July to -0.40%. In October, the rate is expected to be raised again,
to -0.25%, to be followed with three hikes of 25 basis points each in 2019.
13NORDIC S
Nordic countries – Continue to improve
The economies of the Nordic countries continue to improve. Growth in the
Norwegian economy has strengthened even as house prices fall. Household
demand and a tightening labour market are bolstering the Danish economy.
Improved price competitiveness is contributing to Finland’s export growth,
while robust private consumption comes in support of a diminishing saving rate.
The Nordic economies continue to gain from stronger growth in the euro area.
Norway
Growth has strengthened even as Growth in the Norwegian economy has picked up significantly as the down-
house prices fall turn in the oil sector has ended. Oil investments and manufacturing produc-
tion stabilised last year, and surveys now indicate growth. This outlook is
supported by rising oil prices in recent months. With strong global demand
and a weak Norwegian krone, tourism and other export-related businesses
will continue to grow. Unemployment is falling, consumer confidence is
rising, and household demand has gained in strength even as house prices
fall.
House prices fell through most of last year, but mostly for apartments in
the three largest cities; meanwhile, prices in areas outside the cities are
actually rising. This suggests developments are not the start of a broad
downturn in the housing market, but rather a function of high construction
activity, as well as tighter credit constraints. Recent data show that both
existing home sales and credit growth are keeping robust, indicating strong
demand.
14NORDICS
Lower housing construction acti- We judge the longer-term fundamental factors as sound and supported by
vity will dampen growth improving macroeconomic developments; however, we expect apartment
prices to decline further in the short term in the major cities as many units
under construction will be completed. New home sales will take time to pick
up, and, as a consequence, construction activity will peak and likely dampen
GDP growth going forward. But we expect other parts of the economy to
remain strong, such that overall GDP growth will keep up quite well.
Denmark
Growth outlook is good The Danish economy has enjoyed robust growth in recent years on ac-
count of household spending, business investments and growing exports.
The expansion looks set to continue, due to high consumer confidence
and improving business barometers. The export outlook remains good as
growth has strengthened further in the euro area. Employment continues
to expand. We see the reported fall in GDP in the third quarter of last year
as transitory and expect growth to remain at 2% in the years ahead.
Capacity utilisation is rising but no Falling underlying unemployment is evidence of higher capacity utilisa-
signs of overheating tion. Signs of a shortage of labour have become more widespread but are
not acute. Wage growth remains modest, just as in many other countries.
Although total consumer price inflation has been below 1% most of the
time since 2013, it rose over the past year towards 1.5% on account of
higher energy prices. We expect inflation to be sustained by gradually
tighter conditions in both product and labour markets as resources become
increasingly scarce.
Several policy issues must be To ensure continued growth and stability in the coming years, the govern-
addressed to ensure continued ment must address several policy issues. It is critical to stimulate labour
growth and stability supply, otherwise fiscal policy will have to be tightened more to keep the
economy from overheating. The continuing house price growth and high
household indebtedness raise concerns for financial stability. The govern-
ment has enacted several measures to dampen house price growth and
reduce vulnerabilities, but more can be done with respect to taxation,
valuation schemes, and macroprudential policies.
15NORDICS
Finland
Export outlook for Finland rema- In 2017, economic growth in Finland accelerated to 3.1%, the fastest pace
ins favourable in 2018 of the last nine years. Production capacity and the turnover of Finland’s
business sector have expanded, whereas improved price competitiveness
and stronger foreign demand are contributing to export growth. Although
demand from Finland’s trade partners peaked last year, it is expected to
remain relatively strong in 2018 and offer good growth opportunities for
exporting sectors. Increased new orders in manufacturing confirm the
continuation of export growth momentum, at least in the short term.
Private consumption maintains Investment growth in construction is decelerating, while foreign demand,
good growth in 2018 the expanded production, and several major industrial projects will maintain
robust growth in private investments. Private consumption has increased
at the expense of households’ diminishing saving rate. Increased consumer
confidence, gradually rising employment, and decreasing unemployment
rates are expected to keep household consumption strong this year, but
wage moderation and gradually accelerating inflation will slow it down in
2019.
Longer-term perspective of Fin- According to our forecast, Finland’s GDP growth decelerates to 2.5% in
land’s public finances is challen- 2018 and to 1.9% in 2019. The strong economic growth and comprehen-
ging sive reforms will help to reduce Finland’s government debt and budget
deficit in the coming few years, but the increased expenditures related to
the ageing population will be a major challenge for public finances from the
longer-term perspective.
16BALTICS
Baltic countries – peaking growth, but balanced
and resilient
Growth has peaked for this cycle, but it will remain above potential this year
before slowing to more sustainable rates in 2019. Exports and investment
will continue to benefit from global tailwinds. Domestic demand will
increasingly contribute to growth. Labour markets will keep tightening, but
rising productivity partly helps to outweigh strong wage growth. Inflation has
accelerated due to global commodity price growth, local tax hikes, and wage
growth.
Estonia
In 2017, economic growth in Esto- Economic growth in Estonia accelerated to 4.4% in 2017, the fastest pace
nia accelerated to the fastest pace since 2011. The growth was broad based and supported both by foreign
of the last five years demand and economic activity on the domestic market. Stronger economic
activity has increased the demand for labour. At the same time, the number
of job vacancies has risen, and the shortage of labour has become an increa-
singly serious problem.
We expect that GDP growth will We expect that GDP growth will remain strong in 2018, increasing to close
remain strong in 2018 to 4% in real terms. Robust foreign demand and rising export prices are
allowing Estonian enterprises to increase their export turnover. The govern-
ment sector will continue to raise its investments with the support of the EU
structural funds. However, at this point in the growth cycle, such a strong
fiscal stimulus to the Estonian economy is wrongly timed.
Robust demand and increased in- Robust demand and increased investments contribute to productivity
vestments contribute to produc- growth. Although the tight labour market will maintain fast wage growth,
tivity growth the changes in income taxation could lower wage growth expectations.
We expect that productivity growth will exceed wage growth in 2018 and
2019. This will help to improve Estonian enterprises’ profitability and slow
the deterioration of their price competitiveness against trade partners. The
households’ financial situation is expected to remain strong. Average pur-
chasing power of households will improve with the support of the increase
in their nontaxable income, and this should give stronger momentum to the
growth of private consumption in 2018.
17BALTIICS
We forecast that GDP growth will decelerate to 3% in 2019, primarily due to
cyclical factors. Because of the openness of the Estonian economy, the main
downward risks to the current baseline scenario are related to the external
environment.
Latvia
Broad upswing continues; do- The strong cyclical upswing continued in Latvia throughout 2017 and
mestic demand takes over as key into 2018. Real GDP growth of 5.8% in the third quarter was the peak of
driver of growth the cycle. Confidence is robust across the board. With the business cycle
maturing, growth will go downhill but in 2018-2019 will still remain strong
and above its medium-term potential of 2.5-3%.
All sectors are expanding, except for financial intermediation (transitory
fall caused by offboarding of nonresidents due to tighter know-your-client
and anti-money-laundering regulations) and agriculture (hurt by rainfall).
Heavy rainfall hampered log supplies to the wood processing industry in
2017, which may weaken exports in early 2018, but, with strong global
demand continuing, the general outlook for exports of goods and services is
good, and we forecast solid 4-4.5% volume growth in 2018 and 2019.
Strong investment activity to Gross fixed capital formation has shot up by 20%. About 40% of the rise is
continue to limit labour market likely due to Air Baltic’s renewing its fleet; thus, the investment recovery
pressures and cover for past for the overall economy is less spectacular. High capacity utilisation, inflows
underinvestment of EU funds, and an upturn in the mortgage credit cycle will yield double-di-
git investment growth also this year and the next. Construction, which was
the fastest-growing sector in 2017, will remain such in 2018.
Tight labour market and pro-cycli- The labour market remains the hotspot of this business cycle. In 2017, the
cal fiscal policy to boost consumer growth in wages was matched with a rise in productivity, but productivity
spending is unlikely to keep up the pace, and risks to competitiveness will build up.
Tighter labour market supports consumer spending, which in 2018 will be
additionally boosted by a rise in the minimum wage (up 13%) and labour tax
cuts. Fiscal policy is mildly pro-cyclical as politicians gear up for the October
2018 general election. We do not foresee major U-turns in economic policy
post-election, but with the election approaching, the reform agenda is likely
to suffer. No major imbalances are present, and strong growth is set to
continue. Hence, do not worry, be happy… for now.
18BALTICS
Lithuania
Growth peaked at 3.8% last The Lithuanian economy remained on strong footing at the end of 2017
year and is set to ease towards and probably expanded for the year at a rate of 3.8%. The main source of
potential output growth last year and in the final quarter was an impressive expansion of
foreign trade – estimated real annual growth of exports of goods and servi-
ces was 12%. Even more impressive was the growth of exports of services
last year, when its value increased more than 20%.
Investments grew slightly more slowly last year – at an estimated 7% - but
this was still a nice recovery after the contraction in the previous year.
During the past two years, investments were dragged down by the public
sector, but it seems the trend has been broken – nominal public sector
investments increased by 25% in the third quarter of last year. Investments
are likely to continue boosting overall GDP growth in 2018, as the pace of
distribution of the EU structural funds finally picks up.
Household consumption growth is Household consumption increased by an estimated 4% last year. Although
being dragged down by demo- consumption growth somewhat eased in the second half of last year, it is
graphics, but the worst of emigra- expected to continue growing at a similar pace in 2018. Overall household
tion is in the past consumption is dampened by negative demographic trends, but, on an
individual level, most households are doing fine – average wage growth
was close to 8% last year. Emigration seems to be easing, while immigration
continues picking up. In December 2017, for the first time in this century,
immigration was higher than emigration. Even though this may have been a
blip, the worst of net emigration is in the past.
The overall economy remains very well balanced and resilient. Foreign trade
was close to a record surplus last year – at 1.9% of GDP – while the current
account was in balance. The general government budget was in surplus
for the second year in a row and is planned to remain in surplus again in
2018. The private sector has very low debt-to-income ratio, while housing
affordability and other indicators show that there are no bubbles in the
residential real estate market. Unlike in 2008, the private and public sectors
are very well positioned to withstand even large external shocks.
19EXCHANGE AND INTEREST RATES
Exchange and Interest Rates
The policy direction of central banks is clear: a gradual removal of policy stimu-
lus has begun. This normalisation is expected to continue and will affect market
interest rates, as well as exchange rates. Interest rates are rising, and we see a
progressively stronger krona, as well as euro, during the forecast period.
Central banks’ cautious normalisation of policy continues
The Riksbank will start hiking The US central bank, the Fed, has begun normalising monetary policy by
rates very cautiously raising the federal funds target 125 basis points (bp) since its post-crisis
low. The central bank has also started reducing its bond holdings. We expect
this to continue in the near term, and, with a slightly more ”hawkish” FOMC
committee, we foresee that the Fed will increase its policy rate three times
in 2018. This is a slight upward revision compared to our previous forecast.
A somewhat higher inflation rate, combined with the tight labour market,
will be a central focal point for the Fed. A pickup in economic growth within
the euro zone will also make the ECB slightly more hawkish, and we expect
the ECB to end net asset purchases by September. The ECB will continue to
focus on inflation developments and the strength of the recovery, as well as
the euro exchange rate. The Riksbank will maintain an eye on the krona ex-
change rate and imported inflation. However, we expect that the Riksbank
will begin lifting the repo rate in mid-2018. It will start cautiously, with a
hike of 10 bp, followed by a further hike in October of 15 bp, thereby ending
the year with a repo rate of -0.25 percent. In 2019, we foresee three hikes
of 25 bp each.
Monetary policy sets tone in fixed-income markets
Raising long-term rates, but The central banks’ varying pace in normalising monetary policy will be the
rates will stay low by historical key factor affecting long-term interest rates. In the short term, we expect
standards yield curves to steepen as short-term rates are anchored by policy rates.
Thereafter, as policy rates are raised, we expect yield curves to flatten aga-
in. The differences in timing of the central banks’ actions will be important
to determine interest rate spreads and curvature developments. Throug-
hout the forecasting horizon, long-term interest rates will, however, remain
low by historical standards. Swedish government bond yields will also be
held down by a limited free float of bonds. In terms of peripheral spreads,
the political risks in Europe have diminished, and the cyclical upswing in the
euro area has gained momentum. Nonetheless, one should not completely
rule out the political risk, which could widen peripheral spreads.
Policy rate differentials and short-term market rates affect ex-
changes rates
Gradual strengthening of the Central bank policy also continues to be the major driving force in the cur-
krona and euro rency markets. In the short term, interest rate differentials will support the
US dollar, although recent strong developments in euro area and a slightly
more hawkish ECB will limit the downside in the euro-dollar movements. In
the longer term, we foresee a gradually strengthening of the euro. As the
Riksbank will begin to raise the repo rate, we also expect the Swedish krona
to strengthen. The Norwegian krone will stabilise in the near term, suppor-
ted by a higher oil price and stabilising house prices. Uncertainty surroun-
20EXCHANGE AND INTEREST RATES
ding Brexit will cloud the outlook for the UK pound. We moreover expect
emerging market currencies to strengthen gradually, supported by brisker
global growth and higher commodity prices.
Commodity markets
Oil prices have risen as demand The oil market returned to balance last year, and stock levels continue to
strengthens decline. Stronger global demand and continued production restraint in
OPEC and Russia have driven up the Brent oil price to almost 70 USD/barrel.
Increased tensions in the Middle East have also contributed to push up pri-
ces. We have revised up our estimates for the oil price to 64 USD per barrel
in 2018 and 59 in 2019, as US shale oil is now growing at a high rate again
and US petroleum exports are booming. At the same time, investments in
conventional production have been severely reduced, and the production
shortfall could turn out to be larger than expected.
Interest and exchange rate forecasts
Outcome Forecast
2018 2018 2018 2019 2019
18.JAN 30.JUN 31.DEC 30.JUN 31.DEC
Policy rates (%)
Federal Reserve, USA 1/ 1.50 1.75 2.25 2.50 2.50
European Central Bank 2/ 0.00 0.00 0.00 0.25 0.50
Bank of England 0.50 0.50 0.75 1.00 1.25
Riksbank -0.50 -0.50 -0.25 0.00 0.50
Norges Bank 0.50 0.50 0.50 0.75 1.00
Bank of Japan -0.10 -0.10 -0.10 -0.10 -0.10
Government bond rates (%)
Sweden 2y -0.34 -0.10 0.35 0.70 0.90
Sweden 5y 0.26 0.65 1.25 1.45 1.55
Sweden 10y 0.86 1.15 1.60 1.90 2.00
Germany 2y -0.59 -0.45 -0.10 0.35 0.65
Germany 5y -0.12 0.10 0.60 1.05 1.35
Germany 10y 0.52 0.80 1.20 1.65 1.85
US 2y 2.05 2.20 2.60 2.65 2.65
US 5y 2.43 2.75 3.00 3.10 3.10
US 10y 2.62 3.00 3.20 3.30 3.30
Exchange rates
EUR/USD 1.22 1.20 1.22 1.24 1.25
EUR/SEK 9.81 9.50 9.35 9.25 9.10
USD/SEK 8.03 7.92 7.66 7.46 7.28
KIX (SEK) 3/ 112.8 109.6 107.4 106.1 105.7
EUR/NOK 9.60 9.41 9.17 9.07 9.01
NOK/SEK 1.02 1.01 1.02 1.02 1.01
EUR/GBP 0.88 0.92 0.94 0.94 0.92
USD/CNY 6.44 6.60 6.55 6.60 6.50
USD/JPY 110.3 115.0 115.0 120.0 115.0
USD/RUB 56.8 55.0 53.0 51.0 50.0
1/
Upper Bound
2/
Refi Rate
3/
Trade-weighted exchange rate index for SEK. A higher value of the index means that SEK
has depreciated.
Sources: IMF and Swedbank
21IN-DEPTHS
Sustainability indicators
Swedbank has developed a new methodology, Sustainability Indicators, to monitor
the progress towards the 2030 Agenda. There is much unused business potential
in Sweden and the Baltics in advancing sustainability, e.g., in making the transition
to cleaner and more energy-efficient economies. The aim is to support business
looking at ESG (environmental, social, governance) criteria and help to identify
weaknesses and strengths in Sweden and the Baltics. We find that Sweden has to
speed up to remain among the leaders in Europe, while the Baltics have a lot of
catching up to do.
Progress towards UN SDGs, % of benchmark*
Estonia Latvia Lithuania Sweden
Preconditions for sustainable medium-term growth1/ 71 61 64 90
Social inclusion2/ 56 55 55 89
Environmental protection3/ 58 72 70 82
Governance and institutions 4/
70 51 62 97
Downward/stable trend during last 5 years (4 years for governance) – ↓
* Benchmark is 90/10th percentile of EU28 in 2015. In total 40 indicators covering 14 from 17 SDGs, aggregated to four pillars.
Cut-off points for traffic lights - Sweden: >90% for green, 70-90% for yellow, Baltics: >80% for green, 60-80% for yellow
1/
SDGs #4, 8, and 9: education, labour force participation, employment, and innovations
2/
SDGs # 1, 3, 5, and 10: income and gender inequality, poverty, and health
3/
SDGs # 6, 7, 11, 12, 13: water supply, energy intensity, renewable energy, sustainable cities, waste generation, and GHG emissions
4/
SDGs # 16, 17: government effectiveness, rule of law, corruption perception, regulatory quality, AML, and official development assistance
Focus on sustainable development Sustainable business is going mainstream worldwide. Demand for en-
creates many business opportu- vironmentally friendly products and services is growing, as well as socially
nities responsible investments, especially among millennials. There is also a push
from new regulations and global arrangements (e.g., the Paris climate
agreement). New business/investment opportunities in many sectors are
being created as a result – renewable energy capacity is expanding, electric
cars are soon to be the norm, big data are used for sustainability ratings of
companies, and new finance instruments are being developed.
UN SDGs as a point of departure to To assess long-run sustainability in Sweden and the Baltics and to see
assess sustainable development where the biggest potential for improvement is, we take the 17 UN Sus-
tainable Development Goals (SDGs), a part of the 2030 Agenda, as a point
of departure. We have selected 40 indicators, covering 14 out of 17 SDGs,
and grouped them into four sustainability pillars: sustainable medium-term
growth, social inclusion, environmental protection, and governance. To
assess and compare progress in these areas, we use EU28 90th or 10th per-
centiles (depending on whether a maximum or minimum is relevant) in 2015
as a benchmark and calculate how far the countries have come towards the
benchmark. We calculate the average for each of the four pillars. We assign
a traffic light colour, depending on how likely countries are to reach these
benchmarks by 2030. This shows which areas require the biggest action and
simultaneously provide the largest opportunities. A more detailed methodo-
logy/analysis can be found in our Macro Focus here.
22IN DEPTH
Peer pressure (sustainability as a part of a competitive offer) and policy
pressure (sustainability disclosure) for the companies are growing. Among
the potential benefits of integrating sustainability into business (including
measuring sustainability-related performance) are the following:
• cost efficiencies (e.g., energy) and better risk management (legal
claims and reputational risks);
• innovation and productivity growth, leading both to cost savings
and better revenue streams (access to new markets, new product deve-
lopment); and
• talent development and retainment (employee satisfaction and
engagement, equal opportunities).
Opportunities, though, do not present themselves without risks. The ne-
cessary shift to a low-carbon economy results in a reallocation of resources
and a revaluation of assets, which can pose risks to financial stability and
present challenges for regulators and central banks in safeguarding the resi-
lience of the financial system and developing a proper framework to finance
the transition. The shift itself does not come for granted – emission targets
to moderate climate change are ambitious, and there are already backslas-
hes in commitment from some politicians (read: Trump).
Largest potential in environmen- The Sustainability Indicators show that Sweden has to speed up to remain
tal protection in Sweden among the leaders in Europe. Three out of the four traffic lights are yellow,
and the only green one, governance, shows a negative trend. Sweden enjoys
high scores for social inclusion, but the situation with respect to income
inequality and poverty has been worsening in the last few years. As for the
growth pillar, education is a challenge – for some indicators, Sweden even
lags some of the Baltic countries. For the environmental protection pillar, the
largest improvements are necessary in the areas of resource productivity
and waste generation.
Largest potential in social inclu- The Baltic countries have a longer way to go. Still, the improvements, partly
sion in Lithuania, environmental driven by economic recoveries, during the last five years in all pillars, except
protection in Estonia, and gover- social inclusion, have been remarkable. The largest differences between
nance in Latvia countries are for the governance pillar, while the smallest differences and
lowest scores are for the social inclusion pillar. Gender inequality seems to be
a larger challenge for Estonia, while Latvia and Lithuania struggle more with
income inequality, poverty risk, and maternal mortality. As for the growth
pillar, innovations and lifelong learning for adults constitute the most
pressing problems for both Latvia and Lithuania; meanwhile, in Estonia, the
number of patents is very small despite higher R&D expenditure. For the
environmental protection pillar, Estonia scores the worst on many indicators
due to its polluting shale oil industry.
Overall, Swedbank’s Sustainability Indicators show that the state, civil socie-
ty and business sector must work together for strengthened environmental
protection and social cohesion in order to attain Agenda 2030. Long-term
sustainable economic development goes hand in hand with better pre-con-
ditions for a sound environment, social cohesion and strong democratic
institutions.
23IN-DEPTHS
Sweden vs. Norway housing – similar yet different
After years of strong growth, Norway and Sweden both saw a downturn in house
prices in 2017. We expect that a large supply of new homes and tighter mortgage
credit regulations will continue to dampen house prices this year. But the overall
economic situation is good, and spillover effects to the real economy will be
limited in both Norway and Sweden. However, favourable external factors can
shift. Therefore, in terms of risks, differences in the housing markets suggest that
the Norwegian economy is more vulnerable than its neighbour.
The overall macroeconomic environment is favourable in Sweden and
Norway. The global economy is enjoying a synchronised cyclical upswing,
benefitting the Scandinavian economies. Strong labour markets and expan-
sionary fiscal and monetary policy imply high growth in disposable income.
Household confidence and consumption growth remain strong. The interest
burden is a historically small share of income; it will remain small despite hou-
seholds’ strong preference for floating mortgage rates and the anticipation
of slowly rising interest rates. Banking systems in both countries are well
capitalised and well supervised, with generally sound lending practices. In
addition, strong public finances in both Sweden and Norway can be mobili-
sed if push comes to shove.
A shift in the market balance, with The cooler housing markets in Sweden and Norway are thus not a consequ-
large supply of housing in both ence of changes in fundamental demand. Instead, the downturn is primarily
countries driven by the increase in supply and tightened macroprudential policies,
limiting mortgage credit. As a result, the downturn is mainly concentrated in
metropolitan areas, where new construction of, especially, flats is high, and
debt-to-income ratios are the highest. For example, prices are down more
than 11% from the peak in Oslo, while Stockholm flat prices have fallen 10
% from their seasonally-adjusted peak . Swedbank’s forecast for the year
ahead remains that a stabilisation of housing prices is likely for the two
countries as a whole. However, favourable external factors can shift. It is,
therefore, important to assess risks in the Scandinavian markets.
Severe macroeconomic effects from the housing market downturns can
generally be seen as emanating from three channels: (1) the impact on the
banking sector from falling collateral values, resulting in a credit crunch;
(2) the direct and indirect impact of a reduction in residential investment in
the wake of uncertainty regarding prices; and (3) the impact of households
reducing consumption as their preferences for savings increase.
Strong banking systems in both First, although the conventional banking channel of transmission from
countries works as a buffer, but the housing market to the real economy appears limited for both Sweden
macroprudential tools may backfi- and Norway, authorities in both countries have in recent years tightened
re in short run regulations on the banking sector. These include macroprudential policies
that directly target mortgage lending. Most recently, Norway tightened
limitations on mortgage lending in early 2017, while in Sweden higher
amortisation requirements based on debt-to-income ratios will soon enter
into force. These restrictions can, in a qualitative sense, be compared with a
24You can also read


