THE STATE OF FASHION 2020 - CORONAVIRUS UPDATE - MCKINSEY
←
→
Page content transcription
If your browser does not render page correctly, please read the page content below
The State of
Fashion 2020
   Coronavirus Update
The State of Fashion 2020 — Coronavirus Update

2
CONTENTS

Introduction									6

                                                                       ECONOMY
                                                                        GLOBAL
GLOBAL ECONOMY
01: Survival Instincts 								10

CONSUMER SHIFTS

                                                                       CONSUMER
02: Discount Mindset							16

                                                                        SHIFTS
03: Digital Escalation								20
In-Depth: For Luxury, an Acceleration of the Inevitable			        24

FASHION SYSTEM                                                         FASHION
                                                                        SYSTEM

04: Darwinian Shakeout							28
05: Innovation Imperative							32
In-Depth: Fashion Looks to China for a Glimpse of Its Future 		   36

Glossary and Detailed Infographics						42
Endnotes									44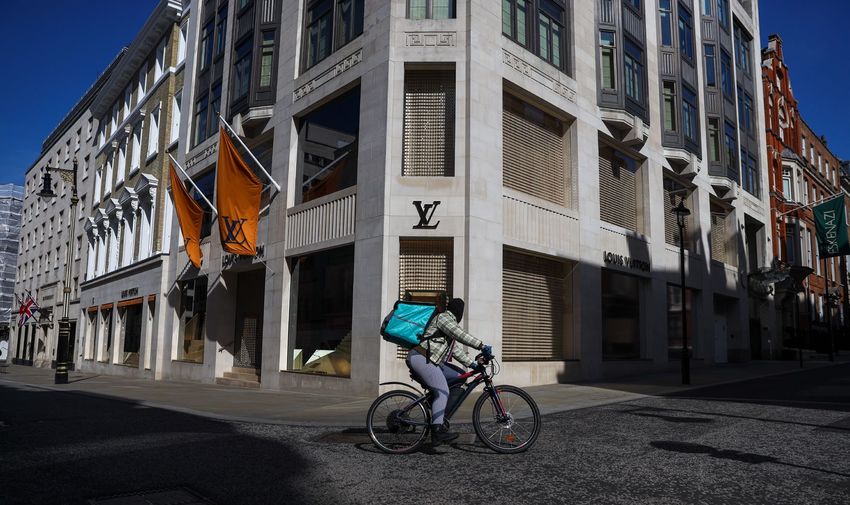
CONTRIBUTORS

                                                 IMRAN AMED                        ACHIM BERG                        ANITA BALCHANDANI                SASKIA HEDRICH

                                                 As founder, editor-in-chief and   Based in Frankfurt, Achim         Anita Balchandani is a Partner   As global senior expert in
                                                 chief executive of The Business   Berg leads McKinsey’s Global      in McKinsey’s London office,     McKinsey’s Apparel, Fashion
                                                 of Fashion, Imran Amed is         Apparel, Fashion & Luxury         and leads the Apparel, Fashion   & Luxury group, Saskia
                                                 one of the fashion industry’s     group and is active in all        & Luxury group in the United     Hedrich works with fashion
                                                 leading writers, thinkers and     relevant sectors including        Kingdom. Her expertise           companies around the
                                                 commentators. Fascinated by       clothing, textiles, footwear,     extends across fashion,          world on strategy, sourcing
The State of Fashion 2020 — Coronavirus Update

                                                 the industry’s potent blend       athletic wear, beauty,            health and beauty, specialty     optimisation, merchandis-
                                                 of creativity and business, he    accessories and retailers         retail and e-commerce. She       ing transformation, and
                                                 began BoF as a blog in 2007,      spanning from the value end       focuses on supporting clients    sustainability topics — all
                                                 which has since grown into the    to luxury. As a global fashion    in developing their strategic    topics she is also publishing
                                                 pre-eminent global fashion        industry and retail expert,       responses to the disruptions     about regularly. Additionally,
                                                 industry resource serving a       he supports clients on a broad    shaping the retail industry      she is involved in developing
                                                 five-million-strong community     range of strategic and top        and in delivering customer       strategies for national garment
                                                 from over 200 countries and       management topics, as well as     and brand-led growth             industries across Africa, Asia,
                                                 territories. Previously, he was   on operations and sourcing-       transformations.                 and Latin America.
                                                 a consultant at McKinsey          related issues.
                                                 in London.

                                                 FELIX RÖLKENS                     ROBB YOUNG                        JAKOB EKELØF JENSEN

                                                 Felix Rölkens is part of the      As global markets editor of       Jakob Ekeløf Jensen is a
                                                 leadership of McKinsey’s          The Business of Fashion,          consultant in McKinsey’s
                                                 Apparel, Fashion & Luxury         Robb Young oversees content       London office, specialising in
                                                 group and works with              from Asia-Pacific, the Middle     Apparel, Fashion & Luxury.
                                                 apparel, sportswear and pure      East, Latin America, Africa,      He has supported several
                                                 play fashion e-commerce           the CIS and Eastern Europe.       global fashion companies
                                                 companies in Europe and           He is an expert on emerging       as well as investors looking
                                                 North America, on a wide range    and frontier markets, whose       at fashion assets across
                                                 of topics including strategy,     career as a fashion editor,       Europe, on topics including
                                                 operating model and merchan-      business journalist, author and   e-commerce, strategy, value
                                                 dising transformations.           strategic consultant has seen     creation and M&A.
                                                                                   him lead industry projects
                                                                                   around the world.

                                                 4
ACKNOWLEDGEMENTS

The authors would like to thank all members of The Business of Fashion and the McKinsey community for their contribution to the
research in this report.

The wider BoF team has also played an instrumental role in creating this report — in particular Amanda Dargan, Anouk Vlahovic,
Casey Hall, Christina Yao, Hannah Crump, Jael Fowakes, Kate Vartan, Lauren Sherman, Niamh Coombes, Nick Blunden, Olivia
Howland, Queennie Yang, Sarah del Corral, Vikram Alexei Kansara and Zoe Suen.

The authors would like to thank Kilian Graulich and Tiffany Wendler from McKinsey’s Berlin and Stuttgart offices respectively for
their critical roles in delivering this report. We also acknowledge the following McKinsey colleagues across the global teams for their
support and contributions to this report: Laura Gallagher, Aimee Kim, Alex Sukharevsky, Althea Peng, Amelia Newland, Annika
Reinelt, Antonio Achille, Antonio Gonzalo, Clarisse Magnin, Colin Henry, Colleen Baum, Daniel Zipser, Danielle Bozarth, David
Barrelet, Ellie Baker, Franck Laizet, Hanna Grabenhofer, Hannah Yankelevich, John Hooks, Karl-Hendrik Magnus, Miriam Lobis,
Nadya Snezhakova, Raphael Buck, Ryan Shultz, Sajal Kohli, Sakina Mehenni, Stijn Kooij, Thomas Tochtermann, Ulric Jerome. We’d
also like to thank Adriana Clemens for external relations and communications.

In addition, the authors would like to thank Joanna Zawadzka for her creative input and direction into this State of Fashion report,
Anna Kövecses for the cover illustration and Getty Images for supplying imagery to bring the findings to life.

                                                                                                                                          5
INTRODUCTION

                                                 It’s Time to Rewire
                                                 the Fashion System.
                                                 Fashion executives and business leaders are currently
                                                 focusing on crisis management and contingency planning,
                                                 but eventually we must shift towards re-imagining our
                                                 industry altogether. How will dramatic shifts in the global
The State of Fashion 2020 — Coronavirus Update

                                                 economy and consumer behaviour in the post-coronavirus
                                                 world impact fashion and what can be done to rewire a
                                                 fashion system that is no longer working?

                                                         Even before the coronavirus disrupted           confront a disorientating future and vulnerable
                                                 financial markets, upended supply chains and            workers face hardship and destitution. With this
                                                 crushed consumer demand across the global               special Coronavirus Update to The State of Fashion
                                                 economy, fashion industry leaders were not              2020, we have taken a stance on what our “new
                                                 optimistic about 2020. The industry was already         normal” will look like in the aftermath of this black
                                                 “On High Alert” and executives expressed pessimism      swan event, analysing surveys, data and expert
                                                 across all geographies and price points in our annual   interviews to provide insight for fashion profession-
                                                 report, The State of Fashion 2020, released late last   als as they embark on the 12- to 18- month period
                                                 year. But fast forward a few months and fashion’s       after the dust settles.
                                                 outlook has gotten dramatically and suddenly
                                                 bleaker. As an industry, we are now on red alert.              The Black Swan and Fashion

                                                 The crisis is affecting our daily lives,                       Covid-19 could spur the biggest economic
                                                                                                         contraction since World War II, hitting every sector
                                                 instilling anxiety and uncertainty in                   from finance to hospitality.1 Yet fashion, due to its
                                                 the minds of almost everyone.                           discretionary nature, is particularly vulnerable.
                                                                                                         The average market capitalisation of apparel, fashion
                                                        This unforeseeable humanitarian and              and luxury players dropped almost 40 percent
                                                 financial crisis has rendered previously planned        between the start of January and March 24, 20202
                                                 strategies for 2020 redundant, leaving fashion          — a much steeper decline than that of the overall
                                                 businesses exposed or rudderless as their leaders       stock market.

                                                 6
Humanitarian repercussions are expected                 The interconnectedness of the industry is
to outlast the pandemic itself. Dire consequences         making it harder for businesses to plan ahead. Just as
for fashion, one of the biggest industries in the world   China inched through recovery, outbreaks worsened
generating $2.5 trillion in global annual revenues3       in Europe and the US. But it is in the developing world,
before the pandemic hit, entails joblessness or           where healthcare systems are often inadequate and
financial hardship for people across the value            poverty is rife, that people will be hit the hardest. For
chain — from those harvesting the fibres used to          workers in low-cost sourcing and fashion manufac-
make textiles to shop assistants selling the finished     turing hubs such as Bangladesh, India, Cambodia,
fashion product.                                          Honduras and Ethiopia, extended periods of unem-
         We estimate that revenues for the global         ployment will mean hunger and disease.
fashion industry (apparel and footwear sectors) will
contract by 27 to 30 percent in 2020 year-on-year,
                                                          Though the duration and
although the industry could regain positive growth
of 2 to 4 percent in 2021.4 For the personal luxury       ultimate severity of the pandemic
goods industry (luxury fashion, luxury accessories,       remains unknown, it is apparent that
luxury watches, fine jewellery and high-end beauty),
                                                          the fashion industry is just at the
we estimate a global revenue contraction of 35 to 39
percent in 2020 year-on-year, but positive growth         beginning of its struggle.
of 1 to 4 percent in 2021.5 If stores remain closed
for two months, McKinsey analysis approximates                     The crisis is affecting our daily lives,
that 80 percent of publicly listed fashion companies      instilling anxiety and uncertainty in the minds
in Europe and North America will be in financial          of almost everyone. Indeed, consumer pessimism
distress. Combined with the McKinsey Global               about the economy is widespread, with 75 percent of
Fashion Index (MGFI) analysis, which found that 56        shoppers in the US and Europe believing that their
percent of global fashion companies were not earning      financial situation will be impacted negatively for
their cost of capital in 2018, we expect a large number   more than two months.4
of global fashion companies to go bankrupt in the next             Though the duration and ultimate severity
12 to 18 months.                                          of the pandemic remains unknown, it is apparent
                                                          that the fashion industry is just at the beginning
                                                          of its struggle. By causing blows to both supply
It is in the developing world, where
                                                          and demand, the pandemic has brewed a perfect
healthcare systems are often                              storm for the industry: a highly integrated global
inadequate and poverty is rife, that                      supply chain means companies have been under
                                                          immense strain as they tried to manage crises on
people will be hit the hardest. For
                                                          multiple fronts as lockdowns were imposed in rapid
workers in low-cost sourcing and                          succession halting manufacturing in China first,
fashion manufacturing hubs such                           then Italy, followed by countries elsewhere around
                                                          the world.
as Bangladesh, India, Cambodia,
                                                                   A freeze on spending is aggravating the
Honduras and Ethiopia, extended                           supply-side crisis. Widespread store closures for
periods of unemployment will mean                         an industry reliant on offline channels, coupled
                                                          with consumer instinct to prioritise necessary
hunger and disease.
                                                          over discretionary goods, hit brands’ bottom lines

                                                                                                                  7
INTRODUCTION

                                                 and depleted cash reserves. Even online sales have     once the immediate crisis subsides. Even after
                                                 declined 5 to 20 percent across Europe, 30 to 40       witnessing waves of insolvencies, industry leaders
                                                 percent in the US and 15 to 25 percent in China.5      will need to get comfortable with uncertainty
                                                                                                        and ramp-up their future-proofing efforts as the
                                                        Once the Dust Settles                           potential for further outbreaks and lockdowns loom.

                                                          Once the dust settles on the immediate
                                                                                                        No company will get through
                                                 crisis, fashion will face a recessionary market and
                                                 an industry landscape still undergoing dramatic        the pandemic alone, and fashion
                                                 transformation. We expect a period of recovery to be   players need to share data,
                                                 characterised by a continued lull in spending and a
                                                                                                        strategies and insights on how to
                                                 decrease in demand across channels. As noted in our
                                                 previous reports with themes on “Getting Woke,”        navigate the storm.
                                                 “Radical Transparency” and “Sustainability First,”
                                                 the consumer mindset was already showing signs of                This will also be a time for collaboration
                                                 shifting in certain directions before the pandemic.    within the industry — even between competing
The State of Fashion 2020 — Coronavirus Update

                                                                                                        organisations. No company will get through the
                                                 The coronavirus also presents                          pandemic alone, and fashion players need to share
                                                                                                        data, strategies and insights on how to navigate the
                                                 fashion with a chance to reset and                     storm. Brands, suppliers, contractors and landlords
                                                 completely reshape the industry’s                      should also find ways to share the burden.
                                                 value chain — not to mention an                                  This joint report by The Business of Fashion
                                                                                                        and McKinsey & Company is an effort to advance
                                                 opportunity to reassess the values                     the discussion beyond crisis management and
                                                 by which we measure our actions.                       immediate contingency planning, by outlining the
                                                                                                        areas where the industry must focus once the dust
                                                          Now, the resulting “quarantine of consump-    settles on the current crisis. Exactly when this will
                                                 tion”6 could accelerate some of these consumer         happen is impossible to know for sure, except that
                                                 shifts, such as a growing antipathy toward             it will, in all likelihood, be linked to the discovery
                                                 waste-producing business models and heightened         of a workable antiviral treatment and delivery of a
                                                 expectations for purpose-driven, sustainable action.   proven vaccine, which some experts say is at least 12
                                                 Meanwhile some of the shifts we will witness in        to 18 months away.
                                                 the fashion system such as the digital step change,              Navigating this uncertainty will not be easy
                                                 in-season retail, seasonless design and the decline    for fashion leaders. Players need to be decisive and
                                                 of wholesale are mostly an acceleration of the         start putting recovery strategies into motion to
                                                 inevitable — things that would have happened           emerge with renewed energy. The crisis is a catalyst
                                                 further down the road if the pandemic had not          that will shock the industry into change — now is the
                                                 helped them gain speed and urgency now.                time to get ready for a post-coronavirus world.
                                                          The coronavirus also presents fashion
                                                 with a chance to reset and completely reshape
                                                 the industry’s value chain — not to mention an
                                                 opportunity to reassess the values by which we
                                                 measure our actions. We expect that themes of
                                                 digital acceleration, discounting, industry consoli-
                                                 dation and corporate innovation will be prioritised

                                                 8
FIVE THEMES FROM THE CORONAVIRUS UPDATE

                                                                                          30
                    01.

                                                                                             %
 GLOBAL ECONOMY

                    Survival Instincts                                                             Percentage of
                                                                                                   fashion industry
                                                                                                   employees who
                    Recovery from the pandemic will coincide with a recessionary                   perceive their
                    market, compelling fashion players to ramp up resilience planning              company’s
                    and adapt their operating models. Companies surviving the                      planning for
                                                                                                   recovery post-
                    immediate crisis will have made bold and rapid interventions to                crisis response as
                    stabilise their core business before seeking out new markets,                  ineffective
                    strategic opportunities and future pockets of growth in a global
                    fashion industry undergoing dramatic transformation.

                    02.

                    Discount Mindset                                                               Percentage of
                                                                                                   consumers who

                                                                                          56
                                                                                                   said special
                    As deep discounting plagues retailers for the remainder of 2020,               promotions were
                    a decade-long build-up of bargain shopping culture will be                     an important factor
                    exacerbated by a rise in anti-consumerism, a glut in inventory and             when shopping
                                                                                                   for clothes in the 4
                    cash-strapped consumers looking to trade down or turn to off-price             weeks leading up to
  CONSUMER SHIFTS

                    channels. To reach increasingly frugal and disillusioned consumers,            29 March 2020
                    brands must find inventive ways to regain value and rethink their
                    broader business mission.

                    03.

                    Digital Escalation                                                             Year-on-year
                                                                                                   increase in

                                                                                          >700%
                                                                                                   livestreaming
                    Social distancing has highlighted the importance of digital                    on Chinese
                    channels more than ever and lockdowns have elevated digital                    e-commerce
                                                                                                   website Taobao
                    as an urgent priority across the entire value chain but, unless
                                                                                                   since the outbreak
                    companies scale up and strengthen their digital capabilities in                of Covid-19
                    the recovery phase of the crisis, they will suffer in the longer
                    term. Consumers will continue to demand more in this space
                    and brands must act fast to deliver.

                                                                                          80   %
                    04.

                    Darwinian Shakeout                                                             Percentage of
                                                                                                   fashion companies
                                                                                                   who would be in
                    The crisis will shake out the weak, embolden the strong and                    distress after more
                    accelerate the decline of companies that were already struggling               than 2 months of
                                                                                                   store closures
                    before the pandemic, leading to massive waves of consolidation,
                    M&A activity and insolvencies. To secure their future, companies
                    must adapt to the new market environment by evaluating
  FASHION SYSTEM

                    divestment and acquisition opportunities to strengthen their core
                    and capture whitespaces that emerge from the reshuffle.

                    05.

                    Innovation Imperative                                                          Percentage of
                                                                                                   fashion industry
                                                                                                   employees that
                    To cope with new restrictions, mitigate the damaging impact of the             perceive their
                    pandemic and adapt to economic and consumer shifts, companies                  company’s
                    must introduce new tools and strategies across the value chain to              planning for post-
                                                                                                   crisis recovery as
                    future-proof their business models. Fashion players must harness               ineffective.
                    these innovations and scale up those that work in order to make
                    radical and enduring changes to their organisations — and to the
                    wider industry — after the dust settles.
                                                                                                           9
The State of Fashion 2020 — Coronavirus Update

10
                        01. SURVIVAL INSTINCTS
                                                 GLOBAL
                                                 ECONOMY
01. SURVIVAL INSTINCTS
Recovery from the pandemic will coincide with a
recessionary market, compelling fashion players to ramp
up resilience planning and adapt their operating models.
Companies surviving the immediate crisis will have made
bold and rapid interventions to stabilise their core business
before seeking out new markets, strategic opportunities
and future pockets of growth in a global fashion industry
undergoing dramatic transformation.
If macroeconomic headwinds weren’t already 30 percent of industry revenue is generated from
nudging businesses to reassess their position on a luxury purchases made outside consumers’ home
whole host of priorities, the coronavirus pandemic is countries),10 in addition to lower levels of online
now forcing companies across many sectors to make presence and high dependency on department
urgent, existential decisions. The global fashion stores and experiential in-store retail. For example,
industry is no different, with almost all companies in March LVMH announced a 20 percent drop
battling lacklustre consumer confidence, foregone in quarterly revenue as a result of the Covid-19
revenues and stores on lockdown. outbreak.11 While the extent of the damage remains
Fashion companies — particularly those unclear, 2020 is already shaping up to be “the worst
relying on longer lead times and inflexible supply year in the history of modern luxury,”12 said Luca
chains — are uniquely vulnerable due to the Solca, investment research analyst at Bernstein.
category’s discretionary nature. Indeed, fashion
may face a harder time than discretionary goods A two- to three-month lockdown
overall: more than 70 percent of European and US will cause financial distress for
consumers expect to cut back spending on apparel7
80 percent of European and North
compared to a 40 to 50 percent drop in global discre-
tionary spending.8 American fashion businesses,
A two- to three-month lockdown will cause as volatility reduces investor
financial distress for 80 percent of European and
confidence in a stock market facing
North American fashion businesses, as volatility
reduces investor confidence in a stock market facing its hardest hit since the global
its hardest hit since the global financial crisis of financial crisis of 2008.
2008.9
As the dust settles, the luxury sector may Consumption shifts already evident in
suffer more than other segments. This is due to countries from China to the US will be echoed across
the luxury sector’s reliance on travel retail (20 to most major global markets. In the US, 56 percent
11GLOBAL ECONOMY
of consumers surveyed in McKinsey & Company’s of different plays of pandemic containment and
Covid-19 Consumer Pulse Survey said they are the ensuing economic response. The McKinsey
cutting back on spending, while 48 percent agreed Global Institute (MGI) describes four different
that economic uncertainty is preventing them from scenarios for the crisis to develop (see Exhibit 1).
committing to purchases they would otherwise have In each scenario, the spread of Covid-19 is eventually
made.13 With the US reporting a record 6.6 million controlled and catastrophic structural economic
unemployment claims filed in one week between damage is avoided. Scenarios form a V-shape if
March 22 and 28,14 and Chinese unemployment economic rebound is strong, and a U-shape if
figures at a record 5.7 percent in February, discre- economic recovery is slower. The recovery curves
tionary spending will take a backseat. are distinguished further by the speed and effec-
In the event that a vaccine is developed, some tiveness of the virus containment.17 However, any
shoppers in certain markets might respond with scenario will likely disproportionately affect the
a momentary “euphoric” spike in consumption, fashion industry given its discretionary nature,
suggested Solca. This is similar to murmurings in and the industry’s recovery will lag behind the rest
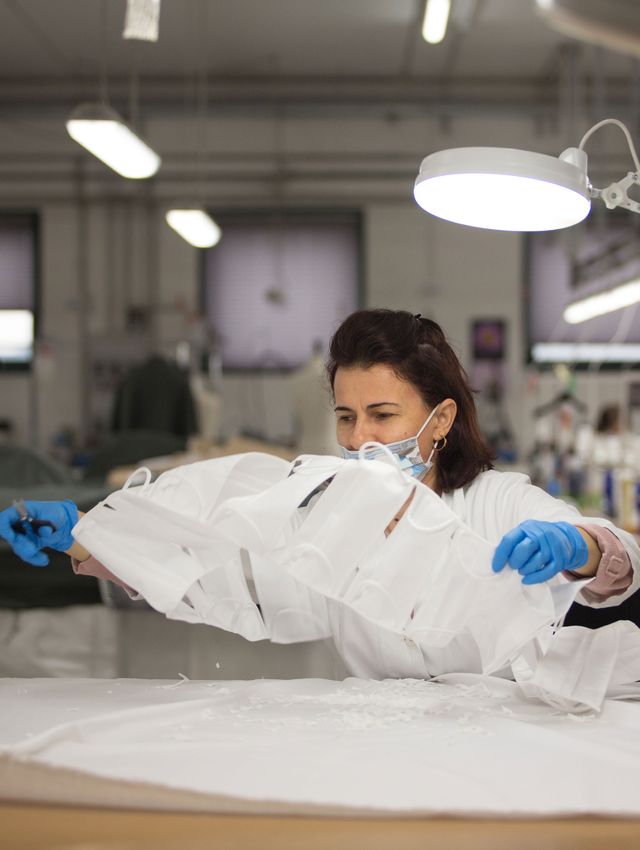
Tailoring department of Cieffe Company, a high fashion company that is reinventing itself to produce hospital products. Massimo Cavallari/Getty Images
The State of Fashion 2020 — Coronavirus Update
China of a potential return of so-called “revenge of the economy.
buying,” in which consumers may salve the wound
of a months-long lockdown with feel-good spending. Any scenario will likely
But “[if] we don’t manage to vanquish the threat
disproportionately affect the
of Covid-19...the shape of recovery will be more
subdued,” he said.15 fashion industry given its
Amid the health crisis, some digitally adept discretionary nature, and the
offerings and business models created pockets of
industry’s recovery will lag behind
positive momentum by cutting out middlemen
and optimising e-commerce capabilities to reach the rest of the economy.
self-isolating shoppers. At the same time, a “wellness
dividend” has provided a boost for some hygiene- As we have seen in China, the re-opening
and health-orientated products and brands that of physical retail does not mean business returns
have capitalised on the shift in consumer attention back to “normal.” When 90 percent of apparel
to safety, health and wellness. However, an indis- stores re-opened in China, footfall and purchases
criminatory downturn in consumer appetite for were still 50 to 60 percent below pre-crisis levels.18
discretionary purchases awaits even the savviest Furthermore, each country will see varying
players, meaning any momentary uptick in sales recovery phases depending on their healthcare
will not be able to offset a decline in spending across systems, financial resources and immediacy of
the board. response to the outbreak. For fashion, a rapid return
While the duration of the pandemic remains of consumer confidence is especially important to
uncertain, recovery will most likely be gradual. restore the value chain.
Consumer sentiment took up to two years to return We expect markets where the “dust has
to normal after previous global crises: recovery begun to settle,” such as China and South Korea, to
from the 2003 SARS pandemic, 9/11 and the 2008 experience a quick recovery unless there are second
financial crisis took 6 months, 1.5 years and 2 years waves of outbreaks. Although fears of a second wave
respectively.16 in China are constant, with worrying signs of new
There are multiple possible scenarios for how small-scale outbreaks around the country at the
the fallout will unfold, hinging on the effectiveness time of writing.19 Developing countries in Asia, such
1213
GLOBAL ECONOMY

                                                 as India and Indonesia, have been severely hit by the   growth opportunities will depend largely on the way
                                                 lockdown of production facilities, leaving millions     each country manages the pandemic. With a human-
                                                 without jobs and weakening their position in the        itarian crisis unfolding in emerging markets like
                                                 global value chain. Similarly, we expect markets        India, fashion players will now need to re-evaluate
                                                 that have been under economic distress before the       strategies for which stores to re-open and when,
                                                 crisis — such as Venezuela and Nigeria — to require     and how their supply chain can best support the
                                                 more time to restore growth, owing to their inherent    ramp-up.
                                                 political instability.
                                                         In the west, there will be different rates of   Companies must adopt a recovery
                                                 return of consumer confidence based on the speed        position based on impact severity
                                                 and effectiveness of government support and how
                                                 severely hit the country has been by the pandemic,      to help prepare for the deployment
                                                 with countries like Italy, Spain and France             of a recovery action plan.
                                                 potentially faring worse than Germany.
The State of Fashion 2020 — Coronavirus Update

                                                         Looking ahead, businesses will have to                  In the event that collateral economic damage
                                                 review their operating models. While implementing       from the pandemic continues for an extended
                                                 short-term interventions — like cutting costs and       period of time, brands should review cost bases to
                                                 production, securing liquidity and adjusting product    identify measures for quick wins, set up employee
                                                 assortments, which have been the highest priority       plans to assess workforce decisions, and rationalise
                                                 in urgent reactions to the crisis — companies now       overhead spend to plan for potential store closures.
                                                 need to consider actions for the recovery period and    On the supply chain side, fashion companies should
                                                 implement resiliency into their planning.               learn from this global trade disruption that the
                                                                                                         value chain must be re-invented. This includes
                                                 In the west, there will be different                    reviewing production regularly to identify potential
                                                                                                         disruptions before they happen in order to cushion
                                                 rates of return of consumer                             the blow when they come to pass and strengthening
                                                 confidence based on the speed                           regional integrated supply chains. It also means
                                                 and effectiveness of government                         exploring nearshoring activities to bring flexibility
                                                                                                         and autonomy to their production facilities. Broadly
                                                 support and how severely hit the                        speaking, non-core assets and activities should be
                                                 country has been by the pandemic.                       divested and stopped to streamline current offerings
                                                                                                         and ensure efficient execution.
                                                         Companies must adopt a recovery position                Speed and adaptability are of the essence
                                                 based on impact severity to help prepare for the        for this crisis. But when the first signs of normalcy
                                                 deployment of a recovery action plan. This means        do begin to emerge, companies are cautioned not to
                                                 reassessing their geographical footprint, store         be complacent. Instead, they must double-down on
                                                 network and growth opportunities, while also            recovery and resiliency measures for this will be a
                                                 looking for any emerging whitespace, be it during       time of unprecedented transformation for the global
                                                 recovery or an extended crisis period. In The State     fashion industry. Only then can companies begin to
                                                 of Fashion 2020 report, the biggest growth was          decipher what their “new normal” actually looks like.
                                                 predicted for emerging Asia, with rising opportu-
                                                 nities in India and Southeast Asian nations like
                                                 Indonesia.20 However, the preservation of these

                                                 14
01. SURVIVAL INSTINCTS
Exhibit 1:
GDP impact is heavily dependent on different plays around
pandemic containment and economic response policy
GDP IMPACT OF COVID-19 SPREAD BASED ON PUBLIC HEALTH RESPONSE AND ECONOMIC POLICIES
U-SHAPED V-SHAPED
A C
Rapid and effective
control of virus spread,
with controlled spread
EFFECTIVENESS OF THE PUBLIC HEALTH
within 2-3 months
Virus contained and slow recovery Virus contained and strong growth rebound
PANDEMIC CONTAINMENT
B D
Effective response,
but (regional) virus
resurgence
Virus resurgence and slow long-term growth Virus resurgence and return to trend growth
Partially effective interventions, Effective interventions, with strong
with banking crisis avoided and responses preventing structural
recovery levels muted damage and recovery to pre-crisis
EFFECTIVENESS OF ECONOMIC POLICY RESPONSE
SOURCE: “SAFEGUARDING OUR LIVES AND OUR LIVELIHOODS: THE IMPERATIVE OF OUR TIME”, MCKINSEY & COMPANY, MARCH 2020
15CONSUMER
SHIFTS
The State of Fashion 2020 — Coronavirus Update
02. DISCOUNT MINDSET
03. DIGITAL ESCALATION
1602. DISCOUNT MINDSET
As deep discounting plagues retailers for the
remainder of 2020, a decade-long build-up of bargain
shopping culture will be exacerbated by a rise in anti-
consumerism, a glut in inventory and cash-strapped
consumers looking to trade down or turn to off-price
channels. To reach increasingly frugal and disillusioned
consumers, brands must find inventive ways to regain
value and rethink their broader business mission.
Consumer sentiment is at an all-time low. As a result, overfilled warehouses laden with
This has hit the fashion industry especially hard due unsold seasonal stock will haunt most players, as
to the discretionary nature of clothing purchases. long lead times weigh heavily on fashion’s supply
In Europe and the US, more than 65 percent of chain and global consumer appetite for discretion-
consumers expect to decrease their spending on ary purchases wavers. Companies will turn to steep
apparel, while only 40 percent expect to decrease discounting to clear inventory for the rest of the
total household spending (see Exhibit 2).21 What’s year at a minimum, with a risk that “the contagion
more, 56 percent of consumers state that their main of deep discounting could spread as quickly as the
reason for purchasing clothing during the crisis was disease”24 throughout the industry, reminiscent of
special promotions.22 the discounting culture that took hold during the
2008 financial crisis and has dogged the industry
In Europe and the US, more than ever since.
65 percent of consumers expect to Some retailers in the US estimate that a
majority of spring inventory will be leftover due to
decrease their spending on apparel, store closures and a dip in online traffic, conversions
while only 40 percent expect to and consumer sentiment. Following the imposition
decrease total household spending. of lockdowns across most of Europe and the US,
some brands and retailers have stopped fulfilling
Some experts predict that consumer e-commerce orders entirely, while many of those
sentiment may never recover to pre-2020 levels who remain up and running have resorted to flash
as anti-consumerism and economic fallout cast a and mid-season sales to increase demand. In Italy,
shadow over global markets, and shoppers are hit the number of items on discount is up 20 percent
hard by a global recession. As of March 2020, 60 year-on-year.25
percent of consumers in the US already reported Seasonless stock like intimates is less
that they need to be careful how they spend their exposed and can be repurposed later in the year,
money, with more than one-third stating that the but most mass-market players will be left with
pandemic is even impacting their ability to make little alternative to slashing prices, with other
financial ends meet.23 inventory-reduction plays, such as controversial
17CONSUMER SHIFTS
stock incineration, no longer feasible in times of work with wholesalers and e-tailers — which might
heightened transparency and sustainability-con- even include inventory swaps to prevent them from
scious consumers. discounting their products.29 (Multi-brand retailer
Even after the dust settles, financial turmoil Net-a-Porter had 30 percent of its assortment on
stemming from the crisis will continue. McKinsey markdown as of March 2020, compared to only 1
and Oxford Economics analysis shows that, even in percent in 2019).30 As boutiques struggle with store
the most positive economic recovery scenario, GDP closures and overstock problems, and as grey market
will only return to pre-crisis levels by the end of counterparts in countries such as China cancel
2020, or even the beginning of 2021.26 As consumer orders, marketplace model e-tailers like Farfetch
spending in most advanced economies accounts for will be well-positioned to facilitate the liquidation
roughly two-thirds of the economy, and about half of large volumes of cheap stock. This will create
of that is discretionary spend, fashion companies tensions with brand-owners, however, as they will
will be left grappling with price deflation and a sharp want to take a more discreet approach.
drop in demand across the board. Evidence from
The State of Fashion 2020 — Coronavirus Update
previous crisis shows that it may take up to two years The pandemic will bring values
to fully restore consumer confidence,27 with early
numbers from China showing that apparel sales
around sustainability into sharp
were still down by 50 to 60 percent in the first month focus, intensifying discussions and
after stores re-opened.28 further polarising views around
We expect different market categories to
be impacted by the discounting wave to varying
materialism, over-consumption and
degrees. Mid-market brands and retailers will be irresponsible business practices.
hit hardest, as cash-strapped shoppers trade down
to the value segment for essentials and middle- Moving forward, the “off-price deception”
class consumers turn more to heavily discounted trend witnessed in The State of Fashion 2018
affordable luxury and premium goods. report — which highlighted the danger of off-price
cannibalising full-priced sales — will soon reach a
In the luxury segment, we expect new phase, as growth in the discount sector puts
consumers to return more quickly to companies at risk of margin erosion. Premium
discount retailers with effective merchandising
paying full price for quality, timeless and strong customer service, like The Outnet and
goods, as was the case after the Yoox online and McArthurGlen offline, will become
2008 financial crisis. mainstream by offering discreet and large-scale
avenues for excess stock disposal. As in 2008,
In the luxury segment, we expect consumers new digital players will also emerge to seize the
to return more quickly to paying full price for opportunity to dispose of excess stock. But caution
quality, timeless goods, as was the case after the is advised: for companies engaging with a growing
2008-2009 financial crisis. For luxury brands, cohort of anti-consumerist shoppers, significant
however, the discounting challenge is exacerbated by discounting and traffic driving could be construed as
the need to preserve reputation and image, making tone deaf.
it crucial to avoid steep discounting, or at least The pandemic will bring values around
discount in a more controlled way through off-price sustainability into sharp focus, intensifying
channels. Brands will need to find innovative ways to discussions and further polarising views around
1802. DISCOUNT MINDSET
materialism, over-consumption and irresponsible To improve their long-term outlook, brands
business practices. Retailers have already come will need to tailor future discounting strategies
under fire for keeping stores open and putting retail by aligning promotions to their various channels
workers in danger during outbreaks in the US, and putting in place a revised product calendar to
where many lack healthcare benefits.31 Meanwhile, reflect fashion’s “new normal.” They will also need to
some players who stopped paying rent to stay liquid reinfuse value to make it worthwhile for consumers
have faced public backlash and have consequently to shop at full price. The solution is not just about
reversed their actions to regain customer trust, reducing overstock but gaining back the trust and
while public outcry about unpaid order cancellations enthusiasm of cash-strapped consumers — and that
of finished garments in production has forced some cannot be achieved by discounting alone.
global players to revise their actions. The focus on
sustainability will be especially prominent for
Exhibit 2:
Gen-Z and Millennial shoppers, whose concerns for
the environment were already heightened pre-crisis. A significant drop in
As we stated in The State of Fashion 2019 report
trend “Getting Woke,” consumers will make or break consumer spend on apparel
brands based on trust — a trend that is now further will result in massive
intensified.
“The virus, I think, can be seen as a inventory build-ups
representation of our conscience... it brings to light
what is so terribly wrong with society and every day CONSUMERS’ EXPECTED CHANGE IN SPEND ON
APPAREL ‘IN NEXT 2 WEEKS’
that becomes more clear,” said Trend Forecaster Li
PERCENT OF RESPONDENTS
Edelkoort. “It teaches us to slow down and to change
our ways.”32 Decrease Same Increase
This may signal the end of “extreme
consumerism” for some consumers who reject the 4 4
idea of buying goods in large volumes. According to
a McKinsey survey, 15 percent of consumers in the 28
30
US and Europe expect to buy more ecologically and
socially sustainable clothing.33 Brands that are able
to reorient their missions and business models in
more sustainable ways will be able to cater to a more
captive audience than ever before.
Fashion players may also turn to more
innovative ways to reduce stock and reinfuse value 68
66
into their products, such as accelerating nascent
sustainability trends. For many players, repurposing
existing stock for new seasons will be a more viable
option than recycling or upcycling with fabric
additions or extractions. Other opportunities
EUROPE USA
include personalisation, customer experience and
a re-evaluation of the company’s fashion calendar, SOURCE: MCKINSEY & COMPANY COVID-19 CONSUMER PULSE, 20 - 29
such as moving monthly drops into later seasons. MARCH 2020
1903. DIGITAL ESCALATION
Social distancing has highlighted the importance
of digital channels more than ever and lockdowns
have elevated digital as an urgent priority across the
entire value chain but, unless companies scale up and
strengthen their digital capabilities in the recovery
phase of the crisis, they will suffer in the longer term.
Consumers will continue to demand more in this space
and brands must act fast to deliver.
The State of Fashion 2020 — Coronavirus Update
If ever there was a time to turbocharge third quarter ended February 2934 — leveraged
digital, it is now. The global pandemic’s shutdown Taobao livestream bloggers during lockdown in
of offline retail channels has pushed digitally China, while local fashion group Peacebird grew
inept fashion companies to the brink. With no or retail sales as a result of innovative customer
limited avenues to recover lost sales, purely offline engagement on their WeChat channel, which
players whose revenues hinge on brick-and-mortar featured over 100 live broadcasting sessions with
sales have been hit hardest. Many multi-channel influencers and drew over one million consumers.35
businesses have had their first glimpse of what it
takes to be truly digital-first, and this step change in Consumers increasingly
consumer adoption is likely to stick when we emerge embraced digital solutions for
from the crisis.
Almost overnight, the global fashion
shopping, entertainment and
industry’s reliance on digital channels has communications thanks to the
accelerated faster than anyone could have response of brands and retailers
anticipated prior to the crisis. This could spell
trouble for department stores and speciality retail,
who quickly enhanced their
in addition to smaller players incapable of adapting digital capabilities by launching or
to a digital-first mentality. improving innovative new channels.
But there is a silver lining emerging in Asia.
Evidence from China suggests that consumers there Social media platforms in the region
increasingly embraced digital solutions for shopping, have also seen pockets of momentum and have
entertainment and communications thanks to delivered much-needed solutions for some brands
the response of brands and retailers who quickly and retailers. WeChat saw a 159 percent boost in
enhanced their digital capabilities by launching or transaction volume for fashion brand mini-pro-
improving innovative new channels. Nike — whose grammes (brand-powered app-in-apps embedded
digital sales in the region grew 36 percent in the within its interface) between January and February
2003. DIGITAL ESCALATION
2020 during the peak of China’s outbreak.36 modes of engagement. People will acclimate to the
WeChat offers features that allow store assistants wider digitisation of consumer journeys as digital
to message consumers and complete purchases, content creation becomes their primary mode of
generating a much-needed revenue source for brands brand interaction. According to a McKinsey survey,
operating in the quagmire of a crisis. Through almost a quarter of US and European consumers
WeChat Groups and WeChat Work, companies are expect to increase their spend via social channels in
able to engage clients and integrate their profiles April 2020.39 As the crisis also pushes 13 percent of
into their brand’s account. European consumers to browse online e-tailers for
Other digital solutions used by retail the first time,40 brands should take the opportunity
assistants during the lockdown in China included to become not just more digitally adept, but to
livestreaming sessions on WeChat or platforms become digital frontrunners.
such as Yizhibo, which effectively turned empty
luxury brand stores into virtual shopping stages As the crisis also pushes 13
hosted by the staff. As seen on apps like Xiaohongshu percent of European consumers
and Taobao, brand-to-shopper video chats and
broadcasted influencer-curated assortments were to browse online e-tailers for the
well-received, with the number of Chinese brands first time, brands should take
livestreaming on Taobao up by 700 percent.37 the opportunity to become not
In March 2020, executives like Giovanni
Pungetti, Greater China and APAC chief executive just more digitally adept, but to
of OTB Group, which controls brands Marni, Diesel become digital frontrunners.
and Maison Margiela, embraced experiments
with livestream commerce.38 “It’s a completely “Working from home or staying at home
different way of doing business for us [but] we have may well drive more non-work screen time, which
been able to reach every corner of China [and] we would give marketers additional shots on goal,” said
have been able to make some business,” he said. “I Simeon Siegel, managing director and senior analyst
always underline this to our shareholders in Italy: at BMO Capital. However, marketing opportuni-
everything we are learning in this moment…will be ties may not translate into much-needed revenue.
an added weapon we can use to increase and grow “Whether they convert is another story,” he said.41
[more broadly elsewhere] when things get back to Indeed, the broader outlook for online is
normal,” he added. challenging. Despite the aforementioned uptick in
social commerce, 44 percent of US and European
“It’s a completely different way of consumers expect to decrease online purchases
overall, which is not far behind the 49 percent
doing business for us but we have who expect to decrease offline purchases as of
been able to reach every corner of April 2020.42
China and we have been able to Though much about the pandemic’s duration
and trajectory remains uncertain, businesses can
make some business.” expect that recovery will be a gradual process
as society adjusts to the new normal, consumers
For strong players looking to accelerate continue to avoid large crowds and social distancing
demand online, staying ahead of fashion’s digital rules remain in force. Even after stores begin to
step change will mean adopting these next-level re-open, fashion’s digital step change demands
21CONSUMER SHIFTS
that companies change their mindset and begin to model that prioritises digital growth in an integrated
operate like pure digital players: rather than asking way with cutting-edge customer experience. It is
what benefits online can offer offline channels, important to remember that digital channels are not
players should ask how their brick-and-mortar a “silver bullet” to compensate for the shortfall in
presence can support e-commerce sales. Digital revenue from stores — in making this switch, some
plans should be prioritised when it comes to talent, businesses may become smaller, at least for a while,
time, allocated inventory and future investments, which will open up the need to revisit their operating
and marketing spend should be shifted to digital model as they adjust to the new reality.
channels, with ROI precisely tracked.
The strongest players will quickly scale up
Exhibit 3:
and strengthen their digital capabilities, which will
allow them to capitalise on future opportunities and Consumers expect to spend
protect their businesses from risks. Investing more more via online and social
in existing digital capabilities — such as improving
channels than through offline
The State of Fashion 2020 — Coronavirus Update
the customer journey and the broader customer
experience — should happen alongside pioneering channels in light of the
new ways of engaging with consumers online. Covid-19 outbreak
Livestreaming services, omnichannel inventory
capabilities and social commerce platforms are just ANTICIPATION OF SHOPPING HABITS ACROSS
the tip of the iceberg. DIFFERENT CHANNELS IN APRIL 2020, WESTERN
Digital strategies should also closely inform EUROPE AND THE US
partnerships and brand positioning at every stage. PERCENT OF RESPONDENTS
Brands should consider platforms as a way of
Decrease Same Increase
preserving their reach and fulfilment capability,
while identifying a suitable digital model that will
lay the groundwork to build traffic in cost-efficient 14 18
24
ways. The window of opportunity to invest and leap
forward will not last forever.
37
Since digital channels can be 38
29
less profitable than physical retail,
players need to establish a balanced
model that prioritises digital growth
in an integrated way with cutting- 49 44 47
edge customer experience.
For consumers, the rapid and recent pivot to
Ridvan Celik., Getty Images
digital will continue long after the immediate crisis, OFFLINE ONLINE SOCIAL
but for most fashion players, it will come at a cost.
Since digital channels can be less profitable than SOURCE: MCKINSEY & COMPANY COVID-19 APPAREL & FASHION SURVEY,
27 - 29 MARCH 2020
physical retail, players need to establish a balanced
2223
IN-DEPTH

                                                 For Luxury, an Acceleration of
                                                 the Inevitable
                                                 Will the coronavirus pandemic change the way consumers shop forever? When it comes to the
                                                 market for personal luxury goods, expect behaviour to shift far more quickly than anticipated.

                                                 by Lauren Sherman

                                                                                                                                                                   Chanel luxury clothing store closed in Turin, Italy during the nationwide lockdown to control the coronavirus pandemic.
The State of Fashion 2020 — Coronavirus Update

                                                                                                                                                                   Stefano Guidi/Getty Images

                                                          It’s true that the House of Chanel survived     when LVMH’s marquee brands began swelling in
                                                 multiple world wars, the stock market crash of 1988,     size, and competitors like Kering and Richemont
                                                 the Great Recession, and many other world-chang-         began building their own formidable stables.
                                                 ing, life-altering events. So did Gucci, Louis Vuitton            In many ways, the coronavirus pandemic
                                                 and Prada. But the modern luxury industry as we          is the first global crisis that will deeply impact the
                                                 know it — where brands are multi-billion dollar          sector since the industry morphed into a virtual
                                                 powerhouses, employing hundreds of thousands             oligopoly. How will it fare? The short answer: expect
                                                 of people across the globe, up and down the supply       the expected, and at lightning speed.
                                                 chain — has only really existed for the past 30 years,            During the Great Recession from 2008 to

                                                 24
CONSUMER SHIFTS
2009, the worst economic downturn in US history 2021, positive growth could return at 1 to 4 percent
since the Great Depression of the 1930s, the compared to the 2019 baseline.44 For companies that
luxury market was disproportionately impacted, do make it through to see a return to growth, what
contracting 8 percent globally compared to the will the new normal look like?
overall apparel market’s 5 percent shrinkage.
Because personal luxury goods are discretionary While it’s never been more
purchases, consumers tend to abandon them first,
especially from brands that have not developed
important to win over China’s
an emotional reason for existing in the eyes of growing middle class of brand-
the consumer. conscious shoppers, the focus will
However, after that downturn, the luxury
industry bounced back more strongly than perhaps increasingly be on meeting them
anyone could have anticipated. At the end of 2019, locally, not abroad.
LVMH, which owns brands including Louis Vuitton,
Christian Dior and Celine, became the second Post-downturn, the luxury industry had two
most-valued company in Europe, following oil and levers of growth that cannot be exactly replicated
gas giant Royal Dutch Shell, with a market capi- this time around. For one, luxury brands started
talisation passing the €200 billion mark ($217.9 charging a lot more for the products they sold at full
billion).43 That same year, the group, which now price. In 2000, the starting price for an Hermès Kelly
includes more than 70 brands across categories such bag was $4,800. By 2013, it was $7,600, reflecting a
as wine and spirits, jewellery and watches, travel 58 percent increase in 13 years, 1.5 times the rate of
and fashion, generated €53.7 billion ($58.5 billion) inflation during that period.
in revenue, up 15 percent year-over-year. Its closest While raising prices helped boost margins,
rival, Kering, generated €15.9 billion ($17.3 billion), the Chinese market, which, for most brands, only
up 16 percent from a year earlier. emerged as a significant source of revenue in the
mid-2000s, became the engine of growth. Chinese
In many ways, the coronavirus consumers were responsible for more than half of
global luxury growth between 2012 and 2018, and
pandemic is the first global crisis total spend by Chinese consumers is expected to
that will deeply impact the sector make up 40 percent by 2025, according to a 2019
report by McKinsey.45
since the industry morphed into
But while both of those levers can still be
a virtual oligopoly. pulled, the circumstances driving them are now
different. “Over the past three or four years, the
More than a decade after the Great Recession consumer’s behaviour was changing regardless,”
ravaged the global economy, the luxury industry is said John Idol, chief executive of Capri, the
now facing an even greater threat: a pandemic that American group that controls Michael Kors, Versace
has halted nearly all trade in a large part of the world. and Jimmy Choo.
The next six months may be far more The coronavirus pandemic will only
damaging to luxury than the previous downturn, accelerate that change.
with several struggling players — mostly debt-ridden For instance, while it’s never been more
multi-brand retailers and cash-poor independent important to win over China’s growing middle class
brands — not making it out the other end. McKinsey of brand-conscious shoppers, the focus will increas-
estimates that the global industry for personal ingly be on meeting them locally, not abroad. There
luxury goods will contract by 35 to 39 percent in was already a movement toward this, as price
2020 compared to the previous year. However, by
25CONSUMER SHIFTS
harmonisation at brands like Chanel made travel Right now, even retailers specialising in
retail less attractive. discounted luxury goods are struggling. In the US,
In 2019, Chinese consumers took more than American off-price chain Ross, which is similar to
150 million trips abroad, with McKinsey estimating TJ Maxx, told vendors it was cancelling orders for
that purchases outside the mainland accounted for up to three months. But come autumn, the discount
more than half of China’s luxury spend that year.46 channel will inevitably get busy, as excess inventory
Now, with travel retail suspended due to interna- from the first nine months of the year will flood the
tional lockdowns, Chinese consumers have no other market. Whether or not the demand will be there
choice but to shop at home. remains to be seen.
“Travelling shoppers will take significantly
longer to return,” said Pierre Mallevays, founder Many consumers will be looking
and managing partner of Savigny Partners LLP, a
mergers and acquisitions advisory firm focusing on
for so-called “investment” pieces —
luxury brands and retail. “This means travel retail minimalist, last-forever items, that
and tourist-dependent stores will continue to suffer feel more responsible given the
into 2021.”
Brands have never been more incentivised to state of the world.
The State of Fashion 2020 — Coronavirus Update
nurture the local market while retail in other major
regions is shut down completely, but that shift will That inventory glut will force brands to be
continue once retail operations return to normal more conservative about their autumn and spring
globally. “The Chinese will become even more production runs, if they are even able to produce the
important,” said Luca Solca, an investment research autumn season at all. What this will likely spur is a
analyst at Bernstein. “The Chinese economy should move further upstream for more companies, so that
be the least damaged from the crisis.” However, not they can participate in “reactive” manufacturing,
all signs are necessarily pointing in that direction. as one luxury executive called it. Companies like
The World Bank’s latest forecast adjusted for Hermès, Chanel, Gucci and Louis Vuitton own their
Covid-19 impact reveals that China’s economic own factories in Italy, France and beyond, which
growth is projected to decline from 6.1 percent in means they can more easily stop and start production.
2019 to 2.3 percent in 2020 (in the baseline) and 0.1 Luxury consumers are also likely to, at least
percent (in the lower-case scenario).47 for the time being, adopt the “fewer, better things”
Self-isolation has also forced another change mantra that environmentalists have been advocating
in behaviour that is likely to remain once the dust over the past decade. While this could spur increased
settles: more shopping online. “Digital will enjoy a activity in the second-hand and rental channels
step-up,” Solca said. While e-commerce channels once fear around the virus contagion subsides, it
are likely to see a boost — as more consumers get also means that many consumers will be looking
comfortable with making high-price purchases for so-called “investment” pieces — minimalist,
online as they remain hesitant to visit crowded last-forever items — that feel more responsible
public spaces — other channels, like multi-brand given the state of the world. “Call it cautious
retail, are primed for contraction even after consumption,” said Mario Ortelli, managing partner
lockdowns are lifted. Some luxury stores will not of luxury advisors Ortelli & Co. “It will take more to
survive the lockdown, as constrained cash flow will justify a purchase.”
make it impossible for them to pay their creditors There is also a contrary school of thought
and clients. suggesting that consumers in some market
“Channel distribution will weigh even more geographies and segments will release pent-up
heavily towards online — and further away from demand once there is light at the end of the tunnel.
wholesale,” he added. Instead of restraint, some cohorts in the uber
26IN-DEPTH
Food delivery courier passes a closed Louis Vuitton store. Simon Dawson /Getty Images
wealthy demographic may choose to spend like crazy more amenable to such overtures. The same goes for
on decadent, fun, outrageous and exuberant things. the likes of Salvatore Ferragamo, Brunello Cucinelli
With either scenario in mind, expect an and even Ralph Lauren, while mid-sized companies
uptick in bespoke shopping experiences both online — those with annual revenues in the $100 to $500
and off, with customer relationship management million range — will struggle to compete against the
tools that allow brands to keep up an ongoing groups, which control everything from the supply
dialogue with each client. “Consumers want their chain down to the retail real estate.
shopping experience to be a bit more tailored to
them,” Idol said. “As a part of that, they want their “Consumers want their shopping
sales associates to really talk to them, think about
the way they dress.”
experience to be a bit more
Of course, this new reality will only affect tailored to them. As a part of that,
the companies that make it through the next six
they want their sales associates
months. Some companies will go private in order to
manage the situation without the pressure of public to really talk to them, think about
markets, as may be the case for supply chain giant the way they dress.”
Li & Fung. But the fallout signals an opportunity
for strategic groups like LVMH and Kering, which In the post-pandemic era, consolidation of
will have the capital to make further acquisitions of the luxury market will only intensify. Likening the
targets that may well be more affordable than they future rush of M&A activity to a possible “tsunami,”
once were when this is all over. Ortelli was quick to point out that the fallout from
Independently run companies including the coronavirus won’t be a crisis for everyone. For
Moncler and Prada, which have already been subject some luxury players it will definitely be “a unique
to takeover rumours for months, may suddenly be opportunity,” he said.
27You can also read


