Conquering the Chasm

Global Export Forecast
Spring 2015
←
→
Page content transcription
If your browser does not render page correctly, please read the page content below
Conquering the Chasm Global Export Forecast Spring 2015
Global export forecast

Table of Contents            EDC ECONOMICS
1.0 GEF Executive Summary

2.0 Country Risk Overviews   Peter Hall, Vice-President and Chief Economist
                             Tina Drew, Administrator
3.0 Sector Overviews

4.0 Provincial Overviews

                             Economic and Political Intelligence Centre

                             Stuart Bergman                        Todd MacDonald
                             Marc Antonius                         Ross Prusakowski
                             Daniel Benatuil                       Aimee Rae
                             John Bitzan                           Richard Schuster
                             Catherine Couture                     Geoff Stone
                             Nadia Frazzoni                        Ian Tobman
                             Andrea Gardella                       Peter Whelan

GLOBAL EXPORT FORECAST SPRING 2015                                                    2
Table of contents
1.0 GEF Executive Summary 5
Table of Contents
1.1 Conquering the Chasm 6
1.0 GEF Executive Summary
1.2 High-Wire Act, Euro-Style 9
2.0 Country Risk Overviews
1.3 The Contrasting Impacts of Plummeting Oil Prices 10
3.0 Sector Overviews
1.4 A Renminbi Hub for the Americas 11
4.0 Provincial Overviews
1.5 Swimming Without Shorts in a World Awash in Liquidity 12
2.0 Country Risk Overviews 14
2.1 Brazil 15
2.2 China 16
2.3 France 17
2.4 Germany 18
2.5 India 19
2.6 Japan 20
2.7 Mexico 21
2.8 Russia 22
2.9 South Africa 23
2.10 United Kingdom 24
2.11 United States 25
3.0 Sector Overviews 27
3.1 Energy 28
3.2 Ores and Metals 29
3.3 Agri-Food 30
3.4 Fertilizers 31
3.5 Forestry Products 32
3.6 Automotive 33
3.7 Industrial Machinery and Equipment 34
3.8 Advanced Technology 35
3.9 Aerospace 36
3.10 Chemicals and Plastics 37
3.11 Consumer Goods 38
3.12 Services 39
GLOBAL EXPORT FORECAST SPRING 2015 3Table of contents
4.0 Provincial Overviews 41
Table of Contents
4.1 Newfoundland and Labrador 42
1.0 GEF Executive Summary
4.2 Prince Edward Island 43
2.0 Country Risk Overviews
4.3 Nova Scotia 44
3.0 Sector Overviews
4.4 New Brunswick 45
4.0 Provincial Overviews
4.5 Quebec 46
4.6 Ontario 47
4.7 Manitoba 48
4.8 Saskatchewan 49
4.9 Alberta 50
4.10 British Columbia 51
GLOBAL EXPORT FORECAST SPRING 2015 41.0 GEF ExECUTIVE Summary
Table of Contents
1.0 GEF Executive Summary
1.1 Conquering
the Chasm T
1.2 High-Wire Act,
Euro-Style
1.3 The Contrasting
Impacts of Plummeting
Oil Prices
1.4 A Renminbi Hub
for the Americas
1.5 Swimming Without
Shorts in a World Awash
in Liquidity
2.0 Country Risk Overviews
3.0 Sector Overviews
4.0 Provincial Overviews
GLOBAL EXPORT FORECAST SPRING 2015 51.0 GEF ExECUTIVE Summary
Table of Contents 1.1 Conquering the Chasm
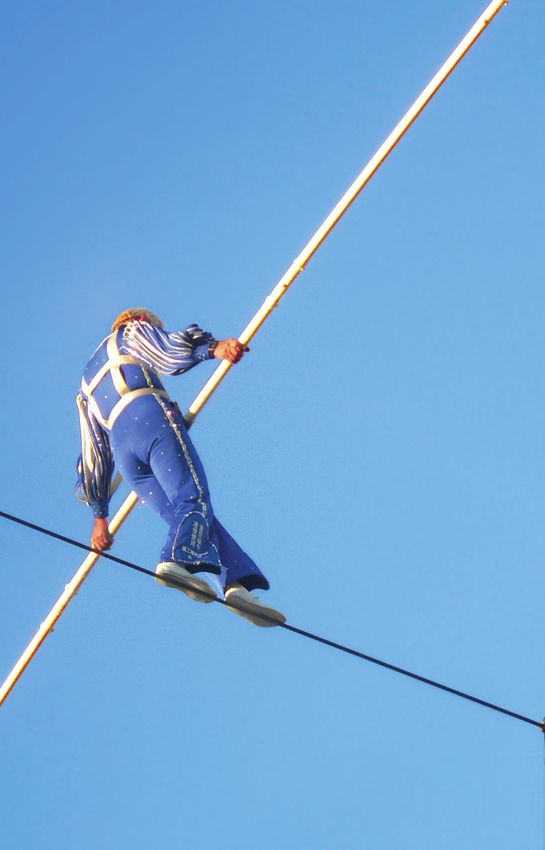
1.0 GEF Executive Summary The audience gasps. Way up in the vaulted canopy, the high-wire act falters. They’ve seen this all before,
1.1 Conquering numerous times. At first, they couldn’t look – the odds of a horrible end seemed too great. But time and again,
the Chasm the foothold was regained, and the act resumed. Now, it looks like that master wire-walker is actually going to
make it, and with rapt attention, the throng is willing that lone figure to succeed. Will the world economy’s
1.2 High-Wire Act,
high-wire act really end well?
Euro-Style
1.3 The Contrasting The setbacks have been manifold. Most recently, neo-stagnation has been the worry. From Europe’s brush with
Impacts of Plummeting “triple-dip” to Japan’s new-tax trauma to the demand difficulties of the emerging market giants, steady growth
Oil Prices has been elusive. Trouble is, steady economic movement is essential to coping with and overcoming the structural
1.4 A Renminbi Hub weaknesses revealed and magnified by the crisis of 2008-09. So far, so good: we have not been knocked off our
for the Americas game by impossible fiscal chasms, financial market carnage, waves of political upheaval, experimental policy
measures and a host of smaller but significant inhibitors. Consistent movement is about all that remains to get
1.5 Swimming Without
global commerce to the end of the high wire and on to a firmer footing.
Shorts in a World Awash
in Liquidity
Canada has had a firmer foothold than most, but lately there have been clear signs of fatigue. Consumer debt
2.0 Country Risk Overviews levels have soared. Housing markets are overbuilt. Governments at the provincial level still face years of austerity.
Plunging prices are decimating the resource industries, which have been until recently an economic mainstay.
3.0 Sector Overviews
Consequently, domestic investment is slowing. High-profile retailers are pulling up the tent pegs, while others are
4.0 Provincial Overviews consolidating. Suddenly, our own high-wire act is looking precarious. Will we make it?
Thankfully, there’s a wire-walker that is a standout. It certainly didn’t start well for this one; it began as the
weakest of the bunch. But it is now moving surely, and is practically running across the wire. And it just happens
to be Canada’s number one customer. America is going full-tilt, and thankfully, its success is catching on. Can its
momentum carry it – and the rest of us – along, or like the rest of the world, is it also at great risk of a bad turn
of events? The difference for the US economy is the presence of an essential ingredient – pent-up demand.
It is probably most obvious in the US housing market. Dramatic growth notwithstanding, US housing market
activity still finds itself well shy of the basic demographic requirements of the economy. That was necessary a few
years ago to get rid of the egregious excesses that had swamped the market. But those are now long gone, and it is
becoming more obvious that the market is in deficit. In fact, it can easily grow by 40% over the next year or two
and only just be meeting the current needs of the market. More growth is needed to deal decisively with the deficit.
What’s even more inspiring about this sub-market’s about-face is that it is a key leading indicator of economic
activity. Its movements are replicated in other economic developments months down the road. As such, if strong,
double-digit growth can be expected here, it is likely to show up elsewhere in short order. One of the first places is
consumer spending. Imagine all the fixings that are needed for the wave of newly built homes in the marketplace.
This demand in turn creates jobs and incomes that pull more players into the spending game. Not to mention that
Americans are driving around in clunkers that need a serious near-term upgrade.
Get the US consumer going, and it’s a major accomplishment. They account for almost 70% of the world’s largest
economy. Their absence over the past 7 years has been felt by the broader economy. Their return is having huge
repercussions, not just for the US economy itself, but for the world. Simple math shows that American consumers
account for 13 cents of every dollar that circulates worldwide. This revival is for everyone.
Is that the end of the story? Far from it. Believe it or not, there is even more excitement in the business investment
arena. Groggy from a protracted hibernation, US business is waking up to a crisis of a different sort. The fast
ramp-up of activity has gobbled up existing resources so quickly that there’s a widespread capacity crunch. Capital
spending has vaulted up into the double digits, and given the pace of new orders, more new capacity is definitely
needed in the near term. In fact, there’s a worry that the capacity to create new capacity is also tight, suggesting
risk that orders may not be met. Add it all up, and we are expecting US GDP growth of 3.6% this year, and 3.3%
in 2016. Does low capacity put this outlook at risk?
Ironic that we have been so worried about a lack of demand, and now it’s a lack of supply that may ruin the
recovery. Is it, indeed, a real threat to global growth? Quite the contrary, it’s likely a guarantee of growth. Global
crisis spurred a dangerous reversion to protectionism – Buy American, France First and so on. Sadly, some of the
greatest beneficiaries of globalization were the first to jump on the protectionism bandwagon. Re-shoring became
a popular buzz-word. The outcome? For starters, apart from very near neighbours, US growth has thus far been
GLOBAL EXPORT FORECAST SPRING 2015 61.0 GEF ExECUTIVE Summary
fairly self-contained. But bumping up against capacity limits changes the picture. Assuming firms will not turn
Table of Contents
business away, capacity is now more likely to be sourced from abroad – finally spreading the benefits of US
1.0 GEF Executive Summary growth further afield. Additional encouragement will come from the fast-appreciating greenback, up by over
12% on a trade-weighted basis since mid-2014. Do the numbers agree?
1.1 Conquering
the Chasm
It’s too early to tell, but so far, results are encouraging. The Eurozone has definitely shrugged off the worst fears
1.2 High-Wire Act, of a triple-dip, and recent data on both expectations and real activity are quite positive. There will need to be
Euro-Style much more evidence before we can conclude that Europe is on a new, higher-growth trajectory, but our
1.3 The Contrasting expectations, which are much the same as others’, is that growth will accelerate to 1.6% by 2016.
Impacts of Plummeting
Oil Prices Europe is on the move. Most of the news on China is bleak. Soft domestic demand, punctuated with stories of
1.4 A Renminbi Hub policy-led construction excesses and financial market fragility, is the predominant theme, leading many forecasters
for the Americas to write down growth to something just under 7%. Absent a significant change in external growth, this is
reasonable. However, considering the international trade vacuum that opened up in China back in 2009 and the
1.5 Swimming Without
lack of OECD-area growth since, a return to developed-market growth – starting with the US economy – suggests
Shorts in a World Awash
something much better for China’s exports in the near term. If our outlook for the US and the Eurozone is realized,
in Liquidity
it is entirely possible to see China’s export growth back up into double digits, enough to see trade climb back into
2.0 Country Risk Overviews the economy’s driver’s seat.
3.0 Sector Overviews
Plunging oil prices are adding more than a casual wrinkle to the outlook. Resource-sector investment has been
4.0 Provincial Overviews a vibrant island of growth in an otherwise weak world. Now that picture is changing, and there are big questions
about the net effects. These are covered in a special article on the issue. On balance, we believe that the positive
effects on net oil-consuming economies will outweigh the negative effects on the big oil producers, lifting global
growth. The price shakeout is itself related to the return of growth and the unwind of extraordinary post-crisis
monetary measures. Prices for a range of commodities were artificially high, and are now trying to find a more
stable platform. Until that point, we can expect turbulence.
World growth will benefit from the robust US performance and its knock-on effects on the rest of the world.
Our forecast calls for growth this year of 3.5%, and for an additional 3.9% in 2016. We’re getting to the end
of the tightrope.
Plunging resource prices are taking a bite out of Canadian GDP growth this year. The impact on the energy
sector is dramatic. However, lower resource prices have also brought the Canadian dollar down with them.
The non-energy manufacturing sector, already benefiting from the rise in US demand and tightening American
capacity, now has a currency bonus enhancing price competitiveness. The result is upheaval on multiple fronts.
Growth is shifting from the domestic sector to external demand, and even on the external side, growth is shifting
dramatically from the resource side to non-resource manufacturing and services. Given our expectation that oil
prices will average just over USD60 per barrel this year, the net effect on GDP growth is about 0.3%. As such,
Canada’s growth is expected to average 2.4% this year and next year.
Canadian exports did well in 2014. Merchandise exports grew by 10.9%, aided by favourable prices, but over
half of the growth was sheer volume activity. Momentum is strong going into 2015, and based on the shifts in
the economy, the outlook for overall trade is positive. The crying need for capacity stateside is expected to power
double-digit growth in non-mining equipment exports. The auto sector will also see two-digit performance,
thanks largely to the weaker dollar. Aerospace will capitalize on a strong showing in other aircraft and parts exports
and the slumping value of the Canadian dollar. Consumer goods will also do well, thanks to Americans opening
up their wallets once again.
Energy exports are the big spoiler. Volume shipments are actually forecast to rise modestly, but prices will
drive total sales down by 23.3%. A partial recovery is forecast for 2016, split roughly between volume gains and
a partial recovery in prices.
The bottom line? The global economy has very skillfully traversed its largest chasm in recent memory. It has been a
death-defying high-wire act, with safety nets that long since became very frayed. The wire-walker is perhaps weary,
but gaining courage from the success of efforts past and the obstacles overcome. While still vulnerable to any
disturbance, the current proximity to the “other side” is building confidence that we are making it. Our challenge?
To ensure that we shift along with the balance of growth, capturing as much of it as we can.
GLOBAL EXPORT FORECAST SPRING 2015 71.0 GEF ExECUTIVE Summary
Table 1: Key Economic Estimates (KEEs)
Table of Contents
1.0 GEF Executive Summary
EXPORT FORECAST OVERVIEW 2012 2013 2014 2015 (f) 2016 (f)
1.1 Conquering
the Chasm GDP (% y/y)
1.2 High-Wire Act, Canada 1.7 2.0 2.4 2.4 2.4
Euro-Style United States 2.3 2.2 2.4 3.6 3.3
1.3 The Contrasting Euro Area -0.7 -0.5 0.8 1.4 1.6
Impacts of Plummeting Japan 1.5 1.6 0.1 1.1 1.2
Oil Prices
Developed Markets 1.2 1.3 1.8 2.5 2.5
1.4 A Renminbi Hub
Emerging Asia 6.7 6.6 6.5 6.8 6.9
for the Americas
Latin America and the Caribbean 2.9 2.8 1.2 1.2 2.4
1.5 Swimming Without
Shorts in a World Awash Emerging Europe 7.4 4.7 2.7 -1.3 0.8
in Liquidity Africa and Middle East 5.0 3.1 3.3 4.1 4.8
2.0 Country Risk Overviews Emerging Markets 5.1 4.7 4.4 4.3 4.9
3.0 Sector Overviews World Total 3.4 3.3 3.3 3.5 3.9
Currencies
4.0 Provincial Overviews
USD/CAD 1.00 0.97 0.91 0.82 0.84
Commodity Prices
WTI $94 $98 $93 $61 $71
Lumber (WSPF, US$ per thbf) $255 $318 $349 $383 $400
Copper (USD/MT, LME) $7,947 $7,322 $6,862 $5,806 $5,995
Wheat: Canada (USD/Metric Ton) $7 $7 $6 $5 $6
Other
US housing starts (‘000s) 780.60 924.90 1,005.80 1,350.00 1,550.00
Sources: Statistics Canada, EDC Economics
Table 2: Canadian Merchandise Export Forecast by Region
% Share Export Outlook
CAD bn of Total (% growth)
EXPORT FORECAST OVERVIEW 2014 2014 2014 2015 (f) 2016 (f)
Developed Markets
United States 375.9 76.5 12.2 -1 9
Western Europe 39.2 8.0 15.5 2 6
Japan, Oceania and Developed Asia 23.4 4.8 2.9 1 -2
Emerging Markets
Latin America and the Caribbean 13.3 2.7 7.3 4 5
Emerging Europe and Central Asia 3.5 0.7 -5.3 -6 3
Africa and the Middle East 8.4 1.7 17.8 7 7
Emerging Asia 27.8 5.7 -2.1 4 5
Total Goods Exports 491.6 100.0 10.9 0 8
Total Emerging Markets 53.1 10.8 2.7 4 5
Total Developed Markets 438.5 89.2 11.9 -1 8
Sources: Statistics Canada, EDC Economics
GLOBAL EXPORT FORECAST SPRING 2015 81.0 GEF ExECUTIVE Summary
Table of Contents 1.2 High-Wire Act, Euro-Style
1.0 GEF Executive Summary Among recent synonyms for slow, Europe’s economy ranks close to the top. Beset by a plethora of deep structural
1.1 Conquering strictures, Europe watchers wonder that there has been any growth at all, and that its latest brushes with recession
the Chasm have not brought it down. It has put to severe test a zone known throughout history for its irreconcilable schisms.
Some openly doubted the mega-economy’s ability to withstand its first recession. So far, it has outlasted a very
1.2 High-Wire Act,
severe one, although it is not yet out of the woods. Will the Euro Area outlast its manifold structural challenges,
Euro-Style
or is the single market, as we know it, still at risk?
1.3 The Contrasting
Impacts of Plummeting There is a long list of irritants. Close to the top would be slow growth itself. OECD’s projection for annual growth
Oil Prices potential is a skinny 1%, against over 2% in the US. The battle for a share of this wealthy but sluggish market
1.4 A Renminbi Hub is bound to keep intra-regional trade a hot issue. Weak overall population growth is key to sluggish demand
for the Americas projections, keeping immigration an obvious policy priority. But slow growth and divergences in sub-population
growth rates have for some time created divisions along racial lines – which from time to time escalate to the top
1.5 Swimming Without
levels of politics. Current demographic trends suggest that intra-country and intra-region population friction will
Shorts in a World Awash
likely only rise over time, elevating risk of instability.
in Liquidity
2.0 Country Risk Overviews Public finances in the Euro Area are another source of irritation. All countries are in violation of the Maastricht
rules, but some a lot more than others. Discipline around these rules is fundamental to cohesion, and lax or
3.0 Sector Overviews
flawed adherence to these was laid bare following the wave of extraordinary post-crisis stimulus. Surprisingly,
4.0 Provincial Overviews scathing austerity – imposed, in certain cases – was agreed to, and while acrimonious, did not rend the Area’s
political fabric. But it’s stretching it pretty thin now. Oddly, as austerity is now bearing tangible fruit – with
Europe’s worst fiscal sinners either achieving or marching fast toward balanced budgets – anti-austerity
movements are gaining momentum, and in Greece’s case, getting elected. With debt ratios still impossibly
high in a number of cases, fiscal-led dissent ain’t over yet.
The list grows. Near collapse of Europe’s financial system, linked as it was to its fiscal woes, is exacerbating
sluggish growth. Tight regulatory rules and a desire to attain them first have compromised lending activity.
Latent structural weakness suggests this mindset will be around for a while. One remedy has been cleverly
constructed monetary measures, purchases of select asset classes designed to enhance intra-regional lending.
Insufficient, this has morphed into “whatever-it-takes” monetary easing, acceptable to many but anathema to
inflation-averse Germans. In its infancy, the program is being tolerated, but at the sight of price acceleration
there are bound to be “words.”
To this we can add geopolitical concerns. As if the Euro Area did not have enough internal pressures, the Russia–
Ukraine conflict flared up virtually out of nowhere. One key implication is access to energy. Russia supplies Europe
with about half of its oil and about one-third of its natural gas, creating a short-run supply problem during the
recent European winter, in addition to compromising the deep bilateral financial and economic ties. Resolution
can’t be predicted at this point, so the internal European tensions surrounding alternative reprisals, sanctions and
solutions are, with other tensions, likely to persist.
These and other extant Euro risks are an ever-present cloud over a tenuous recovery. US recovery, clear
signs of pent-up European demand on multiple fronts, impressive recent data, a rapid run-up in the composite
leading indicator and a decent consensus forecast all suggest a brighter near-term outlook than the risks suggest.
For now, growth seems to be gingerly winning out. But the presence of the daunting risk list is a reminder that
any growth interruption is a heart-stopper.
The bottom line? Make no mistake, nascent growth notwithstanding, Europe has a tough economic and political
row to hoe in the coming years. Will it make it? Few of the current list items are new. If anything, it’s more than a
small miracle that Europe has made it this far. If growth outshines expectations – and there’s a good chance it will –
Europe may just do it.
GLOBAL EXPORT FORECAST SPRING 2015 91.0 GEF ExECUTIVE Summary
Table of Contents 1.3 The Contrasting Impacts of Plummeting Oil Prices
1.0 GEF Executive Summary Plunging crude oil prices have dramatically changed the economic growth landscape. Canada knows this all
1.1 Conquering too well – anything related to oil seems to be in freefall, while outside of energy, industry is expecting a bonanza.
the Chasm The effect is being felt across the global macroeconomy. Oil exporters are counting their losses, while net
importers are already projecting handsome dividends. As an imminent rebound is unlikely, how will the price
1.2 High-Wire Act,
plunge change world growth? And how is Canada expected to fare?
Euro-Style
1.3 The Contrasting Let’s start with the bad news. Oil net exporters, like Canada, are bleeding cash. The biggest net exporter is
Impacts of Saudi Arabia, at 8.4 million barrels per day. At a world price of $60 per barrel, that’s costing them about
Plummeting Oil Prices $100 billion annually. Russia is second, with a net hit of $87 billion annually. The rest of the Middle East loses
1.4 A Renminbi Hub another $100 billion, with Nigeria and Venezuela also making the top list of money losers. Canada is feeling
for the Americas the pain, significantly, but industrial diversification is saving us from a far more negative result. If it is any
additional solace, we don’t even make the top 10.
1.5 Swimming Without
Shorts in a World Awash
Panning through the extensive list of global net exporters, it is clear that while non-oil Canadian exports go to
in Liquidity
these destinations, with the exception of Russia, these account for 1.8% of total Canadian exports. In Russia’s
2.0 Country Risk Overviews case, exports are being hampered already by sanctions, and as such, are limiting the direct impact of the oil shock
on trade activity. Overall, it’s not a great news story, as individual exporters that have had success in oil-rich markets
3.0 Sector Overviews
will suffer. But on the whole, the net damage to Canada will be limited. As bad news goes, we’ve seen worse.
4.0 Provincial Overviews
How about the good news? The flipside is that net importers are saving money – buckets of it. At a $60 average
price for West Texas Intermediate crude, the US – the world’s top net importer in 2013 (the latest annual data
we have) – saves over $100 billion annually. Add another $50 billion if the price averages $45. Much of this
gets passed on to consumers in lower pump prices. If it were all passed on, it adds up directly to about 0.8%
of US consumer spending – a huge one-year boost. The impact of this on Canada’s top customer is likely
Table 3:
already translating into higher imports of Canadian goods. It doesn’t hurt that our dollar is now about 20%
cheaper than a year ago. Estimates of the impact on the US economy this year range from 0.3 to 0.6% on
total GDP growth, and that could be conservative. For the world’s top economy, already seeing a decent revival,
and for Canadian exporters, not bad news at all.
TOP GLOBAL
OIL IMPORTERS
AND EXPORTERS
Some of Canada’s largest traditional trading partners make the top 10 list of global oil net-importers. Among them,
(millions of barrels per day, 2013) Japan is next to the US, totally dependent on external supply, and at $60 oil, set to save $50 billion this year.
Net importers Amount
South Korea and Germany each save just under $30 billion on their national bill, and France is good for another
$20 billion. These funds will clearly spill through the economy and have a magnified positive effect. It could hardly
US 8.8 come at a better time for Europe, and Canada should gain in export sales.
China 6.6
Oil cost-savings are substantial across a broad swath of the emerging world. China depends on the rest of the
Japan 4.6
world for 6.6 million barrels a day of crude oil. With prices down by over $30 per barrel this year, it is estimated
India 2.8 it will save a whopping $77 billion. India, next on the developing market list, looks to the rest of the world for
South Korea 2.5 2.8 million barrels per day, generating equivalent savings of $33 billion annually. Savings aren’t miniscule in
non-oil-producing South and Central America, and oil-producer Brazil still depends on external supply to fill
Germany 2.4
its economy’s needs. The list of oil-dependent emerging nations goes on and on.
Net exporters Amount
Saudi Arabia 8.4 The benefits of these lower prices vary with the individual internal market structures. Many emerging nations
subsidize local fuel prices, to shield citizens – mainly the poorer ones – from global price fluctuations. As such,
Russia 7.5 pass-through of savings to consumers won’t be as direct as for OECD nations in a good number of cases.
Iraq 3.1 However, it is interesting to note that several governments are taking advantage of low oil prices to reduce
or eliminate subsidies. One way or another, emerging economies will benefit. Either their consumers will have
United Arab 2.9
Emirates more purchasing power, or their governments will have added fiscal flexibility, and consequently a lower overall
risk profile – boosting their appetite for foreign goods and services.
Kuwait 2.6
Nigeria 2.3 The bottom line? Canada’s energy sector service and equipment exporters are in for tough times, and cash flows
Venezuela 1.8 for oil and gas exporters will tighten significantly. This is already beginning to spill red ink on Canada’s trade and
fiscal statistics. However, Canada’s non-energy sector exporters should see a substantial boost. Look for stronger
Sources: BP Statistical Review
of World Energy, EDC
demand growth for a whole range of Canadian products emanating from the advanced markets that are net oil
importers and where lower oil prices translate directly to the gas pump. Emerging market oil importers will be a
mixed bag, but in general exports to these destinations should see some lift this year. This will be modestly offset
by declining demand from the big oil exporters. It is fair to say that on balance, the oil price swoon is a piece of
very well-timed private market stimulus for the world economy.
GLOBAL EXPORT FORECAST SPRING 2015 101.0 GEF ExECUTIVE Summary
Table of Contents 1.4 A Renminbi Hub for the Americas
1.0 GEF Executive Summary On March 23rd, the grumpy Monday morning crowd had something to smile about: the renminbi (RMB) stepped
1.1 Conquering into Canada with the inauguration of the only RMB hub in the Americas, one more advance on its long march to
the Chasm internationalization. It all began with its first step into Hong Kong more than a decade ago. A long pause, and then
a move into Southeast Asia in 2013. Then Europe in 2014. In each of these locations, the RMB’s arrival was both
1.2 High-Wire Act,
eagerly anticipated and ballyhooed. In Canada, it was also greeted with fanfare, but what is less certain is whether
Euro-Style
or not Canadian exporters and international investors will take action as they move forward. Should they?
1.3 The Contrasting
Impacts of Plummeting It sure seems so. Consider the marvel of the RMB’s rise. Simply put, we are watching history in the making.
Oil Prices Within the span of the last five years, the RMB went from being virtually non-existent outside the People’s Republic
1.4 A Renminbi Hub to the fifth-most-used payments currency in the world as of last autumn. And there is little doubt that before long it
for the Americas will overtake the Japanese yen and be fast on the heels of the pound.
1.5 Swimming Without
By comparison, the only globally significant currencies to internationalize in the last half-century were the euro
Shorts in a World Awash
and the yen. And neither one is indicative of the RMB’s future prospects. In the euro’s case, the currencies
in Liquidity
that merged together were already hard currencies. As for the yen, it internationalized under very different
2.0 Country Risk Overviews circumstances – we know that Tokyo’s global aspirations for the yen, and the rest of the world’s appetite for it,
were measured from the outset.
3.0 Sector Overviews
4.0 Provincial Overviews In contrast, Beijing has made it clear that it intends to transform the RMB into a global reserve currency.
Moreover, China has arrived as an economic superpower and established robust trading relationships with every
corner of the globe. Most will not be surprised, for instance, to hear that China is Asia’s largest trading partner.
Fewer realize that China overtook Europe as Africa’s largest trading partner and fewer still are aware that China is
set to overtake Europe as Latin America’s second-largest partner as early as 2016. It may or may not be well known,
but here in Canada, China stands quite alone as our second-largest trading partner. In other words, the demand
structure for RMB internationalization is global in scope, deeper than that of the yen, and alive and growing here
in Canada.
With these realities in mind, Canadian companies would do well to take notice, consider ways of leveraging the
opportunities the RMB’s arrival presents to them, and take appropriate measures to mitigate the risks. Regarding
risks, the story is clear. The establishment of RMB trading hubs across Asia and Europe is spurring our competitors
in Australia, the UK, Germany, and South Korea, to name just a few, to experiment with RMB-denominated trade
solutions. If Canadian companies are not willing to step out in the same way, they may find themselves having
trouble gaining or maintaining their market share in China in the near- to mid-term.
On the opportunities front, the benefits are equally apparent. By adopting the RMB as a payments currency,
Canadian traders will have access to a wider universe of Chinese clients, and at the same time, improve their bottom
lines. This is because the vast majority of China’s traders are SMEs, most of which do not have USD liquidity.
As such, they need to rely on foreign exchange agents to access dollars, who in turn charge service fees and impose
conversion ceilings. At the end of the day, this system creates bottlenecks and costs, not to mention manifold
frustration. However, if payment was made in RMB, life would become a whole lot easier and cheaper for everyone
involved – except, of course, the foreign exchange agent.
Finally, timing is also important, especially for our exporters. The RMB is expected to continue its fall against the
US dollar during 2015. China’s importers will be more receptive than ever to denomination of contracts in RMB.
The bottom line? The RMB’s long march to internationalization is rewriting the rules of engagement and, in the
process, creating new risks and opportunities for the global trading community. As the celebration of our new hub
dies down, it’s time for Canadians to roll up our sleeves and make the most of it.
GLOBAL EXPORT FORECAST SPRING 2015 111.0 GEF ExECUTIVE Summary
Table of Contents 1.5 Swimming Without Shorts in a World Awash in Liquidity
1.0 GEF Executive Summary Six years ago, a world that teetered on the edge of the worst economic plunge since the Depression was arguably
1.1 Conquering rescued by a wave of massive and unprecedented coordinated public stimulus measures. Among other things,
the Chasm central bankers of the world opened the floodgates to a surge of liquidity that would help carry a panicking global
economy to the shores of relative safety. One unintended side effect of quantitative easing (QE) saw investment cash
1.2 High-Wire Act,
flood out of safe assets and into a number of riskier ones.
Euro-Style
1.3 The Contrasting This never-ending search for yield helped bid up the price of emerging market sovereign and commercial debt.
Impacts of Plummeting Currency forecasters were forced to abandon their traditional models, or at least substantially up their “speculation”
Oil Prices components, in the face of a reinvigorated carry trade. Global equity markets began their ascent to new peaks.
1.4 A Renminbi Hub And copper’s 123% surge in 2009, viewed against a completely stagnant global economy, prompted calls to strip
for the Americas the red metal of its honorary doctorate in economics, so bestowed for its past ability to predict global growth cycles.
1.5 Swimming Without
But if, as the saying goes, a rising tide raises all boats, then (as Warren Buffet likes to remind us) it’s only when
Shorts in a World
the tide goes out that we see who was swimming without shorts. The eventual net reduction in aggregate global
Awash in Liquidity
liquidity means that there will, at some point, be less money available for everyone. And while there will be winners
2.0 Country Risk Overviews and losers, some losers will lose more than others.
3.0 Sector Overviews
In emerging markets, while capital inflows tumbled almost 20% last year, and another stressful year is expected
4.0 Provincial Overviews in 2015, some did take advantage of the high tides to boost competitiveness, make labour markets more flexible
and improve the efficiency of public institutions – a divergence highlighted by the effects of the taper tantrum.
So the real impact on emerging markets will be the return of risk differentiation within the emerging market class.
While this is a normal process that markets have to endure every few years, the real concern is more around the
absurd extreme of that lack of risk differentiation. QE didn’t simply encourage investors to explore traditional
corporate and sovereign risk. Given the flood of money chasing somewhat limited assets, securing a decent return
meant venturing further along the risk continuum. This prompted investors to embrace a host of higher-risk assets,
at increasingly declining returns – returns that may not be adequately compensating them for the risks assumed.
The consequences of these ultra-loose monetary policy distortions? At one point, investors were offered less than
250bps for assuming Gabon sovereign risk over US Treasury risk. US junk bond issuances have soared since 2009,
and prices for high-yield corporate debt tested historical peaks. Last year, we had more than $20 billion go into
subprime auto asset-backed securities. Subprime ABS. And once we ran out of places to stash our cash, we began
betting on the weather. Investors snapped up $8.1 billion worth of catastrophe bonds last year, most of which went
to pension funds and other large institutional investors. Even in Germany, a country not typically known for bubbly
behaviour, demand for investment properties has heated up, pushing the price of new-builds up more than 25%
since July 2009.
However, in a world of negative interest rates, such probability-weighted expected loss may be a reasonable
alternative to the certainty of costs charged on deposits. But, what happens when some of these recent entrants
into the sovereign bond market struggle to service foreign currency debt, as local currencies depreciate?
Could pension funds be in for a surprise the next time a major hurricane strikes a small island economy?
The bottom line? Perhaps the threat of the imminent economic plunge was so catastrophic back in 2009 that
officials were forced to focus on that. But if, as some say, 2008-09 was a function of the recession we didn’t have
in 2000-01, then what would the bursting of some of these bubbles look like over the medium term? The cash
we pumped into the system this time around makes Greenspan look like a hawk. One can only hope that national
regulators have learned more from the last seven years than markets have.
GLOBAL EXPORT FORECAST SPRING 2015 122.0 COUNTRY RISK Overviews
Table of Contents
1.0 GEF Executive Summary
2.0 Country Risk Overviews
2.1 Brazil
2.2 China
2.3 France
2.4 Germany
2.5 India
2.6 Japan
2.7 Mexico
2.8 Russia
2.9 South Africa
2.10 United Kingdom
2.11 United States
3.0 Sector Overviews
4.0 Provincial Overviews
GLOBAL EXPORT FORECAST SPRING 2015 132.0 COUNTRY RISK Overviews
Table of Contents Glossary of Terms
1.0 GEF Executive Summary
Short-Term Commercial
2.0 Country Risk Overviews
Risk Rating
2.1 Brazil
Average default rate on credit commitments of one year or less on the part of commercial obligors in a country.
2.2 China
2.3 France
Payment Experience
2.4 Germany Measured by the number and size of EDC claims experienced in a particular country, over a period of a year,
relative to EDC’s business volume growth.
2.5 India
• Positive: The number of claims, or the amounts claimed have decreased in proportion to EDC business
2.6 Japan volume growth.
2.7 Mexico • Neutral: The number of claims, or the amounts claimed have remained unchanged in proportion to EDC
2.8 Russia business volume growth.
2.9 South Africa • Negative: The number of claims, or the amounts claimed have increased in proportion to EDC business
volume growth.
2.10 United Kingdom
2.11 United States Medium-Long-Term Commercial
3.0 Sector Overviews
Commercial Country Ceiling
4.0 Provincial Overviews
The Commercial Country Ceiling (CCC) is meant to represent the best possible rating that can be assigned
to commercial obligors domiciled in a country. The CCC is impacted by the Sovereign Probability of Default,
political risks (transfer and inconvertibility, political violence, expropriation) and other mitigating or
Risk Rating Lexicon
exacerbating factors.
Low
Low-Medium
Expropriation
Medium The likelihood, over the medium to long term of government action (e.g. outright seizure of an asset/
Medium-High investment or less pronounced interference such as unjustified non-renewal of required permits or licences) or
High weak governance conditions (e.g. a weak rule of law or high levels of corruption) having a significant impact on
a country’s commercial environment.
Prohibitive
No Information Transfer and Conversion
The likelihood, over the medium to long term, of a government imposing conversion or transfer restrictions
Payment Experience Lexicon
that significantly affect the commercial environment. Conversion restrictions could include measures that
Positive prevent companies from converting local currency to hard currency, while transfer restrictions would be
Neutral measures that inhibit the transfer of said hard currency out of the host country by legal means.
Negative Political Violence
The likelihood, over the medium to long term, of an act of political violence occurring in a country that
significantly impacts the country’s commercial environment. Political violence events can include acts of war
(declared or undeclared), insurrection, revolution, rebellion, riot, terrorism, sabotage, civil disturbance, or other
such violent acts that are politically motivated.
Sovereign
The Sovereign Probability of Default (SPD) measures the ability and willingness of a sovereign to honour its
financial obligations over the medium to long term.
GLOBAL EXPORT FORECAST SPRING 2015 14Economic and Political Intelligence Centre Spring 2015
Brazil RISK Overviews
2.0 COUNTRY
Table of Contents
2.1 Brazil
1.0 GEF Executive Summary
Short-Term CommercialShort-Term Commercial Current Account and Economic
2.0 Country Risk Overviews Growth
Risk Rating Risk Rating
Payment Experience
2.1 Brazil Payment Experience 2013 2014 2015 2016
4
In order
2.2 China to normalize its highly overvalued
In order to normalizecurrency and
its highly increasecurrency
overvalued 2
competiveness,
2.3 France the Central Bank is attempting to reverse
and increase competiveness, the central ineffective
bank is 2
monetary policies. Althoughattempting
the Brazilian real is expected to normalize
% of GDP
to reverse ineffective monetary policies.
2.4 Germany
over the coming months, it will experience considerable downward 0 0
Although the Brazilian real is expected to normalize
%
pressures
2.5 India in H1-2015 due toover bearish economic
the coming months,activity and as theconsiderable
it will experience
“Lava-Jato” scandal spreadsdownward
beyond Petrobras.
pressures in That
H1-2015said,duea high level of
to bearish -2
2.6 Japan
foreign exchange reserves continue
economicto resultand
activity in as
overall benign liquidity
the “Lava-Jato” scandal -2
spreads beyond Petrobras. That said, a high level -4
conditions
2.7 Mexico for the commercial sector. Sweeping reforms affecting the of
business sector are unlikely,foreign exchangeshould
but investors reservesexpect
continuemoderate
to result inpolicy
overall Current Account Balance
2.8 Russia benign liquidity conditions for the commercial sector.
shifts over the next 12 months. Real GDP Growth
Sweeping reforms affecting the business sector are
2.9 South Africa
unlikely, but investors should expect moderate policy
Medium-Long
2.10 United KingdomTerm Commercial
shifts over the next 12 months. World Bank Governance Indicators
100
2.11 United States
Commercial Country Ceiling Expropriation
3.0 Sector Overviews
Medium-Long-Term Commercial
Transfer Overviews
and Conversion Commercial Country
Political Ceiling
Violence 55 55 52
4.0 Provincial 51
Expropriation 50
The commercial environment is characterized
Transfer by a persistently strong
and Conversion
Political
banking sector, lack of financial Violence and low dependence on
dollarization,
foreign borrowing. The government will continue efforts to reverse
The commercial environment is characterized by a 0
inflation and tepid growth, as well as address poor infrastructure, but
persistently strong banking sector, lack of financial Control of Government Regulatory Rule of Law
investment activity remainsdollarization,
bearish. Additionally, reformsonand
and low dependence efforts
foreign to
borrowing. Corruption effectiveness Quality
stimulate the economy may Thebe over-shadowed by the on-going
government will continue efforts to reverse inflation
corruption investigations relating to growth,
and tepid Petrobras. While
as well Brazil
as address is infrastructure,
poor expected The percentile rank term ranges from 0 (lowest rank)
to be a net-benefactor of weaker oil prices,
but investment MLT
activity investment
remains bearish.in pre-salt
Additionally, to 100 (highest rank).
oil exploration and production mayand
reforms be efforts
impacted shouldtheprices
to stimulate economyfallmay
close
be
to USD 45 a barrel. over-shadowed by the on going corruption investigations Public Finances
relating to Petrobras. While Brazil is expected to be a net
5
Sovereign benefactor of weaker oil prices, medium to long-term 50
investment in pre-salt oil exploration and production may
be impacted should prices fall close to USD 45 a barrel.
Sovereign Probability of Default
0 0
Although increasing in levels, external debt metrics remain relatively
Sovereign
healthy, and financing needs will continue to be mostly absorbed by the
domestic market. Foreign currency-denominated
Sovereign Probabilitydebt is a very small
of Default -50
portion of total government debt and, as a result, exchange rate risk is -5
minimal. In the aftermath ofAlthough increasing
the elections in levels,2014,
in October external debtismetrics
there 2013 2014 2015 2016
remain relatively healthy, and
tremendous pressure to implement much-needed reforms in order financing needs
to will
continue to be mostly absorbed by the domestic
reverse slow growth and investment activity, as well as improve fiscal Fiscal Balance (% of GDP)
market. Foreign currency-denominated debt is a
management. However, reforms will face increasing roadblocks as
very small portion of total government debt and, Public Debt (% of GDP)
efforts meet strong congressional opposition,
as a result, exchangeandrate will
risk isbeminimal.
made more
In the
challenging with the political fall out of the “Lava-Jato” scandal.
aftermath of the elections in October 2014, there Sources: EDC Economics, World Bank,
is tremendous pressure to implement much-needed Haver Analytics, EIU
reforms in order to reverse slow growth and
investment activity, as well as improve fiscal
management. However, reforms will face increasing
roadblocks as efforts meet strong congressional
opposition, and will be made more challenging
with the political fall-out of the Lava-Jato scandal.
GLOBAL EXPORT FORECAST SPRING 2015 15Economic and Political Intelligence Centre Spring 2015
China RISK Overviews
2.0 COUNTRY
Table of Contents
2.2 China
1.0 GEF Executive Summary
Short-Term CommercialShort-Term Commercial Current Account and Economic
2.0 Country Risk Overviews Growth
Risk Rating Risk Rating
Payment Experience
2.1 Brazil Payment Experience 2013 2014 2015 2016
8
Residential
2.2 China property, small-Residential
and medium-sized enterprises
property, small- and
and medium-sized
state-owned banks could come under stress as growth eases a notch. 2
2.3 France enterprises and state-owned banks could come 6
Ample foreign exchange reserves
under stress as growth eases a notch. Amplesuggest
and China’s net creditor status
% of GDP
foreign
2.4 Germany
currency stability. Althoughexchange
the CB reserves
loweredand theChina’s
reservenetrequirement
creditor status 4
%
ratio recently, an easing in interest rates may
suggest currency be around
stability. thethe
Although corner inbank
central an 1
2.5 India
attempt to help spur growth,lowered
whichthe could leadrequirement
reserve to some near-term
ratio recently, 2
2.6 Japan
currency weakening. an easing in interest rates may be around the corner
in an attempt to help spur growth, which could lead 0 0
2.7 Mexico
to some near-term currency weakening. Current Account Balance
2.8 Russia
Real GDP Growth
2.9 South Africa Medium-Long-Term Commercial
Medium-Long
2.10 United KingdomTerm Commercial World Bank Governance Indicators
Commercial Country Ceiling
100
Commercial Country Ceiling ExpropriationExpropriation
2.11 United States
Transfer and Conversion
3.0 Sector Overviews
Political Violence
Transfer Overviews
4.0 Provincial and Conversion Political Violence 54
Current policy goals include economic reform 50 47
43 40
Current policy goals includeofeconomic
state-owned enterprises,
reform opening up to
of state-owned private
enterprises,
competition and foreign ownership,
opening up to private competition and foreign ownership, land land ownership,
and resource pricing. An export recovery is expected
ownership, and resource pricing. An export recovery is expected to play
to play out going forward. Shifting growth inland 0
out going forward. Shifting will
growth inland will open up new opportunities
open up new opportunities for transportation Control of Government Regulatory Rule of Law
for transportation and distribution networks. Localized
and distribution networks. protests
Localized over
protests over Corruption effectiveness Quality
corruption, the environment,corruption,
and land the
ownership will continue.
environment, and land ownership
will continue. The percentile rank term ranges from 0 (lowest rank)
to 100 (highest rank).
Sovereign Public Finances
20
Sovereign Probability of Default
Sovereign
2
China appears resilient to external shocks. 10
Sovereign Probability of Default
Despite a low external debt burden, the sovereign
could be saddled with contingent liabilities linked 0 0
China appears resilient to external shocks. Despite
to local government a low external
debts, state-owned debt
enterprises,
burden, the sovereign couldandbe saddled
state bankwith contingentloans.
non-performing liabilities linked
The government -10
to local government debts, state-owned
will implemententerprises, and packages
modest spending state-bankand credit -2
easing to support
non-performing loans. The government willgrowth in ordermodest
implement to manage these risks.
spending -20
packages and credit easing to support growth in order to manage these 2013 2014 2015 2016
risks.
Fiscal Balance (% of GDP)
Public Debt (% of GDP)
Sources: EDC Economics, World Bank,
Haver Analytics, EIU
GLOBAL EXPORT FORECAST SPRING 2015 16Economic and Political Intelligence Centre Spring 2015
France RISK Overviews
2.0 COUNTRY
Table of Contents
2.3 France
1.0 GEF Executive Summary
Short-Term CommercialShort-Term Commercial Current Account and Economic
2.0 Country Risk Overviews Growth
Risk Rating Risk Rating
Payment Experience
2.1 Brazil Payment Experience 2013 2014 2015 2016
TheChina
2.2 French economy exitedThe
recession in the third
French economy quarter
exited of 2014,
recession in the but 1
1
crawled
2.3 France toward year-end, posting annual GDP growth of
third quarter of 2014, but crawled toward0.4 per year-end,
cent for
the third consecutive year. The outlook is expected to improve but
% of GDP
posting annual GDP growth of 0.4% for the
2.4 Germany
remain lackluster, underperforming the wider
third consecutive year.EUTheand euroisarea
outlook averages
expected 0 0
%
with growth
2.5 India exceeding one per
to cent
improve only
but as of
remain 2016. The
lacklustre, lack of
underperforming
progress on structural reforms
the is evident
wider EU andin the
Eurorising trade deficit
area averages and
with growth
2.6 Japan -1
stubbornly high unemployment; household
exceeding 1% onlyconsumption
as of 2016. The and
lackbusiness
of progress -1
investment
2.7 on structural
Mexico remain weak. Lending reforms
remains tightis evident
and theintopthe French
rising trade
banks have been downgraded deficit and stubbornly
because of exposure high to
unemployment;
the troubledhousehold Current Account Balance
2.8 Russia consumption and business investment remain weak.
countries of peripheral Europe. Real GDP Growth
Lending remains tight and the top French banks have
2.9 South Africa
been downgraded because of exposure to the troubled
Medium-Long
2.10 United KingdomTerm Commercial
countries of Peripheral Europe. World Bank Governance Indicators
100 88 89 88
2.11 United States 85
Commercial Country Ceiling Expropriation
3.0 Sector Overviews
Medium-Long-Term Commercial
Transfer Overviews
4.0 Provincial and Conversion Political Ceiling
Commercial Country Violence
Expropriation 50
France has a great number of highly successful
Transfer world-class companies.
and Conversion
However, most are struggling with the
Political weak export demand that lingers
Violence
from the Eurozone crisis. The credit environment remains tight; however,
France has a great number of highly successful
increased liquidity throughout the euro area resulting from the European 0
world-class companies. However, most are struggling
Central Bank’s quantitative with
easing program is expected to improve the
the weak export demand that lingers from the
Control of
Corruption
Government
effectiveness
Regulatory
Quality
Rule of Law
credit transmission mechanism.Eurozone French
The government
crisis. The has shown
credit environment little
remains
interest in the types of structural reforms increased
tight; however, that couldliquidity
improve businessthe
throughout The percentile rank term ranges from 0 (lowest rank)
competitiveness. euro area resulting from the European Central to 100 (highest rank).
Bank’s quantitative easing program is expected
to improve the credit transmission mechanism. Public Finances
The French government has shown little interest 5 100
Sovereign in the types of structural reforms that could
improve business competitiveness.
Sovereign Probability of Default
Sovereign 0 0
France is expected to continue facing challenging public debt dynamics
over the next two years. By Sovereign
2017, government
ProbabilitydebtofasDefault
a share of GDP is
expected to peak at almost 100 per cent, while the fiscal balance is
projected to fall below the EU’s
FranceMaastricht
is expectedTreaty threshold
to continue of three per
facing challenging -5 -100
cent of GDP. Deeper reforms public debt dynamics
are urgently overtothe
needed next two
balance theyears.
budget
By 2017, government debt as a share of GDP 2013 2014 2015 2016
and improve debt sustainability. There are few concrete plans for
spending reductions; instead,is expected to peak athas
the government almost 100%, while
promised thetaxes
to raise
fiscal balance is projected to fall below the EU’s Fiscal Balance (% of GDP)
on the wealthy and on business. Austerity plans have been put on hold
Maastricht Treaty threshold of 3% of GDP. Public Debt (% of GDP)
for the next two years. Deeper reforms are urgently needed to balance
the budget and improve debt sustainability. Sources: EDC Economics, World Bank,
There are few concrete plans for spending Haver Analytics, EIU
reductions; instead, the government has promised to
raise taxes on the wealthy and on business. Austerity
plans have been put on hold for the next two years.
GLOBAL EXPORT FORECAST SPRING 2015 17Economic and Political Intelligence Centre Spring 2015
Germany
2.0 COUNTRY RISK Overviews
Table of Contents
2.4 Germany
1.0 GEF Executive Summary
Short-Term CommercialShort-Term Commercial Current Account and Economic
2.0 Country Risk Overviews Growth
Risk Rating Risk Rating
Payment Experience
2.1 Brazil Payment Experience 2013 2014 2015 2016
Germany is the safe haven of Europeiswith its healthy 8
haven of public
Europefinances,
2.2 China
Germany the safe with its 1.5
large current
2.3 France account surpluses, and highly competitive and dynamic
healthy public finances, large current account 6
business sector. German GDP growthandwas weaker than expected in 2014,
% of GDP
surpluses, highly competitive and dynamic
2.4
andGermany
the forecast for this yearbusiness
is a slight deceleration to 1.3 per cent.
sector. German GDP growth was weaker 1.0
%
4
2.5 India than expected in 2014, and the forecast for this
year is a slight deceleration to 1.3%. 2 0.5
2.6 Japan
0 0.0
2.7 Mexico
Medium-Long-Term Commercial
Current Account Balance
2.8 Russia
Commercial Country Ceiling Real GDP Growth
2.9 South Africa Expropriation
Medium-Long Term Transfer and Conversion
Commercial World Bank Governance Indicators
2.10 United Kingdom
Political Violence 100 91
2.11 United States 94 93 92
Commercial Country Ceiling Expropriation
Business confidence and export demand is
3.0 Sector Overviews recovering as the Eurozone crisis wanes.
Transfer and Conversion
4.0 Provincial Overviews High levels of productivity and efficiency may
Political Violence
suffer as German wages are rising faster than 50
those demand
Business confidence and export of the restisofrecovering
the Eurozone, butEurozone
as the it will take
many years for Germany’s huge competitive
crisis wanes. High levels of productivity and efficiency may suffer as
advantage
German wages are rising faster to erode.
than those of the rest of the Eurozone, but
it will take many years for Germany’s huge competitive advantage to 0
erode. Sovereign
Control of
Corruption
Government
effectiveness
Regulatory
Quality
Rule of Law
Sovereign Probability of Default
The percentile rank term ranges from 0 (lowest rank)
to 100 (highest rank).
Germany’s debt as a percentage of GDP remains
high at almost 80%. However, the increase recorded
during the global financial and Euro area debt crises
Public Finances
was lower than that of many other major developed 80
Sovereign market economies, and the trajectory is favourable. 0.6
Furthermore, Germany’s low funding costs will 60
Sovereign Probability of Default
ensure that the debt servicing requirements remain
affordable. Over the long term, solutions to the 0.4
40
Germany’s debt as a percentage of GDP
Eurozone crisis,remains high at almost
such as mutualized 80 per
debt and fiscal
cent. However, the increasetransfers,
recordedallduring
requirethe global tofinancial
Germany and
take on more 0.2 20
Euro area debt crises was lower thanfor
liabilities that of many other
its neighbours to themajor
south.developed
market economies, and the trajectory is favourable. Furthermore, 0.0 0
Germany’s low funding costs will ensure that the debt servicing 2013 2014 2015 2016
requirements remain affordable. Over the long term, solutions to the
Eurozone crisis, such as mutualized debt and fiscal transfers, all require
Fiscal Balance (% of GDP)
Germany to take on more liabilities for its neighbours to the south.
Public Debt (% of GDP)
Sources: EDC Economics, World Bank,
Haver Analytics, EIU
GLOBAL EXPORT FORECAST SPRING 2015 18Economic and Political Intelligence Centre Spring 2015
India RISK Overviews
2.0 COUNTRY
Table of Contents
2.5 India
1.0 GEF Executive Summary
Short-Term CommercialShort-Term Commercial Current Account and Economic
2.0 Country Risk Overviews Growth
Risk Rating Risk Rating
Payment Experience
2.1 Brazil Payment Experience 2013 2014 2015 2016
Inflationary
2.2 China pressures have Inflationary
eased, although sizable
pressures fiscal although
have eased, shortfalls leave
sizable 2
5
little room
2.3 France to stimulate growth. Foreign exchange reserves have
fiscal shortfalls leave little room to stimulate growth.
recovered somewhat, following a period of reserves
investorhaveportfolio
% of GDP
Foreign exchange recovered somewhat,
2.4 Germany Companies servicing legitimate foreign debts should have
rebalancing. 0 0
following a period of investor portfolio rebalancing.
%
little
2.5 difficulty meeting theirCompanies
India obligations. Currency
servicing volatility
legitimate foreignwill
debtspersist
should
through 2015. have little difficulty meeting their obligations. Currency
2.6 Japan -2 -5
volatility will persist through 2015.
2.7 Mexico
Current Account Balance
2.8 Russia Medium-Long-Term Commercial
Real GDP Growth
2.9 South Africa Commercial Country Ceiling
Medium-Long Term Expropriation
Commercial World Bank Governance Indicators
2.10 United Kingdom
Transfer and Conversion 100
Commercial Country Ceiling Political Violence
2.11 United States Expropriation
3.0 Sector Overviews Business investment, including foreign direct
Transfer Overviews
4.0 Provincial and Conversion investment, is expected to Violence
Political rise due to a sense of 53
improved policy decisiveness and fewer policy flip-flops 50 47
on regulatory issues now that the government holds 36 34
Business investment, including foreign direct investment, is expected to a
rise due to a sense of improved policy decisiveness and fewer policy arise
strong majority. Nonetheless, challenges may still
in some
flip-flops on regulatory issues nowsouthern
that the and eastern states.
government holdsPolitical violence
a strong
remains location-centric.
majority. Nonetheless, challenges may still arise in some southern and 0
eastern states. Political violence remains location-centric. Control of
Corruption
Government
effectiveness
Regulatory
Quality
Rule of Law
Sovereign
The percentile rank term ranges from 0 (lowest rank)
Sovereign Probability of Default to 100 (highest rank).
Fiscal consolidation is anticipated in coming years
under Prime Minister Narendra Modi. Debt levels
Public Finances
are much higher for India than for economies with 5 50
Sovereign similar ratings, but the strong medium- to long-term
growth projection will afford the government some
Sovereign Probability of Default
policy space. External sovereign debt obligations are
quite small. 0 0
Fiscal consolidation is anticipated in coming years under Prime Minister
Narendra Modi. Debt levels are much higher for India than for
economies with similar ratings, but the strong medium- to long-term
growth projection will afford the government some policy space. -5 -50
External sovereign debt obligations are quite small. 2013 2014 2015 2016
Fiscal Balance (% of GDP)
Public Debt (% of GDP)
Sources: EDC Economics, World Bank,
Haver Analytics, EIU
GLOBAL EXPORT FORECAST SPRING 2015 19You can also read


