History Report CONSUMERS CREDIT UNION
←
→
Page content transcription
If your browser does not render page correctly, please read the page content below
CONSUMERS CREDIT UNION
History Report
Table of Contents
I. Seventy-Five Years of Service ........................................................................................... 1
		       It All Began With Milk Prices ......................................................................................... 1
		       A Co-op Is Born ............................................................................................................... 2

II. The 1930s: The Depression Years ..................................................................................... 3
		        First Annual Meeting ...................................................................................................... 4
		        Charter Member of the Illinois League .......................................................................... 4
		        Members Rebate Five Cents on Dividend ...................................................................... 4

III. The 1940s: The War Years and Their Aftermath ............................................................. 5
		         Joining the War Effort .................................................................................................... 5
		         War Brings Credit Union to Standstill ........................................................................... 5
		         After 18 Years, Key Man Resigns from Board ............................................................... 7

IV. The 1950s: At Ease with Eisenhower ................................................................................ 8
		        A Stronger Position in the Community ......................................................................... 8
		        Credit Union Marks 25 Years of Progress ..................................................................... 9
		        Credit Union Buys Land for Office .............................................................................. 10

V. The 1960s: Vietnam and Violence .................................................................................. 11
		       Resolving the Space Problem ....................................................................................... 11
		       Members Change Credit Union’s Name ....................................................................... 12
		                   One of the State’s Finest ............................................................................................... 13

VI. The 1970s: Bring Major Change ...................................................................................... 16
		        One of the First to Qualify for Federal Insurance ....................................................... 16
		        A Master Plan for Growth ............................................................................................. 17
		        Sixteen Hundred at Grand Opening ............................................................................ 19

VII. The 1980s: Selling the Credit Union to the Me-Generation ......................................... 22
		         Credit Union Becomes State-of-the-Art ....................................................................... 22
		         Credit Union Drops NCUSIF for Private Insurer ........................................................ 23
		         Positioned for Further Growth ..................................................................................... 25

VIII.
  The 1990s: Increasing Delivery Channels While Using Technology and
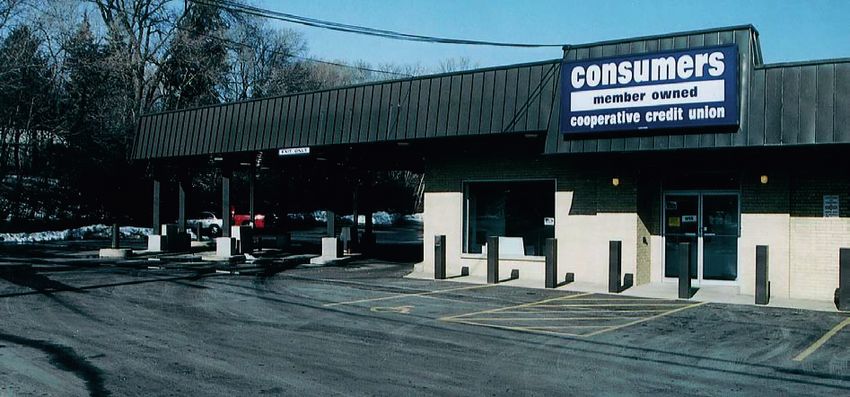
  Staff Training to Deliver Quality Service to Our Members ........................................... 28
         Technology Enhancements .......................................................................................... 29
		       New Delivery Channels ................................................................................................. 31
		       Addition of New Products and Services ...................................................................... 32
         Branch Development ................ ………………..………………………………………….. 33
         Staff Training ............................ ………………..………………………………………….. 34
         Regulatory ................................. ………………..………………………………………….. 35
         In Memoriam ............................ ………………..………………………………………….. 36
         The Decade by the Numbers .... ………………..………………………………………….. 37
         Milestones of the Decade .......... ………………..………………………………………….. 38
IX.
  The 2000s: A Decade of Challenges, Changes and Progress.......................................... 39
        Leadership Changes and Expansion............................................................................. 41
		Physical Growth and Expansion................................................................................... 43
		      Technology and Security Enhancements..................................................................... 44
		      Expansion of Products and Services............................................................................. 45
		      Leveraging CCCU’s Unique Charter.............................................................................. 46
		      The Decade by the Numbers......................................................................................... 48
		      Milestones of the Decade............................................................................................... 49
		      Awards and Recognition................................................................................................ 50

X. 2010 - 2019: Emerging from the Great Recession – Stronger than Ever!..................... 51
		        Risk Management and the Regulatory Environment.................................................. 53
          The Role of Innovation.................................................................................................. 54
          Centralization of Administrative Staff.......................................................................... 56
          Lending Growth............................................................................................................. 57
          Out of market Member growth..... ………………………………………………………….58
          Mergers and the Continued Expansion of our Local Footprint................ ……………59
          Expansion of Financial Advisor services....... ……………………………………………..61
          The Decade by the Numbers... ………………………………………………………………63
          Milestones of the Decade.. ……………………………………………………………………64
          Awards and Recognition.. ………………………………..…………………………………..65
With special thanks to all subsequent
contributors to this document
RS COOPE
                              ME        R

                             SU

                                                    AT
                          CON

                                                      IVE
                                             TH

                                  1930       2020

                             CR
                                  EDI               N
                                         T U NIO

More than 90 years of service

                                                        1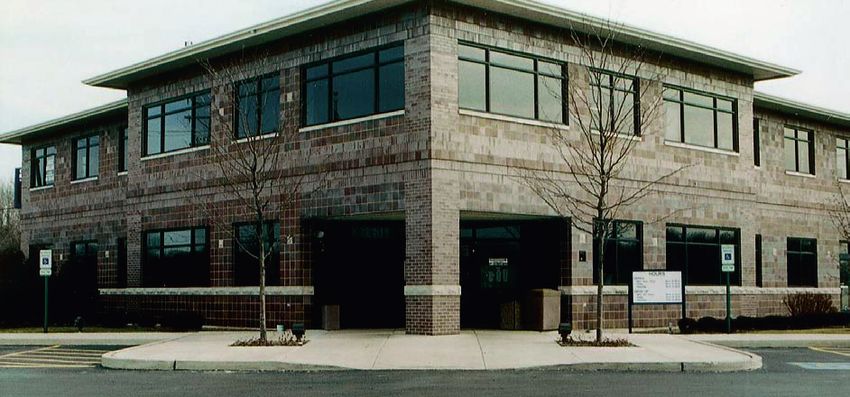
2
3
4
5
6
7
8
9
10
11
12
13
14
15
22
16
17
18
19
20
21
22
23
24
25
26
27
The 1990s: Increasing Delivery Channels While
Using Technology and Staff Training to Deliver
Quality Service to Our Members
If ever it could be said that one time period method of communication called email.
set the
The table The
1990s: for another,
Oklahoma that statement would This less formal (andgrowth.
much faster) meansand
Assets of
surely apply to the
City Bombing, April 19, last decade of the 20th communication rapidly became the option of
share/savings growth
century. There were a series of significant trends choice for many.
1995; Operation Desert are projected to be in the
that started in 1990 and continued up until the
Storm Begins, January 29, Desktop workstations, range of 6%
email to 8%. and
messaging We
very last day of 1999. Those trends include
1991; The Internet
innovation Comes
through technology, an expanded rudimentary websiteswill
werecontinue to devote
just the beginning.
of Age.of products and services combined with
menu a great deal
By the mid-90s, technology of effort
allowed to
work
new channels to deliver them, groups to share applications
improving service and building and
1990
all while doubling the number ideas, fueling
business a burst in with
relationships creativity
our
Income
of physicaland membership
branches – then tying growth and efficiency. Websites
members. We believe there is amorphed
were robust
everything and the
together withCash Station
a series from electronic brochures to
great deal of potential for growth
of training programs for your e-commerce sites, allowing
ATM Network was made available within our family of 33,763 mem-
team. business to be conducted over the
to our Members bers and we intend to leading
Internet, pursue to
thatanpotential.”
increase in
That’s the story of Consumers the “reach” for companies with
The credit unionCredit
Cooperative added 1,493
Unionnew members 1991 the vision to invest in this new
in
(CCCU) during the 90s. membership
1990 bringing the total Let’s count Assets wenttechnology.
over the $100 million mark,
to 33,763.
begin … The return on assets for the year we opened our second branch office, and
amounted to 1.1% which was excellent and it “Operation With such huge advances in
Grassroots” triumphed over
The pace of change technology came equally huge
helped reserves grow by 19.14%. Although the Banking Lobby
during the decade moved concerns about issues such as
savings growth was below the 7% goal for
at unprecedented levels privacy and data security. In truth, each
the year,
– as sharetosavings
seems be thestill increased by $4.6 The Annual Membershipwas
new advancement Meeting was held
accompanied by
million or 6.1%. This
case throughout mostfueled growth of $5.6 on March 11, 1992 and the Annual Report
an increase in potential vulnerability.
million
of our in assets.Perhaps
history. stated that
Such“1991 was acast
concerns verya good
large year for
shadow
the most significant our credit union.” Growth in share/savings
over the financial services industry,
The Waukegan
change was the office was refurbished for the
Internet, amounted to $12.2
causing CCCUmillion or a15.1%.
to take prudentThis
“go
first
whichtime since
grew it opened
from in 1975.
a mysterious In primarily
tool June the slow” approach that allowed for
drove assets up by a whopping 15.22%! Un- progress
used by government and military
credit union joined the Cash Station ATM agencies, while always
fortunately, thekeeping the Confidence
Consumer well-being of our
Index
technology enthusiasts
(Automated and thenetwork.
Teller Machine) few among Thisus Membership
started in mind.
the year at a low level and trended
who effectively work in a DOS environment
greatly expanded our service capability over down
As thefrom
decade there. This negatively
progressed, impacted
perhaps the largest
into THE dominant force for businesses.
the proprietary ATM network we had been loan growth holding it to just $2.3
concern was preparing for “Y2K,” with the million or
operating.
That growth Members
began inwere no longer
the early yearslimited
of the 3.8%.
fear theHowever, loan delinquency
world’s computer systems mightwascome
held
to doingasbusiness
decade, graphicalat theinterfaces
user credit unionʼs two
and desktop in check and
crashing down loans charged
as we moved offinto
amounted
the newto
ATMs. They were now able to transact busi-
computing became affordable. Access to this just .18% of total year end loans, which was
millennium. As with responsible organizations
ness at any Cash
wonderful new Station ATM. to virtually
tool expanded everywhere,
excellent by CCCU
industrytook several precautions
standards. These two
every workplace as companies both large and throughout the decade to assure
factors helped us maintain asset quality we were as
at
small created
During their first
his report to websites.
the members Chair- prepared as possible for potential
a very high level. Dividends and expenses challenges.
man Ray DeWeerth read the These precautions were reflected in staff
By the end of the decade, thefollowing quote
days of written from operations increased but the low level
training, including creating and continuously
about
letters,the coming
memos andyear from the reports
white-paper Annualwere
Re- of provision for loan loss expense enabled
updating business continuity and disaster
port: “We look to 1991 as a year of
rapidly disappearing, replaced by a new controlled the creditplans.
recovery union to post a 1% return on assets.
28In addition to the challenges, our brave new Technology Enhancements
world also created an exciting platform Technology was clearly one of the driving
on which the credit union could expand forces of the decade, commanding an ever-
our products and services. Technology increasing role in the way CCCU delivered our
enhancements allowed us to introduce the first products and services to Members. Along the
remote additions to our delivery channels that way, there were a series of technology events
expanded how and from where Members could critical to the credit union’s continued success.
access their money and conduct transactions.
Technology also provided the means that The first enhancements of the decade began
would ultimately allow us to better leverage in 1990 when we automated loan documents,
our unique Associational charter. moving to system-generated documents rather
than manually preparing and typing each one.
The combination of new technology, new This new process both increased efficiency and
products and services, and new delivery reduced errors, while Members enjoyed the
channels combined to set the tone for yet benefit of faster turnaround and approval times
another important trend in the evolution of on their loan applications.
Consumers Cooperative Credit Union: the 90s
saw ourMallard
first meaningful branch
Creek Shopping expansion.
Center In in Round
Branch opened In Lake
1992,Beach
the incredit
1991 union installed a new
addition to using technology to expand remote mainframe computing system while also
As a result,
access reserves
to services, we increased
also doubledfrom
our6.95%
numberin ated in 1990
updating grew tosuch
peripherals 70,000 transactions
as desktop per
terminals
1990 to 7.01% at the end of 1991. This
of physical locations during the 90s from two was month. The strong growth in assets
and printers. These enhancements to our and trans-
quite
to fourgood
whileconsidering
making plansthe strong growth
for even in
more actions heightened
“core” data processing managementʼs
system provided focus on
several
assets
branchesforinthe
theyear. Membership
decade to follow. growth was training
importantinbenefits.
order toFirst,
prepare
the our
newstaff to pro-
technology
very good with 1,321 new members opening vide courteous,
broadened CCU’s personable, and efficient
ability to serve ser-
our current
Exciting new technology. Rapidly expanding business lines. Second, the technology was
accounts, which brought total membership vice. This training initiative began in 1988
products and services. New delivery channels. scalable, meaning
up to 35,084.
An educated and well-trained staff. New
and has helped the it had
staff the solid
make capability
progressto
expand
on as we continued
our mission to providetoourgrow. This with
members one-
physical locations. All interrelated, all two combination provided the third benefit:
On October 1,
contributing to 1991,
CCCU’s thegrowth.
credit union opened Quality Service.
the ability to improve service to our Members.
a second full service branch office in the Mal-
The Creek
results:Shopping
assets grew by 280% duringLake
the Most importantly, the new system was installed
lard Center in Round The Banking
without a hitch!lobby sought to combine the
decade, loans increased 311% and we added
Beach located near the intersection of Rollins NCUSIF (National Credit Union Share In-
more than 10,000 new Members. Add it all up
Road and Route 83. Our first branch opened surance
The centralFund) with the
processing unitFDIC
(CPU) (Federal De-
for the core
and you have the 90s! systemInsurance
was subsequently updated in would
1995,
in Mundelein on February 1, 1984 at the posit Corporation). This
same
On thetime thethat
pages Mundelein Community
follow, we’ll Credit
explore each of again forced
have without any unions
credit negativeto impact
write offonthe
either
1%
Union merged with CCCU. When the Round
these trends in more detail, as follows: staff or Members. This upgrade
deposit they made to fund the NCUSIF and provided the
additional horsepower required to meet the
Lake Beach office opened, we had about sacrifice the independence we had enjoyed
• Technology Enhancements demands of our technology plan through the
5,000 members within a seven mile radius. by having the National Credit Union Asso-
end of the decade.
• Expansion
Business wasofbrisk
Delivery
at theChannels
new office with 100 ciation (NCUA) as an independent regulator
new members
• Addition joining
of New the and
Products credit union each
Services for credit
In the unions.
same year, Seven membersour
we upgraded from our
VISA
month during the first three months of opera- credit card processor to TeleCredit.
credit union traveled to Washington, D.C. TeleCredit
• Branch Development
tion. provided
in Februarytheto show
dual support
benefits forof “Operation
improved
• Staff Training administration of rally
our credit card program while
Grassroots” and for the continued inde-
• Regulatory laying the foundation for future enhancements
We launched and
a newOther
autoConsiderations
buying service with pendence of credit unions. They joined more
to our VISA program.
the
• The National Buyers
Decade by Federation (NBF) to
the Numbers than 15,000 members that had descended on
help membersof purchase
• Milestones the Decadenew cars and trucks the
We capitol, from every
took another big stepstate in theinunion,
forward 1993
for $100 over invoice. Transaction volume to petition
when for our cause.
we automated In addition,
currency processingmanyin
We hope you
continued enjoy the
to grow 90s as
rapidly much astotal
boosting we of our members and those from other credit
Waukegan. Members enjoyed the positive
enjoyed them!
teller assisted transactions to 1.9 million for impact on
unions our personal
wrote busiest branch
appeals through reduced
to their legis-
the year. The Cash Station ATM service initi- wait-times while the credit union
lators to “vote no” on the issue of combin- benefited
from increased accuracy and efficiency. This
29ing our share insurance fund and regulator. 37,807.
the abilityThe return on assets
to “network” was
personal 1.40%, far
computers in
At the end of the day, our grassroots move- better than our goal
key departments, of 1.10%.
a solution Thisdeployed
that was enabled
ment was victorious. Just as important, credit in to
us 1996 and expanded
aggressively in reserves,
increase 1997. This was
thereby,
unions learned to be ever vigilant and pre- another big
making the step forward
credit union and
saferonce
and again, this
more sol-
pared to take on the banking lobby whenever enhancement
vent than ever!”led to improved service for our
Members by improving communication from
the interests of members are threatened.
between departments.
The growth of $119.6 million or 18.6% drove
1992 assets
One oftothea new
most record high.technology
significant Just as impres-
events
Former CCCU Treasurer/Manager, An- sive, asset quality improved over the previ-
of the decade occurred in September 1995 when
thony (Tony) Pierce passed away on Feb- ous year. Forand
we updated example, the credit
tested our unionʼs
Disaster past
Recovery
ruary 22, 1992 at the age of 82. Tony was Plan. For the first time, we moved from
due loans amounted to just .24% (less than an IT/a
Treasurer/Manager of the credit union computer system strategy to an enterprise-wide
quarter of one percent) of total loans, which
from 1956 to 1971. Under his leadership, approach;
was a more
excellent comprehensive
by industry testing plan
standards.
that contemplated potential issues throughout
CCCU grew from $1.7 million in assets to
the credit union. Updates and testing continued
$5.4 million; membership increased from Transaction volumes grew rapidly. Teller
annually through the remainder of the decade.
4,715 to 8,073. Tony dedicated much of assisted transactions ended the year at 2.2
his life to the cooperative movement and million. A total
The “trigger” forofthis
$79.5
newmillion flowed
approach was into
the
the principle
automation of “people
would helping
ultimately spreadpeople.”
to our highly anticipated (and much feared) “Y2K”
memberʼs accounts via direct deposit and an-
With his passing CCCU and the credit
Mundelein location and all future CCCU event $26.6
other on January
million 1, 2000.
came One payroll
in from benefit de-
of
branches.
union movement lost a stalwart friend and the Y2K concern was realized when
duction transactions. We completed 794,253 CCCU
developed and implemented a formal
advocate.
Staff received another great new tool in 1994 ATM transactions and our automated phone
strategy for Technology planning. The plan,
when we purchased our first access service (PAM) successfully processed
introduced in November 1997,
digital telephone system. It took 328,375 calls. outlined future technology
eight months to research and needs while providing
identify the preferred system, The credit union negotiated
guidance the purchase
for both technologyof
which then came online in a 3 acre site at the cornerand
governance of Route 83 and
management
January 1995. The system Monaville Road in Round
decisions. Lake
The newBeach. This
plan helped
improved communication site would ultimately
assure replace our branch
technology in
projects
capabilities between offices and purchases aligned
the Mallard Creek Shopping Center. with
and our growing lending our vision and mission while
departments. The new system supporting the credit union’s
also included CCCU’s very first
Effective September 1, 1992, members be-
enterprise-wide strategic plan.
voicemail capability, making it gan to benefit from higher dividend pay-
well worth the wait! For the first time, CCU ments. This came
Naturally, Y2K about when thetechnology
dominated board ap-
Members could now apply for a loan from any proved
initiativesmanagementʼs recommendation
through the remainder to
of the decade.
touch-tone phone – 24 hours a day, 7 days a convert to a daily calculation
CCCU recognized the need tofor dividends
upgrade our
week, 365 days a year (24/7/365). from a quarterly
technology method.
leadership We negotiated
to manage an
the process,
adding an Information
agreement that allowed Systems
all of ourManager
members in
As lending efforts continued to grow, there 1997. In addition to our internal systems, we
to join SAMʼS CLUB. Plans were also final-
arose a need for powerful loan processing expanded our financial
due-diligence to include
software to handle the increased volume. We ized for a new planning service. key
To
vendors to assure Members would not be
Tony
laid thePierce
foundation for that in 1995 by creating that end a contract was signed with the PLAN
impacted because of failures on their part.
the plan for our first wide area network (WAN). AMERICA investment service with a sched-
At the Annual
Installation ofMembership
the WAN was meeting on March
completed in uled commencement
In 1998, CCCU President in either the second
Bill Reidel or
appointed
10,
March19931996.
Board Chairmanwith
Combined Ray our
DeWeerth re-
new loan third
a Y2K quarter of 1993.to begin assessing and
Committee
ported “1992system,
origination was anloan
extremely strongcould
processing year be
of working on
The Annual Reportissues of concern.
ended Committee
by indicating the
completed
growth for four times faster
our credit union.than evergrew
Assets before.
at a members were Kevin Mayers,
main marketing focus for the coming Operations
year
record pace. We added 2,723 new members VP andbecommittee
would to increasechairman;
our loan Jim Benlein,
portfolio by
Combined with the increased power from our Information Systems Manager; and John
during the
CPU upgradeyear,
in bringing
1995, thetotal
WAN membership to
also provided 15% or greater. Considerable time was also
Pawlowski, VP of Finance. Leaving no stone
30to be spentthe
unturned, oncredit
packaging
union services to increase
also contracted with Department
Our first majorof Financial
step forwardInstitutions on our
was joining the
the number and
McGladrey of services per member.
Pullen 1998. Their roleSystem
was to examination
Cash Station ATMfor the year. in
network A June
drive1990.
up ATM
This
audit our Y2K
processing plan, provide
functions were tofeedback and to
be scrutinized greatly
was expanded
installed ourMundelein
at our service capability
office. over
The
offerimproved
and additional with
suggestions
two mainto our committee.
objectives in the internal system we had been operating.
agreement signed the prior year for the Plan
mind: 1) Improve service to members 2) Members Financial
America were no Planning
longer limited
servicetocame
doing
to
This approach provided significant peace of business at the credit union’s two ATMs: they
Initiate a trend tothecutorganization,
mind throughout operations expenses
from the fruition in June when we began offering this
were now able to transact business at any
through efficiency and increased
boardroom to the front lines and everywhereproductiv- service to members. By now staff training
Cash Station ATM, regardless of where it was
ity. The final
in between. Thesentence
planning inandthe 1992 Annual
preparation paid had become an integral part of operations, so
located.
Report stated: “In 1993 we pledge to work
off too: Consumers Cooperative Credit Union much so, that it had become pivotal to help-
even
enjoyedharder to serve
a smooth you wellfrom
transition so that we can
December ing the staff
By 1992, stay onwere
Members trackclearly
in the embracing
pursuit of
31, 1999 to January 1, 2000
continue to earn your support.” with no negative CCCUʼs mission to deliver Qualityfinancial
the idea of self-service with their Service
impact from Y2K. transactions.
to our members.That year alone, CCCU
1993 completed 794,253 ATM transactions.
In summary, the decade from 1990 to 1999 Additionally, Members used our automated
“We aremost
saw the happy to report
significant that 1993
increases in the was
use A strategic planning session was conducted
phone access service (PAM) to check account
our thirteenth consecutive year of asset
of technology in the credit union’s first 70 by Koch McNabb Resources on October 9th
information 328,375 times.
growth.
years. OurSince 1980 assets
measured, haveapproach
thoughtful grown byto and 10th. The goals that came out of this
$117.9
adding million or 939%!”
new systems and solutions created a session for 1994
We further were: 1)
expanded ATMGaincapabilities
15% in loans in
foundation for progress throughout the credit 1993 when we opened a drive-through ATM
2) Plan and implement a service pricing pro- in
union – was
Growth a foundation that will
strong in 1993. be explored
Assets grew by Mundelein,
gram offering
predicated Members
on service the convenience
relationships with
further on the pages that follow.
$10.8 million to at an all time high of $130.4 of 24/7/365 access to their
our members 3) Established that moneyouratsingle
that
location. Later that year, we won the bid to
million. Savings
New Delivery growth slowed from the
Channels best strategy for the future is to focus on re-
install an ATM in the lobby of the Lake County
previous year but still increased by $9 mil- tail lending as a means for increasing loan
The continuous upgrade of CCCU’s Court House, completing installation on
lion. A strong
technology return onprovided
capabilities assets of the
1.28% en-
perfect business.
December 17, 1993. In addition to providing
abled the Board
opportunities to toexpand
increasehowreserves by 18%,
we delivered better Member service, these moves also
which brought the ratio of reserves
our products and services. Prior to 1990, to assets
our Bill Reidel
attracted newclosed
incomeoutfrom
his report at the annual
non-Members who
to 7.92%.channels”
“delivery Loan growth exceeded
were limited: the 15%
coming into meeting by stating:
utilized these “Our mission is to deliver
two locations. 1
goal withwhere
an office a gainyouof could
16.5%see ora$11.6
teller,million.
use our Quality Service to our members. We appreci-
Consumer
proprietary loans posted the
“QuikStop” majority of
Automated the
Teller Thethe
ate previous
hard work section touched on
our employees putCCCU’s
forth to
Machine (ATM) or the drive through. “Remote new phone system, installed in January 1995.
gain followed by mortgage loans and VISA. translate this mission into reality. On behalf
channels” meant conducting transactions by In April of that year, we introduced “Touch
of the Board of Directors, Staff, and Manage-
Tone Loan Express,” giving Members the
mail ordelinquency
Loan direct deposit,declined
where available
to .14%from an
from ment we thank all offorour members forphone
their
employer. That was about to change in a big opportunity to apply loans over the
.24%. This helped reduce the ratio of loans business and support.”
anytime from anywhere, thus adding telephone
way during the decade of the 90s.
charged off to just .12% of total loans, which access as another new delivery channel. That
was 4 times better than the .50% the credit channel was strengthened even further when
union industry considered to be good. Con- 1994
we launched “Loan Line 24” in 1997, giving
sequently, asset quality remained very high “By the end
applicants of 1994 assets
the opportunity to talk climbed to
with a loan
further bolstering the safety and soundness of counselor
$136.4 anytime
Million. theyinapplied
Never forfive
our sixty a loan,
year
the credit union. CCCU signed up 1,536 new 24 /7/365.
history have we been better prepared to
members for the year elevating total mem- meet
CCCUtheprovided
challenges of thenew
another future.”
channel for
bership to 39,343. The above quote from the
Members looking for an auto loan1994 Annual
when Re-we
port was supported
introduced by the lending
a local indirect fact thatprogram
CCCU
Several accomplishments were listed in the had
withincreased assets in
area dealers for 1996.
14 consecutive years.
This program
Annual Report for 1993. CCCU won the bid Our competent
allowed Members friendly staff, efficient
(and prospective deliv-
Members)
to install an ATM in the lobby of the Lake to begin the loan application process
ery systems, and well placed branch office while
County Court House. Installation occurred at the dealer. This added convenience
network were providing real value to our for
on December 17th. The credit union received Members resulted
members in an additional
and driving the credit$2.6 Million
union for-
in auto loan volume for CCCU.
the highest composite rating possible from the ward in the process.
1
Note: in 1996, CCCU discontinued adding a surcharge to ATM transactions.
2
Beta-testing for Automated Bill Pay was completed in 1999, with the service first offered to Members in 2000.
31Although growth in new
The most significant share/savings and assets
delivery channel was members
In 1992, and the work space
credit for staff
union within the
negotiated an
came
createdininunder
1999 goal,
when loan
CCCU growth surpassed
introduced our Mortgage
agreement andwithVISA
Sam’sDepartments. In addi-
Club so all Members
first online banking solution. Originally
the 15% goal with an increase of 16.2% for known couldthejoin
tion, Sam’s
lower levelClub
of theinWaukegan
Gurnee. office
This
as “Home
the Banking,”
year. Since this bold were
share deposits step was
not taken
suffi- represented
was a two-fold
refurbished savings
to improve thetoappearance
Members,
on August 9, 1999 – nearly five months
cient to fully support the heavy loan demand, before first on the Sam’s Club
of the loan department. membership fee, then
the calendar turned to 2000. Home Banking by providing a low-price shopping option for
the investment portfolio had to fund most of
included an option for automated bill pay, a all CCCU Members. Both Sam’s Club and
the growth. This ultimately caused invest-
wonderful convenience for Members opting NBF are examples of helping Members by
ments
for thistofeature.
decline by 16% with the result that A $5 monthly
offering service fee (a
new non-traditional goal from the
services.
this money now resided in the loan portfolio. previous year) was implemented. This fee
Interestingly,
This shift in theHome
mixBanking
of assetsand automated
from invest- was put inunion
The credit placetook
to reduce
another thebold
expenses asso-
step forward
bill pay 2
were added while many
ments to loans would have positive implica- financial in June 1993 when we added Plan America,
ciated with providing check cashing services our
institutions
tions wereincome,
for future paralyzed duebytothethespecter of
superior first investment service, in cooperation
for members who did not use the other ser- with
Y2K. loans
yield If there wasover
have any doubt
that ofabout the wisdom
investments. CUNA
vices theMutual Insurance
credit union had toGroup. Thepolicy
offer. The Plan
of that decision, CCCU Members and staff America program was offered exclusively and
that defined the parameters for this fee pro-
proved we were ready for the challenge: by the at no cost to CCCU Members; a key strategy
The
end ofpercentage of reportable
the year, 1,451 Membersdelinquency to
were enrolled
vided a broad range of services that enabled
to help them effectively plan and manage their
total
in theloans
newincreased slightly
services and from29,464
another the previous
made the vast financial
personal majority goals.
of members to ultimately
The program was so
year, however, loan charge
inquiries about them. WOW! offs declined. This avoid
well received by Members thatpolicy
the fee altogether. The CCCUstatedwas
signified that the quality of the credit unionʼs members
recognizedwho satisfied
as one anyperforming
of the top one of thecredit
fol-
By the
assets wasend
veryof theIndecade,
high. CCCU towas
fact, the Report the lowing
unions for criteria
Plan would
America notbybethe charged the fee:
end of 1994.
transformed from an “on-site”
Members stated: “It is remarkable indeed financial
that an active checking account, or an aggregate
institution to one committed to offering our By the mid-90s, mortgage originations had
we have managed to increase our loan portfo- average daily minimum balance of $500 on
products and services to Members in as many become an increasingly important part of our
lio by $31.1 million the past three years and deposit, or an active VISA account, or a loan.
ways and through as many different delivery loan portfolio. To help increase mortgage
still maintain
channels as superlative
possible. delinquency
By leveragingand loan
new Members
options, we 22added
years of
ourage or 3-year
first younger, or 65 or
Adjustable
charge off statistics. Industry standards
capabilities provided by improved technology indi- older
Rate were exempted
Mortgage (ARM) frominthe fee. We
1994. Overalsothe
cate that a ratiocombined
and telephony, of .25% of netbuilding
with loans charged
on our years the monthly service fee
lowered down payment requirements from 20%proved effec-
off to total loans
relationships with isMembers
excellent.andOur ratioauto
local of tive
to 10%at reducing
to broaden expenses
the reach andofincreasing
our program. the
.07%
dealers,forthe
1994 wasunion
credit 3.5 times
wasbetter.”
ready to plunge use
Thatofsameservices.
year, we received approval from
into the new millennium. our state regulator to increase our maximum
During the year the credit union implemented mortgage amount from $200,000 to $300,000.
Addition of New Products and Services Finally, our unionʼs
increasedprimary
focus ongoals
mortgages was
the required provisions of the Truth In Sav- The credit for 1995
The Act
ings advances
in order in totechnology plus multiple
be in compliance by the supported
were: by the build-out
1) increase loans by of 10%
the lower level of
2) increase
new delivery channels positioned CCCU to the Mundelein office in 1995, allowing for an
effective date of January 1, 1995. A state of savings by 8% 3) earn a return on assets
increase the value of Membership further increase in both staff to effectively manage the
the art digital phone system was installed that (ROA) of 1% or greater. The Annual Report
than ever. The perfect complement to those increased mortgage volume.
tied all ofwould
advances our offices together for
be the expansion thecredit
of the first closed out by stating: “There is no question
time. We received 31 complementary
union’s menu of products and services; the 90s letters that a strong
In 1995, capital
we added position enhances
the SCORECARD the
rewards
from members
saw several whoadditions.
timely felt the staff had delivered solvency of the credit union. However, your
option to CCCU’s VISA credit card portfolio,
on our mission to provide them with Quality with the
board of reward points
directors and redeemable
managementforrealize
both
Towards This
Service. that end,
was awetestimonial
looked fortoinnovative
the com- merchandise and travel. This new feature
that financial strength is also related to such
new ways to increase the value.
mitment management had made to continue In fact, the helped us
factors ascompete on a level
the quality playing
of assets, field with
managerial
decade’s first new service was National Buyers much larger credit card issuers and quickly
training staff on sound methods for providing competence, and future earnings...”
Federation (NBF), an automobile purchasing became a hit with our Members.
personal service. During the year, loan deci-
cooperative added in 1991. This service helped
sion making was centralized
remove the stigma of “haggling” at the
for Waukegan
a fair price 1995
The credit union added Money Market
office to enable more
for automobiles. rapid decisions
Instead, CCCU Membersto occur We exceeded
Accounts as a our
new loan andoption
savings savings goals
in 1996.
for
wereloan requests.
assured the price they paid for new cars Members quickly embraced them: our Money
and finished the year with a strong 1.02%
and trucks would be no more than $100.00 Market on
return Account
assets. balances grew by $13.7
The
over lower
invoice.level of theprogram
The NBF Mundelein
helpedbranch
drive Million in the first year alone. The next year,
we introduced three new certificate of deposit
office was remodeled to improve service tofor
loan volume during a very challenging year Assets grew by $12.5 million to end the year
the U.S. economy. (CD) products of 15, 30 and 45 months,
32at $152 million.
respectively. TheseMortgage
new CDsloans, including
also turned out the
We year was a good
accomplished thatone because
objective in our
1993mem-
with
first
to bemortgages,
quite popularsecond
andmortgages,
grew by $8.2andmillion
home bers trusted us
the purchase with attheir
of land the business
corner of and gave
IL HWY
by yearloans
equity end. grew by 17.3% or $6.5 million. 83 their
us and Monaville Rd in
support. With thatRound Lake
in mind, weBeach,
intend
The increase in first mortgage loans alone where we would ultimately build our
to follow our mission of delivering Quality new
Over the next few years, we enhanced our facility. We took a “go-slow” approach from
amounted
Share Draft to 83% of the total
(checking) loan gain
Accounts, as inwell.
the Service to our members in the pursuit of our
the time we acquired the land until we began
mortgage sector.our Total
We introduced loans increased
first Overdraft Protectionby goals in 1996.”
construction, as our goal was to add 5,000 new
$11.4 million. Investments increased
option in 1997, providing a safety net and by $4.2
Members in the greater Round Lake area by
million. The surplus
peace of mind for thosethat flowedelecting
Members to invest-
the 1996
the time we opened the new office.
ments was due to the robust growth in shares/
feature. In April 1999, we issued our first Debit “Our financial strength, experienced man-
savings of 11.4%.yet another way for Members
Cards, providing agement, andnew
Plans for the thelocation
sound policy decisions of
were completed in
to access funds from their checking accounts. in 1996 and we broke ground for our beautiful
our Board of Directors have positioned us
Loan delinquency and loans charged off in- new Round
well for theLake Beach branch
competitive the following
challenges that lie
Branch Development year. CCCU President Bill Reidel served as
creased. Even though our statistics in these ahead.” (quote from 1996 Annual Report)
The 90s were clearly a dynamic time at general contractor during the construction
areas remained superior to the averages for
CCCU: exciting new technology, a significant phase, working hand-in-hand with the Hezner
credit unions nationally, these increases did The credit union learned long ago that meet-
Corporation, the project architect, and Larry
expansion of delivery channels, and innovative
impact net earnings.
new products Asset
and services qualitytoremained
designed increase ing
May,future challenges
the head depended
of Kimbar, upon good
Incorporated, our
very
the value of Membership. In order To
high despite these increases. para-
to better planning, followed up by the
construction management firm. solid execution
phrase the Annual
serve Members Report:
during thisEven withofthe
period in-
rapid of objectives. During 1996 CCCU did a good
crease,
growth,our ratio of
the credit loans
union alsocharged
made aoff to total
significant The meeting
job target forobjectives
completionandof the newestablished
goals office was
loans ended 1995
commitment to ouratbranch
just .11%. That is super-
network. during the prior year. For example, when
January 1998 – a target that was met the
the goals
branch officially opened on January 11th of
lative performance considering .25% is con- for growth in share/savings, loans, return on
The first investment came in 1990 when we that year. This new facility would become our
sidered excellent by the credit union industry. assets and asset growth were surpassed. In
remodeled the Washington Street office in largest physical office, with a full-service lobby,
Waukegan. This important investment was addition, assets ended
several drive-up the year
lanes and at an allATM.
a drive-up time
The Listsince
the first of Accomplishments
we moved into that for 1995
office ap-
in May high of $168.8
The initial million,
build-out alsomarking
includedsixteen years
office space
peared at the end of the Report to the
1975. After 15 years, the makeover helped us Mem- of consecutive growth.
and an employee break room in the lower level,
bers.
better Some
serve ofthethe notable
rapidly accomplishments
growing transaction while providing for future expansion with an
for the year were: 1)
volume at that location. the credit union earned a The Annual5,000
additional Report stated:
square “Strong
feet share/sav-
available on the
return on assets of 1.02% which enabled the ings
uppergrowth
level ofpushed assets up by $16.5 mil-
the building.
CCCU expanded our branch footprint in
Board to increase reserves by $1,556,884 2) lion or 10.9%. Loan growth led all other as-
October 1991 when we opened a second full-
the ratio of operating expenses to gross income set categories. Our successful performance in
service branch in the Mallard Creek Shopping
was reduced
Center 3) earned
in Round Lake the highest
Beach. rating
While pos-
opening the area of lending will enable us to continue
sible on our examination by the Department
a branch in a strip center was new territory, it paying competitive rates on savings, thereby,
of
wasFinancial Institutions
always meant to be a4)temporary
Developedsolution
a plan enhancing our potential for future growth.”
to launch
until Money
we could Market
identify Accounts the
a permanent next
location
year 5) enhanced
in western our VISA
Lake County, IL,service
even asbyweadding
were Money Market accounts were introduced in
SCORECARD which would
growing new Members in that allow
area. members 1996. By the end of the year the collective
to earn points toward travel and merchan- balance LakeinBeach these accounts
opened inhad grown 1998to $13.7
Round Lake Beach Branch opened in January 1998
Round Branch January
during the past two years we have loaned to open a branch office on this site in 2002.
dise awards 6) increased our business hours outmillion.
$142.7 million Certificates
in new money, for a netof deposit
Management and also grew
the Board felt anrap-
office at
7) received approval from the School Board On
increase December
in our loan portfolio of2, 1996,
$43.1 mil-
idly and combined with the growth in money
lion.”
CCCU
this locationopened
tion load off
would take some
of the
another
Washington
of the transac-
Street office,
unique branch at Adlai E.
which Stevenson
would then enable that officeHighto bring
of Adlai Stevenson High School to open a market
The accounts
credit union signed up 2,567 newpushed
mem- aggregate
new members on board share/sav-
more effectively.
School
bers, bringing theintotal Lincolnshire,
membership count IL.
Once Stevenson
in operation, High
the new office would posi-
branch office in the school. toings
41,487. up
School
referrals
Many by
employeeshad
11%
new members
a when
asked for
or
came
student
$15.2
from
dealing
million.
tion the
population
credit union to better
of 3,300
on the north side of Waukegan
serve members
at
and northward.
with current members. However, the major- In addition, future growth would be enhanced
the time, along with an onaddition
ity of new members were referred through the north side of350 faculty,
Waukegan, Beach Park
The Annual Report for 1995 ended by stat- Loans grew by 14.7%
our indirect lending program with automo-
administrators and support
bile dealers.
or $15.7 million. The
(including the planned Cambridge Homes
staff.at Green
development TheBaygoal was
and Wadsworth
ing: “The continued dedication to service ex- Onstrong
for
Sunday,this growth
Januarylocation signaled
tofrombe a that
11, 1998 we moved catalyst many for members
Roads), Zion, and Winthrop Harbor.
Member
cellence by our staff and board of directors in
Mallard Creek Shopping Center Branch opened in Round Lake Beach in 1991
were
growth helped
in the with
our location at the Mallard Creek Shopping
low
Center, to our new office just completed the cost loans. It18Lake
also
By the end of 1998 CCCU was on a growth
south-central part of
trend that had already spanned consecu-
Mallard Creek Shopping Center Branch opened in Round
1995
As a result,
Lake was
reserves
innecessary
increased
Beach from 6.95% in to ensure
1991 ated in 1990the
grewfuture pros- per
to 70,000 transactions meant
Route 83 inthe
County.
and Roundcredit union
week before at the corner of Monaville Road
Lake Beach. The would ultimately earn
tive years and showed no signs of coming to
a halt anytime soon.
1990 to 7.01% at the end of 1991. This was month. The strong growth in assets and trans- wind howled and temperatures hovered near
perity of the credit
quite good considering the strong growth in union. We recognize
actions heightened managementʼs that
focus on more income. Had this
1999not happened, the
zero during the move. Despite the inclem-
assets for the year. Membership growth was training in order to prepare our staff to pro- ent weather Branch Manager LeRoy Wiese On December 7, 1999 a good friend and
guided completion of the move in a timely lifetime member Karrin M. Luhtala passed
very good with 1,321 new members opening vide courteous, personable, and efficient ser-
fashion and the office opened on time for away at age 96. Karrin was on our first
accounts, which brought total membership vice. This training initiative began in 1988 business the following day. Board of Directors in 1930, and served as
up to 35,084. and has helped the staff make solid progress
on our mission to provide our members with
33
the very first Board Secretary. She had the
Later in the year the credit union purchased distinction of holding account #1 at CCCU.
On October 1, 1991, the credit union opened Quality Service. a 6 acre site at the corner of Beach Road and Karrin was a dedicated supporter of credit
a second full service branch office in the Mal- Lewis Avenue in Waukegan. The plan was unions and reveled in the progress CCCU
lard Creek Shopping Center in Round Lake The Banking lobby sought to combine the 36
Beach located near the intersection of Rollins NCUSIF (National Credit Union Share In-
Road and Route 83. Our first branch opened surance Fund) with the FDIC (Federal De-significant
In addition amount of funds
to expanding the that
branchflowed into
footprint 1997
of Members by delivering the best possible
savings
to Roundwould
Lakehave ended
Beach and up in investments
Lincolnshire, the CCCU
personal experienced strong loan
service to Members. andtraining
This share/
credit union also made capital investments
where yields would have been less. in returned almost immediate dividends,
savings growth in 1997 and an improve- as the
our Mundelein and Waukegan facilities. The credit in
ment union receivedThis
earnings. numerous
helpedletters with
the credit
lower
The levels
good of was
news bothloan
offices were remodeled
delinquency had de- positive feedback from Members recognizing
union gain market share and improve fi-
to help us better manage our growing loan the quality service delivered by our staff.
clined from last yearʼs level. The bad news nancial soundness.
portfolio. When completed, the newly built-
was loans charged off increased dramatical- As a result of this success, the credit union
out Mundelein lower level became home to our
ly. Bankruptcies
Mortgage and VISAwereDepartments,
the prime culprit. In
while the By
madetheaend of 1997 assets
commitment increased
to make to $190.3
staff training a
fact, bankruptcies
remodeled represented
lower level in Waukegan$271,675 or
provided million. Many factors contributed to this
part of each employee’s annual development
68.9% of the total amount of the net charge
upgraded facilities for our Loan Department. growth.
program.For To one
meetthing,
thatshare/savings balanc-
charge, we adopted
off amount of $320,906. Unfortunately this several different training programs during
es grew by $19.5 million or 12.7%. This pro- the
Against
was this backdrop
no aberration. of new
It was locations of
the beginning anda decade. In 1993, for example, we added
vided most of the energy for the $21.4 million the
remodeled
trend facilities,
that would CCCU kept
significantly an eye on
contribute to Vision
in assetQuest program
growth. Loansfrom CUNAbyMutual
increased $16.7
future expansion opportunities as well. We Insurance Group (CMG). In later years, we
loans charged off in future years. million or 13.7%, just short of our 14% goal.
purchased land on the southeast corner of expanded our program to include CMG’s
Lewis Avenue and Beach Road on the north
The mortgage loan sector surpassed consumer
Business Development Sales Training (BDST)
Members benefitedin by
side of Waukegan a 22.7%
1998, increase
a six-acre in
site that loans for the
for staff, first time that
a program and accounted for 62%
was implemented
dividends. Despite this increase, and
would eventually become the home of our a high- of
for new Member-facing staff throughloans
total loan growth. The demand for the
er levelWaukegan
North of operating expenses,
facility. netadd
The goal: earnings
a fifth to purchaseofcars
remainder and trucks was very strong.
the decade.
amounted
location to to
our$1.5 million,
growing which
branch wasbyused
network the At the same time, loan delinquency and loan
to increase
year 2002. the ratio of reserves to assets to Upon completing
charge the installation
offs declined. This helpedofreduce
our new
ex-
core processing system in 1992, management
8.78%. The Annual Report stated: “The capi- penses related to charge offs thereby boosting
Staff Training was challenged to evaluate how we managed
tal and solvency position of your credit union net income.
The the workflow for transactions and other routine
is at CCCU management
a high point team recognized that
in our history.” activities. The purpose: determine where and
successfully managing the growth of products, We
services, delivery channels and facilities how signed
we couldup 913 new operating
increase members efficiency
bringing
In addition to achieving the major goals re- total membership to 38,920. The
throughout by increasing productivity service
and
required an aggressive staff training program.
lated to balance sheet growth and earnings, penetration ratio ofservice.
improving Member services to members in-
No matter how fast the place of growth and
1996 wasthe
change, a very good
credit yearwas
union in many other re-
committed to creased. This meant members used the ser-
spects. The credit As technology
offered to acontinued to evolve and
maintaining the union
highestcompleted the service
quality of design vices greater extent.
improve, this mind-set of reevaluating
This was
for our new Round
to Members. This Lake Beach
section Facility.
covers A
training in great part due to the sales and service ef-
processes became part of CCCU’s approach
fourth branch
highlights fromwas opened at Adlai Steven-
the decade. forts of the staff and to aggressive marketing.
to business. Each time we received a system
son High School. Business hours were in- A comprehensive
upgrade, we lookedmember
for new survey
ways towas con-
improve
The firstattraining
creased program
all offices withwas
the introduced in
exception of ducted during the year. It helped determine
1990, with all staff participating in several hours operating efficiency while maintaining
the Stevenson Branch. The Department of where
superiorimprovements
service. Mostinimportantly,
service needed to be
we made
of training designed to improve performance
Financial Institutions
in their specific gave the
areas while alsocredit union
helping thema made andwas
sure staff revealed that in
adequately general,
trained members
to handle any
level 1 rating, the highest rating possible,
to better understand how to increase the value and were very
changes pleased
before with the
deploying themrelationship
throughouttheythe
CCCU finished the year in a strong position had with their credit union.
enterprise.
to achieve our goals for 1997.
To monitor our success with this project, we
CCCU
hired theintroduced three new certificate
research department of de-
of Credit Union
posit products
National by creating
Association certificate
(CUNA) to maturity
conduct
durations of 15, 30 and 45 months.
extensive Member surveys on a periodic Thesebasis
new
savings
throughout instruments turned
the remainder of out to be quite
the decade. We
popular and grew
used Member by $8.2
feedback million
from thesebysurveys
year end.
to
A total ofour
fine-tune $6.1 millionprogram
training was paid in to
and dividends
identify
to members, which amounted to a 13.9%and
how we could improve Member service in-
further from
crease increase
the the value
prior of Membership.
year. We also launched
a new “Loan Line 24” service to enable mem-
Branch Office in Adlai Stevenson High School
34You can also read


