PROGRESS UPDATE ON STRATEGY AND FUTURE PLANS - JAMES CAMPBELL JUNE 2012
←
→
Page content transcription
If your browser does not render page correctly, please read the page content below
PROGRESS UPDATE ON
STRATEGY AND FUTURE PLANS
JAMES CAMPBELL
JUNE 2012
2

STOP PRESS!
•   STEINMETZ FOREVERMARK JUBILEE PINK

•   Saxendrift diamond selected for display at the

    TOWER OF LONDON as part of Queens Diamond Jubilee

•   The cushion cut, pink-brown diamonds weighing 35.60
    carats, was cut from a 179.60 carat rough diamond that was
    sold into the Company’s BENEFICIATION joint venture with
    Steinmetz Diamond Group (“SDG”)

                                                                 FOCUS ON DIAMOND VALUE MANAGEMENT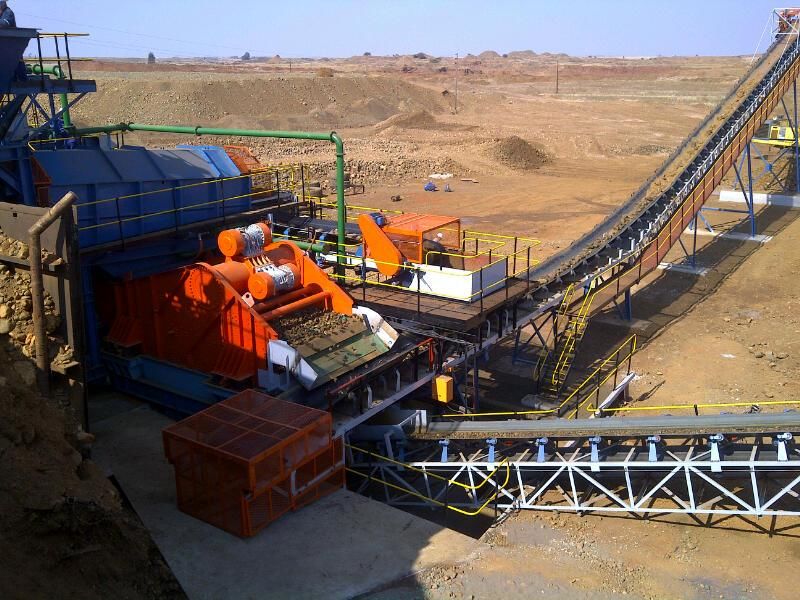
3

AGENDA
•   WHO IS ROCKWELL?
     –   Beneficiation and Rough Diamond Production
     –   Operations and Resources
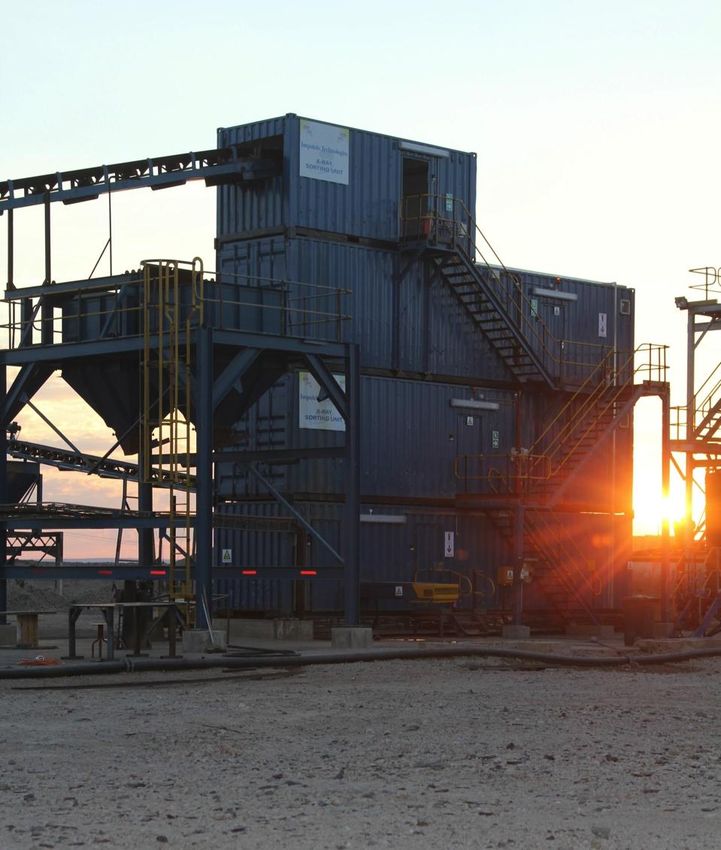
     –   Team                                         First diamonds recovered from bulk x-ray machine at Saxendrift

     –   Capital structure and shareholding
•   PROGRESS UPDATE
     –   Performance overview
     –   Strategic review
     –   Progress with turnaround
     –   Investments and Technology Projects
     –   Valuation Gap
•   WAY FORWARD
     –   Operational targets
     –   Growth objectives
     –   Diamond sector fundamentals
     –   Priorities and outlook

                                                                                       FOCUS ON DIAMOND VALUE MANAGEMENT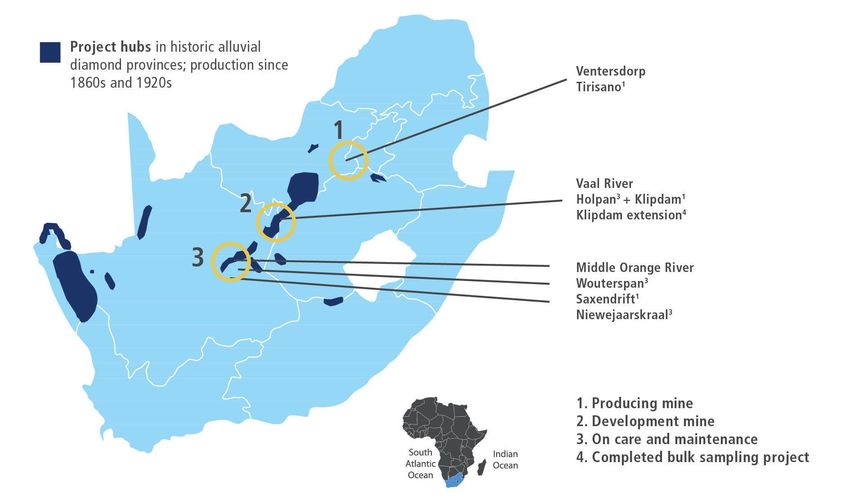
4
WHO IS ROCKWELL?
5

  BENEFICIATION JOINT VENTURE: SIGNIFICANT VALUE ADD
                                                                                                    BENEFICIATION
                                                      ROUGH               POLISHED
                                                                                                     VALUE ADD

                                                    105 ct Type II   35 ct D color internally       +62% on initial rough
                                                      A, Middle             flawless
                                                                      Sold for $230,000/ct              sale price
                                                       Orange

                                                    212 ct yellow,                                  +50% on initial rough
                                                                       102 ct vivid yellow
                                                   Middle Orange                                        sale price

                                                    128 ct yellow,
                                                                       81 ct vivid yellow               Not yet sold
                                                   Middle Orange

Steinmetz Diamond Group (SDG) profit share agreement (>2.8 carat stones)
• MARKET RELATED PRICES for diamonds sold into JV + 50% profit share
• Realized revenue of $7.8m in F2012
       • ±25% of revenue from beneficiation, expected to increase

                                                                                                FOCUS ON DIAMOND VALUE MANAGEMENT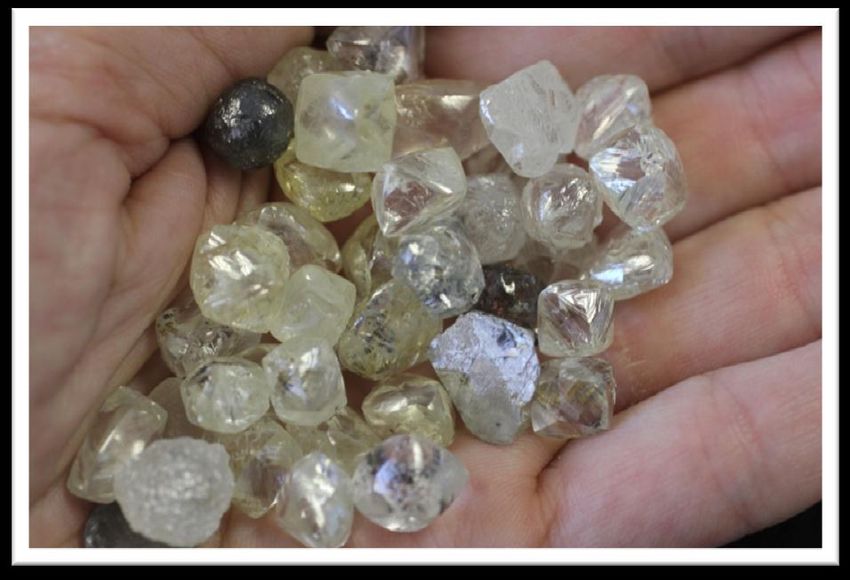
6

ROCKWELL ROUGH DIAMOND PRODUCTION: AVERAGE US$/CARAT

                                                  World Diamond Average
                                                                                                Small diamonds used in lower
                                                  $90/carat                                     price point and pavé jewellery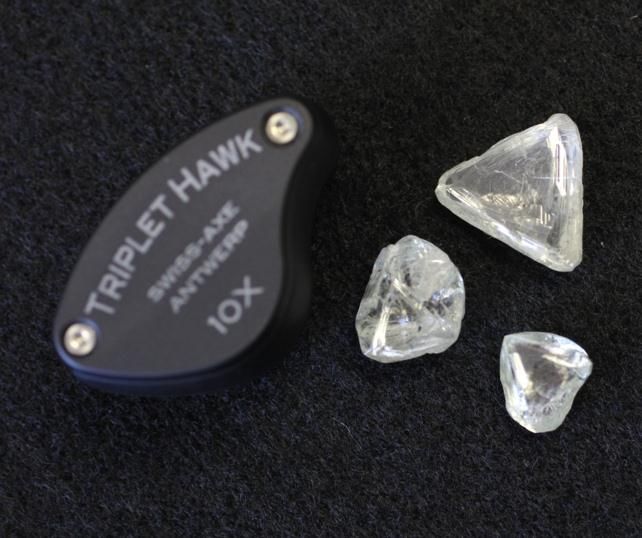
7

ROCKWELL OPERATIONS AND PROJECT LOCALITIES:
NORTHERN CAPE AND NORTH WEST PROVINCES, SOUTH AFRICA

                                               FOCUS ON DIAMOND VALUE MANAGEMENT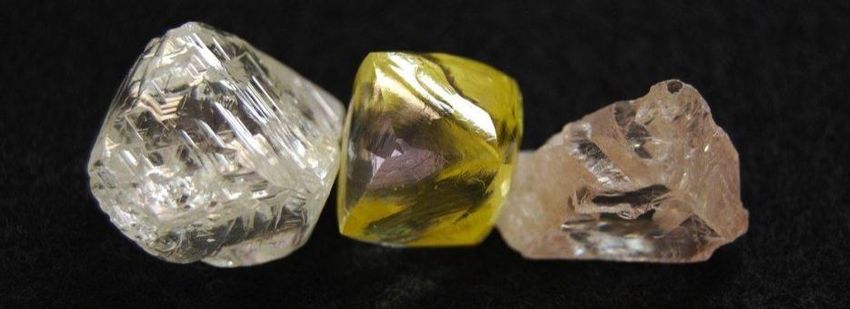
8

EXTENSIVE DEPOSITS TO BENEFIT FROM DIAMOND FUNDAMENTALS

                          Volume (m3)            Value (USD)
                                                                  See www.rockwelldiamonds.com for detailed 43-101 Mineral
      Category                            Carats                  Reserves & Resources: At 28 February 2011.
                          Feb 28 2011              millions       Estimates completed by Rockwell’s Manager, Resources, G.A. Norton, (Pr.
                                                                  Sci. Nat.), a qualified person who is not independent of the Company.
  Probable reserves        4,565,400      22,827         46.3     Reviewed by T.R. Marshall, PhD, (Pr. Sci. Nat.), Marshall, an independent
                                                                  qualified person
 Indicated resources      34,787,600      675,412        489.6
  Inferred resources      82,062,000      828,641    1,141.1
                                                     1,677.0

                                  Processing capacity                                        43-101 value
        Operation                                                Carats per month                                   Life of Mine (years)
                                       (m3 p.m. )                                           (US$ per carat)

   Middle Orange River:
                                          150,000                       750                      2,029                         5
        Saxendrift
       Vaal River:
                                       Klipdam: 90,000             Klipdam: 850             Klipdam: 1,229               Klipdam: 2
   Holpan* and Klipdam
       Ventersdorp:
                                           90,000                      1,400                       606                        18
         Tirisano

                                                                                                      FOCUS ON DIAMOND VALUE MANAGEMENT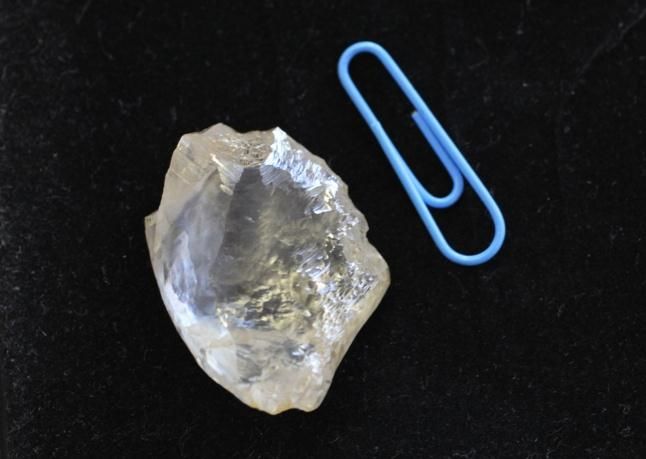
9

LEADERSHIP TEAM WITH CREDENTIALS TO DELIVER VALUE
Board of Directors:
                                                                                                     Group Technical
Mark Bristow (Chairman)                                           CFO
                                                                                                        Manager
Dave Copeland                                                Gerhard Jacobs,
                                                               BAcc, MBA                               Glenn Norton,
Richard Linnell                                                                                         BSC (Hons)
Willem Jacobs
Sandile Zungu
Johan van’t Hof                           Mining and corporate experience with      Geological, mineral resource
Stephen Dietrich                          junior and senior mining companies with   management and production
                                          operations in SA, Australia and Canada.   experience in alluvial diamond deposits,
                                          Knowledge of public listed mining         diamond and coal exploration. Qualified
                                          Companies.                                person and Pr.Sci.Nat.

                President and CEO                                COO
                                                                                                Diamond Marketing & Sales
                 James Campbell,                             Michael Hunt,                              Manager
                BSc (Hons ) ARSM,                       MSc (Advanced Chemical
                  MBA (Dunelm)                                Engineering)                           Jeffrey Brenner

Seasoned diamond executive with           >30 yrs in diamonds incl. mgt. roles at   A leading international diamantaire and
career spanning over 20 years at De       Orapa (world’s largest diamond mine) &
                                                                                    specialist in valuation, marketing and
Beers and 4 years as Managing             The Oaks (De Beers’ smallest mine).
Director of African Diamonds plc.         Operations Manager at Pangea              sales of rough diamond production from
FIMMM, C.Eng, C.Sci and Pr.Sci.Nat.       DiamondFields plc from 2007.              alluvial deposits.

                                                         Group HR/IR Manager
                                                                                                  Corporate Development
                                                            Richard Mhlonto,
                                                        Nat Dip (HR Management                      Stéphanie Leclercq
                   Dr Kurt Petersen,                        & Development)                              BSc, CFA
                  Ph.D. (Stellenbosch)

                                          Extensive HR & Industrial Relations       >12 yrs in investor relations and
                                          management experience including
Expert in economic diamond metallurgy.                                              corporate development. Worked as a
                                          organizational and structural design
Contracted to Rockwell for fiscal 2012.                                             sell side analyst and in-house IRO
                                          initiatives as well as strategy
                                          development and implementation.           across industry sectors.

                                                                                                FOCUS ON DIAMOND VALUE MANAGEMENT
10

CAPITAL STRUCTURE AND SHAREHOLDING
                                                        Top shareholders (% shares in issue)
                            Number of shares
                                               Strategic:
Shares outstanding             47,942,746      •   Daboll (Steinmetz)                     21.3%

Warrants                           -           •   Godia Capital                          8.3%
                                               •   Middle East Investors                  7.1%
Options ($0.90-9.45)           2,121,931
                                               Institutional:
Convertible Debt (~$0.56)      3,499,257
                                               •   Conus Partners                         6.9%
Fully Diluted                  53,563,934      •   Earth Resources (ERIG)                 3.6%
                                               •   Craton Capital                         2.6%
                                               •   Wells Capital                          1.6%
                                               Other:
                                               •   Etruscan                               2.6%
                                               •   Mark Bristow                           1.2%

                                                                           FOCUS ON DIAMOND VALUE MANAGEMENT
PROGRESS UPDATE
12

FISCAL 2012 PERFORMANCE OVERVIEW
•   Substantial progress with REPOSITIONING of Rockwell by new management
•   Beneficiation continues to add value: 64% INCREASE in beneficiation revenues to $7.8m
•   Saxendrift performance trending up: Direct result of DIAMOND VALUE MANAGEMENT strategy
     –    26% INCREASE in rough diamond sales to US$17.5m with 22% increase in average carat value
•   Long term production asset BROUGHT ON STREAM: Tirisano mine ramp up making progress
     –    One time cost of ramp up of $6.7m charged to earnings
•   Operating profit of $7.3m: Mining costs DOWN 4% despite impact of Tirisano costs
•   Net loss of $13.7m: Impact of STRATEGIC DECISIONS place Rockwell on a SOLID FOOTING
    with cleaner balance sheet
     –    Flow through to financials as mines continue to improve production with lower unit costs
     –    Midamines settlement and associated costs ($1.5m) and asset impairment ($4.9m)
•   CONTOPS implemented in January 2012 at Saxendrift and Klipdam
•   Net cash balances of $9.9M preserved to fund growth
•   Investments positioned Rockwell to deliver further IMPROVEMENTS and pursue GROWTH OPPORTUNITIES
    in fiscal 2013

                                                                                             FOCUS ON DIAMOND VALUE MANAGEMENT
13
STRATEGIC REVIEW CATALYZED CORPORATE TURNAROUND
• STRATEGIC REVIEW initiated after management changes in December 2010
• To achieve key CORPORATE OBJECTIVE: increasing annual production of
high-quality gemstones to 120,000 carats in 5 yrs
• TURNAROUND commenced with appointment of new management team
in June 2011
– CEO + COO with >50 years joint diamond experience
– DIAMOND VALUE MANAGEMENT: Brought focus on quality and
embedding new work culture throughout operations
• Comprehensive OVERHAUL of business focused on
– Optimizing the productive mines to deliver better returns
– Driving down costs
– Improving metallurgical processes
– Focus on recovery of diamonds as part of diamond value management
• Next phase: LEVERAGE PRODUCTION PROFILE by developing asset
inventory + possible M&A opportunities
FOCUS ON DIAMOND VALUE MANAGEMENT14
PROGRESS ON STRATEGIC REVIEW
• Understanding of GEOLOGY found to be rigorous with NI 43 101 reports on all properties
• Production issues in plant environment addressed through increased focus on DIAMOND PROCESSING
METALLURGY
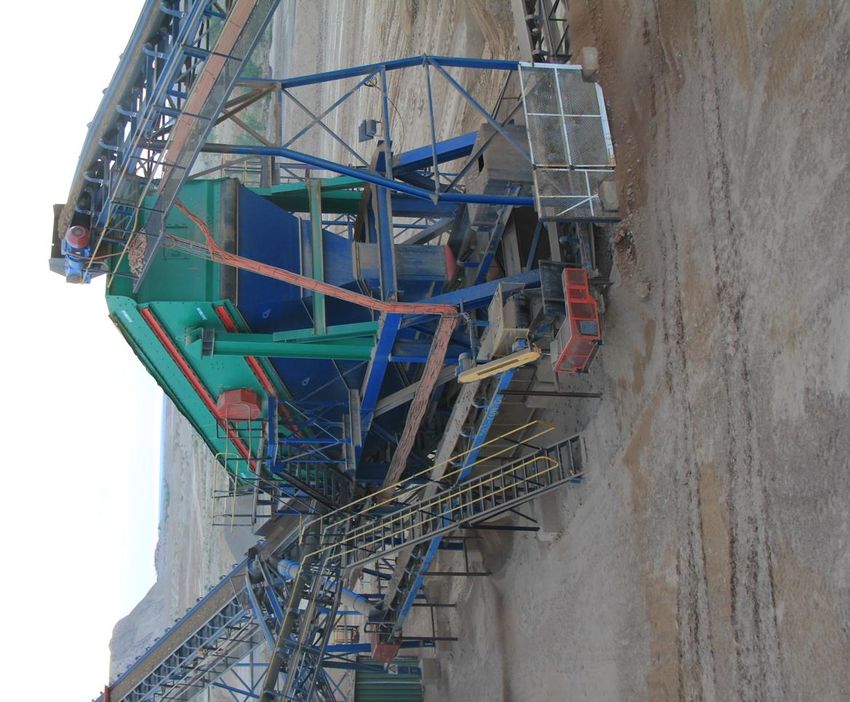
• SAXENDRIFT: Completion of new FIT FOR PURPOSE in field screen and bulk x-ray pilot project
– ON SCHEDULE: Delivering positive recovery performance and results
– New process technologies: BLUEPRINT for future mine development
• KLIPDAM: Economics for remaining LOM improved
– Mine plan adjusted to Rooikoppie with less intense earthmoving requirements
• TIRISANO: Ramp up in progress
– Short term impact on profitability: $6.7m = Full operating and ramp up costs expensed
• HOLPAN: Put on care and maintenance in May 2011
– Was delivering marginal results and reaching end of LOM
– Options to bring this asset to account under consideration
FOCUS ON DIAMOND VALUE MANAGEMENT15
CORPORATE LEGACY ISSUES RESOLVED
• RECAPITALIZATION in Q3: Private placement raised $7.8m + $6.5m from sales of non-core and underutilized assets
– Partly deployed: Implement technology improvements at Saxendrift and complete Tirisano plant
– Solid business case to underpin all further use of funds
• RESOLUTION of Midamines dispute: Final settlement of $1.2m paid
– Company is not aware of any other outstanding litigation
• FINALIZATION of an agreement with AVR: Effectively unwinds 2008 BEE deal (Northern Cape operations)
– Included acquisition of AVR’s Jasper Mine: contiguous to Saxendrift Mine with potential to extend LOM
– In negotiations to introduce other BEE groupings
• STRENGTHENED Board of Directors:
– Chairman: Mark Bristow
– Non-executives + audit committee: Johan van ‘t Hof and Stephen Dietrich
• In depth analysis of ASSET REGISTER to ensure accurate reflection of assets in balance sheet
– $4.9m impairment of property, plant and equipment
FOCUS ON DIAMOND VALUE MANAGEMENT16
DIAMOND VALUE MANAGEMENT: TANGIBLE BENEFITS IN Q4
• SAXENDRIFT: 42% increase in rough diamond sales to US$17.5m with 32% increase in carats sold
– 50% increase in carats produced and 5% drop in unit cost
• TIRISANO: Ramp up in progress with revenue of US$0.5m
– Good progress with wet front end
• STRATEGIC DECISIONS: Holpan mine on care and maintenance and trial mining at Klipdam Extension ceased
• Cost per carat DOWN 6%: Total mining costs down 3%
– Despite impact of Tirisano and upward pressure due to fuel, wages and maintenance costs
• CASH POSITIVE with net cash of $9.9m: After funding capex of $4.0m
Production Sales and inventories
Value of Sales Average value
Volume (m3) Carats Mining costs Sales (carats) Inventories (carats)
(US$) (US$ / carat)
Fourth quarter
661,627 4,043 10,370,000 6,030,376 5,795 1,041 114
fiscal 2012
FOCUS ON DIAMOND VALUE MANAGEMENT17
TECHNOLOGY PROJECTS AT SAXENDRIFT: IN FIELD SCREEN
• CHALLENGE:
– High sand content in gravel and productivity
impact when processing wet gravels
• SOLUTION:
– 3.0m x 8.0m Dabmar Bivitec screen
commissioned in November 2011
– Designed to treat sandy and wet gravels at
required processing rates
• IMPACT:
– Running at > 95% efficiency and operating at
17% above design throughput
– Monthly volumes up 30% (incl. impact of contops
and increased bottom cut off)
FOCUS ON DIAMOND VALUE MANAGEMENT18
TECHNOLOGY PROJECTS AT SAXENDRIFT: BULK X-RAY
• CHALLENGE:
– Low efficiencies in traditional pan plants and final
recovery
• SOLUTION:
– High throughput Bourevestnik (BV) sorter and
one BV single particle sorter to improve
concentrate efficiency and final sorting of
diamond bearing ore (capex $1.5m)
• IMPACT:
– Recovery in first 4 weeks: 316 stones = 1,109
carats have been recovered
– 14 stones >10 carats with largest weighing 76.4
carats
FOCUS ON DIAMOND VALUE MANAGEMENT19
TECHNOLOGY PROJECTS AT TIRISANO: WET FRONT END
• CHALLENGE:
– Current dry front-end cannot
deal with wet, clay rich
gravels
• SOLUTION:
– High water volume monitoring
and screening plant
(capex $200k)
• IMPACT:
– Currently being production
commissioned
FOCUS ON DIAMOND VALUE MANAGEMENT$m
0
2
4
6
8
10
12
14
16
18
20
Opening cash and
cash equivalents
Cash Generated
by Operations
Net changes in
working capital
Proceeds of
Private Placement
Proceeds of
convertible bond
Proceeds from
sale of assets
Capex: Tirisano, Saxendrift and
purchase of mineral property
interests
Movement in
ACHIEVE SHORT TO MEDIUM TERM OBJECTIVES
reclamation deposits
CASHFLOW: INVESTING IN CAPACITY FOR GROWTH
BALANCE SHEET PROVIDES REQUIRED WORKING CAPITAL TO
Other cash flows
Closing cash and
cash equivalents
FOCUS ON DIAMOND VALUE MANAGEMENT
20CORRELATION: RESOURCES TO PRODUCTION
1.5
1.4 Klipdam Recovered Grade vs. Resource Grade
1.3
Grade ct/100m³
1.2
1.1
1.0
0.9
0.8
0.7
Mine Grade 43101 Grade Budget Grade
0.6
0.5
Q3 2009
Q4 2009
Q1 2007
Q2 2007
Q3 2007
Q4 2007
Q1 2008
Q2 2008
Q3 2008
Q4 2008
Q1 2009
Q2 2009
Q1 2010
Q2 2010
Q3 2010
Q4 2010
Q1 2011
Q2 2011
Q3 2011
Q4 2011
3.0
Saxendrift Recovered Grade vs. Resource Grade
2.5
Mine Grade 43101 Grade Budget Grade Linear (Mine Grade)
Grade ct/100 m³
2.0
1.5
1.0
0.5
0.0
Jul 09
Jul 10
Jul 11
Apr 09
Apr 10
Apr 11
Apr 12
Aug 08
Jan 10
Jan 11
Jan 12
May 08
Nov 08
Oct 09
Oct 10
Oct 11
FOCUS ON DIAMOND VALUE MANAGEMENT22
INDEPENDENT VALUATION: CONFIRMED VALUATION GAP
Weighted market value estimate:
Adjusted book value / Fair Market Value of Properties
$62m
using discounted cashflow 70
Saxendrift
60
($15.5m -
$16.1m) Adjusted book value method
Wouterspan Guideline public company method
($47.4m - 50
Trading price method
$54.8m)
40
40%
Niewejaarskra
al ($37.4m - 30
$42.5m)
20
30%
Holpan Tirisano 10
($281,000) Klipdam ($17.6m -
($3.6m) 30%
$20.0m)
0
Resource properties: $121.9m - $137.3m
Adjusted book value: $149.5m - $165.0m
Additional details contained in “Additional Information”
FOCUS ON DIAMOND VALUE MANAGEMENT23
PEER GROUP REVIEW OF DIAMOND JUNIORS:
FURTHER CONFIRMATION OF ROCKWELL’S VALUE UPSIDE
Average price/carat sold (US$) Price: Tangible Book Value
1200 7
6
1000
5
800
4
600
3
400
2
200
1
0
0
Diamond- Firestone Lucara Mountain Namakwa Rockwell Stellar Trans Hex
corp Province Diamonds Diamond- Firestone Lucara Mountain Namakwa Rockwell Stellar Trans Hex
corp Province Diamonds
Enterprise value ($m) Market Cap: Resource value
$500 12%
$400 10%
$300 8%
$200 6%
$100 4%
$- 2%
Diamond- Firestone Lucara Mountain Namakwa Rockwell Stellar Trans Hex 0%
$(100) corp Province Diamonds
Diamond- Firestone Lucara Mountain Namakwa Rockwell Stellar Trans Hex
corp Province Diamonds
Source: Company websites, ThomsonReuters
FOCUS ON DIAMOND VALUE MANAGEMENTWAY FORWARD
25

 OPERATIONAL TARGETS FOR FISCAL 2013

                                                               CASH OPERATING
                    PRODUCTION              GRADE                 COST/m3                    CAPITAL           REVENUE/CARAT
     MINE
                       (m3)              (carats/100m3)                                    EXPENDITURE             (US$)
                                                             BUDGET           F2012

                    At name plate                                                                               In line with F2012
  KLIPDAM                                     Stable           $7.32*         $10.72           Minimal
                   capacity (90 000)                                                                                    YTD

                    Increase to 150
                                                                                                                 In line with two
SAXENDRIFT          000 with new in-          Stable           $8.42          $8.27           $400,000
                                                                                                                  year average
                      field screen

                     Ramping up to           Gradual
                                                                                                                In line with stated
  TIRISANO           90,000m3 p.m.       improvement to       $10.38**        $20.11          $750,000
                                                                                                                  prices of $700
                        06/2012            1.8 by 06/12

- ZAR/CAD exchange rate of 8.00                            - Full implementation of contops at all operations for F2013
- Corporate expenses budgeted to remain stable
- Beneficiation (stones > 2.8 carats) not included in average price per carat expectation
* Change of mining plan       ** Ramp-up

                                                                                                   FOCUS ON DIAMOND VALUE MANAGEMENT
26
GROWTH PLAN: CREATE CRITICAL MASS AND SCALE
Further upside potential from Jasper Mine
Reviewing additional capital requirement to fund expansion with preference for internal cash flows
140,000 1,000,000
120,000 Production targets
800,000
Volume / month (m3)
Total carats / year
100,000
80,000 600,000
60,000 400,000
40,000
200,000
20,000
- -
F2012A F2013 F2014 F2015 F2016 F2017 F2018
Niewejaarskraal Wouterspan Tirisano Klipdam Saxendrift Other Total Production / month
300,000,000
Revenue targets *
250,000,000
Revenue / year ($m)
200,000,000
150,000,000
100,000,000
50,000,000
0
F2012A F2013 F2014 F2015 F2016 F2017 F2018
Other Niewejaarskraal Wouterspan Tirisano Klipdam Saxendrift
Projected production based on mine plans in November 2010 preliminary assessments (Tirisano,
Wouterspan and Niewejaarskraal) and prefeasibility study (Saxendrift). Refer to Saxendrift resource
statement on www.rockwelldiamonds.com
* Based on budgeted carat values for 2013 and 2.5% annual price increases
FOCUS ON DIAMOND VALUE MANAGEMENT27
REVIEW OF INVESTMENT OPTIONS: VALUE CREATION POTENTIAL
NPV / Capital Expenditure (times) Rockwell Diamonds Inc Capital Development
(Bubble Size = Capital Requirement)
12 R 900 Niewejaarskraal
R 800
10 Wouterspan
R 700
NPV (ZAR millions)
8 R 600 Saxendrift
Extension IFS
R 500 Only
Tirisano
6 Expansion
R 400
4 R 300
Saxendrift
R 200 Extension
2 Complete Plant
R 100
0 R0
Wouterspan Niewejaarskraal Saxendrift Tirisano 0 50 100 150
Extension Expansion
Resource Size m (millions)
3
Projected production based on mine plans in November 2010 preliminary assessments (Tirisano,
Wouterspan and Niewejaarskraal) and prefeasibility study (Saxendrift). Refer to Saxendrift resource
statement on www.rockwell diamonds.com.
FOCUS ON DIAMOND VALUE MANAGEMENT28
STRONG FUNDAMENTALS FOR DIAMOND SECTOR
• Diamond DEMAND in carats forecast to grow at 6% p.a. to 2020 ROCKWELL PRODUCTION PROFILE BIASED
TOWARDS LARGE STONES
– OUTPACING annual SUPPLY growth of 2.8%
100%
– CHINESE and INDIAN MIDDLE CLASS to double by 2020 % of carats exceeding 2 cts
90%
% of revenue exceeding 2cts
• ECONOMIC UNCERTAINTY currently impacting sentiment in diamond market 80%
– Industry OVERSTOCKED with expensive rough diamonds 70%
– Resulting in pricing slowdown, especially for smaller stones 60%
• Growing SCARCITY of +2CT diamonds 50%
– Globally: Currently represents 5% of diamond PRODUCTION and 50% 40%
of sales VALUE for producers 30%
20%
10%
0%
Saxendrift Klipdam Tirisano
• ROCKWELL PRICING against current market
– SMALLER STONES: Reduction of ±20%
– >2 CARATS : Stable pricing
– LARGE SPECIALS: Strong demand
FOCUS ON DIAMOND VALUE MANAGEMENT29
PRIORITIES AND OUTLOOK: FISCAL 2013
PRIORITIES: CEMENT TURNAROUND PROGRESS OUTLOOK: POSITIVE LONG TERM FUNDAMENTAL
• KLIPDAM: Achieve volume targets and improve lower • INCREASING DEMAND from China and India and
unit costs under leadership of new Mine Manager reducing supply
• SAXENDRIFT: Optimize mine plan + continue optimizing • Prices and demand expected to continue
in field screen INCREASING
• TIRISANO: Ramp up to full production + complete wet • Rockwell’s BALANCE SHEET provides working
front end + improve availability of earthmoving fleet capital for short to medium term plans
• BEE: Complete process to introduce new partner and • Ongoing review of potential corporate actions for
secure funding GROWTH
• CORPORATE: Deploy bulk X-ray technology at • Continue adding value through BENEFICIATION joint
Saxendrift for bulk sampling and other projects venture with Steinmetz
• GROWTH: Planning and feasibility of Wouterspan using • Deliver on OPERATIONAL PRIORITIES to start
new technology blueprint seeing financial benefits
FOCUS ON DIAMOND VALUE MANAGEMENT30
FORWARD LOOKING STATEMENTS
Except for statements of historical fact, this presentation release contains certain "forward-looking information" within the meaning of applicable securities law. Forward-
looking information is frequently characterized by words such as "plan", "expect", "project", "intend", "believe", "anticipate", "estimate" and other similar words, or
statements that certain events or conditions "may" or "will" occur. Although the Company believes the expectations expressed in such forward-looking statements are
based on reasonable assumptions, such statements are not guarantees of future performance and actual results or developments may differ materially from those in the
forward-looking statements.
Factors that could cause actual results to differ materially from those in forward-looking statements include uncertainties and costs related to exploration and
development activities, such as those related to determining whether mineral resources exist on a property; uncertainties related to expected production rates, timing of
production and cash and total costs of production and milling; uncertainties related to the ability to obtain necessary licenses, permits, electricity, surface rights and title
for development projects; operating and technical difficulties in connection with mining development activities; uncertainties related to the accuracy of our mineral
resource estimates and our estimates of future production and future cash and total costs of production and diminishing quantities or grades if mineral resources;
uncertainties related to unexpected judicial or regulatory procedures or changes in, and the effects of, the laws, regulations and government policies affecting our mining
operations; changes in general economic conditions, the financial markets and the demand and market price for mineral commodities such and diesel fuel, steel,
concrete, electricity, and other forms of energy, mining equipment, and fluctuations in exchange rates, particularly with respect to the value of the US dollar, Canadian
dollar and South African Rand; changes in accounting policies and methods that we use to report our financial condition, including uncertainties associated with critical
accounting assumptions and estimates; environmental issues and liabilities associated with mining and processing; geopolitical uncertainty and political and economic
instability in countries in which we operate; and labour strikes, work stoppages, or other interruptions to, or difficulties in, the employment of labour in markets in which we
operate our mines, or environmental hazards, industrial accidents or other events or occurrences, including third party interference that interrupt operation of our mines or
development projects.
For further information on Rockwell, Investors should review Rockwell's annual Form 20-F filing with the United States Securities and Exchange Commission
www.sec.com and the Company's home jurisdiction filings that are available at www.sedar.com.
This presentation also uses the terms 'indicated resources' and 'inferred resources'. Rockwell Diamonds Inc. advises investors that although these terms are recognized
and required by Canadian regulations (under National Instrument 43-101 Standards of Disclosure for Mineral Projects), the U.S. Securities and Exchange Commission
does not recognize them. Investors are cautioned not to assume that any part or all of the mineral deposits in these categories will ever be converted into reserves. In
addition, 'inferred resources' have a great amount of uncertainty as to their existence, and economic and legal feasibility. It cannot be assumed that all or any part of an
Inferred Mineral Resource will ever be upgraded to a higher category. Under Canadian rules, estimates of Inferred Mineral Resources may not form the basis of feasibility
or pre-feasibility studies, or economic studies except for Preliminary Assessment as defined under 43-101. Investors are cautioned not to assume that part or all of an
inferred resource exists, or is economically or legally mineable.
The securities of Rockwell being offered have not been, nor will be, registered under the U.S. Securities Act and may not be offered or sold within the United States or to,
or for the account or benefit of, U.S. persons absent U.S. registration or an applicable exemption from U.S. registration requirements. This information does not constitute
an offer or sale of securities in the United States. Prior to making any investment decision, investors should consult a professional advisor.
FOCUS ON DIAMOND VALUE MANAGEMENTADDITIONAL INFORMATION
32

    SUSTAINABLE DEVELOPMENT
•    Supporting LOCAL ECONOMIC DEVELOPMENT

      –    LOCAL BENEFICIATION: 85% of diamonds in South Africa

      –    Provided STARTUP CAPITAL and mentorship for construction and brickmaking factory

•    SAFETY: Committed to providing safe working environment

      –    ONE MILLION LTI FREE hour record at Saxendrift

•    Employment: 683 full time employees

      –    Total of 79 new jobs created with conversion to CONTOPS in Northern Cape

•    Corporate Social Investment

      –    Supporting LOCAL ORGANIZATIONS focused on under privileged children, education
           and feeding schemes for elderly

•    Managing ENVIRONMENTAL impact: REHABILITATION as
     land is mined

                                                                                        FOCUS ON DIAMOND VALUE MANAGEMENT
33
INDEPENDENT VALUATION1: CONFIRMED VALUATION GAP
1. The valuation, dated February 28, 2011, conducted by Jennifer Lucas, MBA, CBV, ASA,
Adjusted book value method of Evans & Evans Inc.
using discounted cashflow 1. Valuation of 74% of mine
2. Discount rates:
Operation Value range Wouterspan, Tirisano and Niewejaarskraal: 25.36% to 28.96%
Klipdam, Holpan and Saxendraft: 22.36% to 24.96%
Wouterspan3 $47.4m - $54.8m 4. Adjustments to balance sheet of Rockwell to evaluate fair value of net assets at
February 28, 2011
Tirisano3 $17.6m - $20.0m
Midpoint of fair
Fair Market Value2
Klipdam3 $3.6m Value Value
Valuation method market value Weighting Weighting
($m) ($m)
Holpan3 $281,000 ($m)
Trading price
Niewejaarskraal3 $37.4m - $42.5m 25.28 40% 10.11 40% 10.1
method5
Saxendrift3 $15.5m - $16.1m
Resource properties $121.9m - $137.3m Guideline public
15.80 30% 4.74 25% 3.95
Adjusted book value 4
$149.5m - $165.0m company method6
5. Valuation using average trading price of Rockwell for the
10 and 90 days preceding the valuation date Adjusted book
6. A guideline public company method comparing Rockwell’s 157.25 30% 47.18 35% 55.04
value method
average dollar value per enterprise
value of reserves and resources to eight peer group
companies Total 62.00 69.10
FOCUS ON DIAMOND VALUE MANAGEMENTYou can also read


