FIRST QUARTER 2021 EARNINGS - MGM RESORTS INTERNATIONAL - APRIL 28, 2021
←
→
Page content transcription
If your browser does not render page correctly, please read the page content below
MGM RESORTS INTERNATIONAL
FIRST QUARTER 2021 EARNINGS

        APRIL 28, 2021
        MGM RESORTS INTERNATIONAL
F O R WA R D - L O O K I N G S T A T E M E N T S
Statements in this presentation that are not historical facts are forward-looking statements, within the meaning of the Private Securities Litigation Reform Act of 1995 and involve risks and/or uncertainties, including
those described in the Company's public filings with the Securities and Exchange Commission. The Company has based forward-looking statements on management’s current expectations and assumptions and
not on historical facts. Examples of these statements include, but are not limited to, the Company’s expectations regarding its financial outlook (including expectations regarding its liquidity position, long term cost
savings and the performance at re-opened properties), the continued impact of the COVID-19 pandemic on the Company’s operations, the Company’s ability to execute on its strategic pillars, expectations
regarding the development of an integrated resort in Japan and the positioning of BetMGM as a leader in sports betting and iGaming (including BetMGM’s expected growth in new and existing jurisdictions and
projected market share and net revenues). These forward-looking statements involve a number of risks and uncertainties. Among the important factors that could cause actual results to differ materially from those
indicated in such forward-looking statements include the continued impact of the COVID-19 pandemic, effects of economic and other conditions in the markets in which the Company operates and competition
with other destination travel locations throughout the United States and the world, the design, timing and costs of expansion projects, risks relating to international operations, permits, licenses, financings,
approvals and other contingencies in connection with growth in new or existing jurisdictions and additional risks and uncertainties described in the Company’s Form 10-K, Form 10-Q and Form 8-K reports
(including all amendments to those reports). In providing forward-looking statements, the Company is not undertaking any duty or obligation to update these statements publicly as a result of new information,
future events or otherwise, except as required by law. If the Company updates one or more forward-looking statements, no inference should be drawn that it will make additional updates with respect to those other
forward-looking statements.

                                                                                  MARKET AND INDUSTRY DATA
This presentation also contains estimates and information concerning the Company’s industry that are based on industry publications, reports and peer company public filings. This information involves a number
of assumptions and limitations, and you are cautioned not to rely on or give undue weight to this information. The Company has not independently verified the accuracy or completeness of the data contained in
these industry publications, reports or filings. The industry in which we operate is subject to a high degree of uncertainty and risk due to a variety of factors, including those described in the “Risk Factors” section of
the Company’s public filings with the SEC. Third party logos and brands included in this presentation are the property of their respective owners and are included for informational purposes only.

                                         NOTE REGARDING PRESENTATION OF NON -GAAP FINANCIAL MEASURES
This presentation includes certain “non-GAAP financial measures” as defined in Regulation G under the Securities Exchange Act of 1934, as amended, including, among others, Adjusted EBITDAR, Table Games
Hold Adjusted Las Vegas Strip Resorts Adjusted Property EBITDAR, and Adjusted EPS. Schedules that reconcile the non-GAAP financial measures to the most directly comparable financial measures calculated
and presented in accordance with Generally Accepted Accounting Principles in the United States are included herein or in the Company’s earnings releases that have been furnished with the SEC and are available
on our website at www.mgmresorts.com.

                                  IMPORTANT NOTE REGARDING BETMGM FINANCIAL AND OTHER INFORMATION
This presentation includes certain financial and other information related to BetMGM and the industry in which BetMGM operates, which is jointly owned by the Company and Entain plc. This information was
obtained from BetMGM management and while the Company believes such information to be reliable and accurate, the Company has not independently verified it and does not make any representation as to its
accuracy. Included in this information is BetMGM reported net revenues from operations, forecasted 2022 net revenues from operations and long-term EBITDA margin targets. BetMGM financial information is not
prepared in accordance with GAAP. If BetMGM presented these financial measures in accordance with GAAP, then BetMGM would present the revenues associated with its Nevada digital and retail sports betting
operations differently, until such time as BetMGM is directly licensed as a Nevada gaming operator. Currently under GAAP, its calculation of net revenue would be on a basis net of operating costs, such that the
GAAP reported net revenue would be lower than the net revenue reported herein, with net income remaining the same. BetMGM projected net revenue from operations and target EBITDA margins are also based
on significant assumptions regarding the extension of current market trends in the states where BetMGM currently operates as well as assumptions regarding BetMGM’s expansion into new jurisdictions in 2021
and 2022. These assumptions are subject to significant risks and uncertainty and as a result investors are cautioned not to place undue reliance on such statements as a prediction of BetMGM’s actual results. See
“Forward-looking Statements” above.

  MGM RESORTS INTERNATIONAL                                                                                                                                                                                                     2
OUR STRATEGIC PILLARS
Recruit, develop and retain the best talent
STRONG PEOPLE Foster a culture of diversity and inclusion
AND CULTURE
Invest in the employee experience
Leverage a customer-centric model reinforced by
CUSTOMER-CENTRIC a strong brand and deep customer insights to
provide unmatched entertainment experiences for
MODEL our guests and drive top-line growth
OUR VISION:
TO BE THE WORLD’S
PREMIER Operating model refinement to maximize
operating efficiencies and expand margins
GAMING ENTERTAINMENT OPERATIONAL
COMPANY EXCELLENCE Enhancement of digital capabilities to strengthen
customer loyalty
Pursuit of targeted, attractive ROI opportunities
DISCIPLINED CAPITAL that align to the Company’s strategic vision
ALLOCATION TO MAXIMIZE Focus on shareholder returns
SHAREHOLDER VALUE
Fortify balance sheet
MGM RESORTS INTERNATIONAL 3• 1Q 2021 HIGHLIGHTS
• 1Q 2021 FINANCIAL RESULTS
TABLE OF
CONTENTS • BETMGM
• SUPPLEMENTAL
4KEY 1Q 2021 TAKEAWAYS
Domestic markets solidly improving, with sequential improvement over 4Q 2020
• With nationwide vaccination rollouts underway, Las Vegas Strip recovery is well on track with meaningful uptick in domestic leisure and casino demand
• Regional properties achieved record 1Q Adjusted Property EBITDAR and margins
• MGM China outperformed the market, with 1Q 2021 GGR recovering to ~40% of pre-pandemic 4Q 2019 levels, compared to broader market’s 33%;
Expect Macau’s rate of recovery to be gradual
Strong operating model and liquidity to position the Company for long-term growth
• Expect to permanently reduce approximately $450 million of domestic expenses relative to 2019 levels
• Evidenced by significant margin improvement in 1Q 2021 across both Las Vegas and Regional operations
• Strong liquidity position and improving operating environment allows MGM Resorts to continue disciplined execution of long-term strategy while returning
cash to shareholders
– In 1Q 2021, repurchased 3.15 million shares at an average price of $37.87 per share for an aggregate amount of $119 million
Long-term vision to be the world’s premier gaming entertainment company
• U.S. Sports betting and iGaming opportunity: Believe BetMGM has already established itself as a leader
• Investing in the Company’s digital transformation to drive customer loyalty
• Asia expansion: Pursuit of Japan integrated resort opportunity and further investments in Macau
MGM RESORTS INTERNATIONAL 51Q 2021 FINANCIAL HIGHLIGHTS
($ in U.S. millions, except per share information)
1Q21 1Q20 $ Change % Change
Consolidated Net Revenue $1,648 $2,253 ($605) (27%)
Las Vegas Strip Resorts $545 $1,134 ($589) (52%)
Regional Operations $711 $726 ($14) (2%)
MGM China $296 $272 $24 9%
Net Income (Loss) Attributable to MGM Resorts ($332) $807 ($1,139) NM
Diluted Earnings (Loss) Per Share ($0.69) $1.64 ($2.33) NM
Adjusted EPS ($0.68) ($0.45) ($0.23) NM
Consolidated Adjusted EBITDAR $218
Las Vegas Strip Resorts Adjusted Property EBITDAR $108 $268 ($160) (60%)
Table Games Hold Adjusted Las Vegas Strip Resorts
$107 $273 ($166) (61%)
Adjusted Property EBITDAR
Regional Operations Adjusted Property EBITDAR $242 $152 $90 59%
MGM China Adjusted Property EBITDAR $5 ($22) $27 NM
CityCenter Adjusted EBITDA $33 $79 ($45) (58%)
MGM RESORTS INTERNATIONAL 6SEQUENTIAL DOMESTIC IMPROVEMENT IN 1Q 2021
($ in U.S. millions) ACTUAL HOLD ADJUSTED
1Q21 vs. 4Q20 Change 1Q21 vs. 4Q20 Change
Adjusted Property EBITDAR 1Q21 4Q20 1Q21 4Q20
$ % $ %
Las Vegas Strip Resorts $108 $54 +$54 101% $107 $57 +$50 88%
Regional Operations $242 $159 +$83 53%
MGM China $5 $41 -$36 -88% $5 $43 -$38 -88%
Adjusted Property EBITDAR Margins 1Q21 4Q20 1Q21 vs. 4Q20 Change 1Q21 4Q20 1Q21 vs. 4Q20 Change
Las Vegas Strip Resorts 20% 11% +860 bps 20% 12% +792 bps
Regional Operations 34% 27% +738 bps
MGM China 2% 13% -1,181 bps 2% 14% -1,234 bps
• Las Vegas Strip Resorts: Meaningful acceleration in leisure and casino visitation since mid-February, and March was the best
month since opening. Strong operating productivity also drove margin improvement in the first quarter
• Regional Operations: Robust consumer demand amid easing restrictions, combined with the Company’s keen focus on costs
resulted in 1Q records for Adjusted Property EBITDAR and margins
• MGM China: Sequential decrease in Adjusted Property EBITDAR and margins primarily due to the $23 million bonus accrual
reversal positively impacting the fourth quarter, as well as lower mass hold in the first quarter compared to the fourth quarter
MGM RESORTS INTERNATIONAL Note: Calculations may not match exactly, due to rounding
7OUR LIQUIDITY POSITION REMAINS STRONG
CONSOLIDATED LIQUIDITY OVERVIEW
MGM Resorts MGM Resorts
($ in U.S. millions) (Ex. MGM China and MGP) MGM China MGP Consolidated
Cash and Equivalents $4,939 $1,090 $143 $6,172
Revolver Availability $1,469 $747 $1,350 $3,566
Total Liquidity $6,408 $1,837 $1,493 $9,738
• MGM Resorts’ domestic operations had $6.4 billion of liquidity as of March 31, 2021
• MGM Resorts (consolidated) had $9.7 billion of liquidity as of March 31, 2021
• In March 2021, MGM China raised an additional $750 million of 4.75% senior notes due 2027
• In March 2021, MGM completed the 37.1 million MGP OP unit redemption for cash proceeds of ~$1.2 billion
– Reduced MGM’s ownership stake in MGP from 53.0% to 42.1%
MGM RESORTS INTERNATIONAL 8DEMONSTRATING OPERATING MODEL STRENGTH
MGM 2020 savings include initiatives launched at the end of 2019 that began yielding tangible results prior to
the COVID-19 crisis
Through the pandemic, the Company has fundamentally re-evaluated how it operates, with a focus on permanently
eliminating redundancies and low profitability initiatives
The Company grows increasingly confident in its ability to deliver on these savings when demand returns to 2019 levels
Annualized
($ in U.S. millions)
Run-rate1
Corporate expense (gross)2 $180
MGM 2020 $160
Operations streamlining $85
Fixed Labor $25
Annualized domestic cost reductions $450
1 Annual run-rate savings relative to 2019 actuals
MGM RESORTS INTERNATIONAL 2 Represents gross corporate expense savings, a large portion of which gets allocated to property-level operating results
9• 1Q 2021 HIGHLIGHTS
• 1Q 2021 FINANCIAL RESULTS
TABLE OF
CONTENTS • BETMGM
• SUPPLEMENTAL
101Q 2021 – LAS VEGAS STRIP
Net Revenues Adjusted Property EBITDAR
($ in U.S. millions)
($ in U.S. millions)
Actual Hold-Adjusted Actual Hold-Adjusted
$1,134 $1,141
$268 $273
$545 $544
$108 $107
1Q21 1Q20 1Q21 1Q20 1Q21 1Q20 1Q21 1Q20
• Casino revenue decreased 16% compared to the prior year quarter • Rooms revenue decreased 60% compared to the prior year quarter
– Table games drop of $529 million compared to $841 million in 1Q 2020 – Occupancy of 46% compared to 88% in 1Q 2020
– Table games win % of 24.1% compared to 23.2% in 1Q 2020 Midweek occupancy: 39%
Weekend occupancy: 62%
– Slot handle $2.3 billion compared to $2.5 billion in 1Q 2020
– ADR declined 30% to $129 compared to $183 in 1Q 2020
– Slot win % of 9.2% compared to 9.4% in 1Q 2020
– RevPAR1 decreased 63% to $60 compared to $160 in 1Q 2020
Note: Excludes CityCenter; On March 17, 2020, MGM Resorts temporarily closed its Las Vegas Strip properties due to the COVID-19 pandemic; In 1Q 2021, Mandalay Bay, Mirage and Park
MGM RESORTS INTERNATIONAL MGM hotel rooms were closed mid-week until March 3, 2021. 11
1 RevPAR is hotel revenue per available room. Rooms that were out of service during the three months ended March 31, 2021 and March 31, 2020, including full and midweek closures, as
a result of the Covid-19 pandemic were excluded from the available room count when calculating hotel occupany and REVPAR.1Q 2021 – REGIONAL OPERATIONS
($ in U.S. millions)
Net Revenue Adjusted Property EBITDAR Margin %
$711 $726
34%
21%
$242
$152
1Q21 1Q20 1Q21 1Q20 1Q20 1Q21
• Casino revenue increased 11% compared to the prior year quarter • Adjusted Property EBITDAR margin of 34.0% in 1Q 2021, a 1,311-basis
– Table games drop of $819 million compared to $844 million in 1Q 2020 point increase compared to the prior year quarter
– Table games win % of 21.2% compared to 19.4% in 1Q 2020 • Strong focus on costs and operating productivity resulted in double-digit
– Slot handle of $5.4 billion compared to $5.2 billion in 1Q 2020 margin improvement vs. 1Q 2020
– Slot win % of 9.8% compared to 9.6% in 1Q 2020
Note: Between March 13, 2020 and 17, 2020, MGM Resorts temporarily closed its regional properties due to the COVID-19 pandemic. MGM Springfield’s hotel was closed beginning
MGM RESORTS INTERNATIONAL November 2, 2020, and partial hotel operations resumed with midweek closures on March 5, 2021. MGM Grand Detroit re-closed on November 17, 2020 and re-opened on December 23,
12
2020, with the hotel tower operations resuming February 9, 20211Q 2021 – CITYCENTER
($ in U.S. millions)
1 . S T R U C T U R E T O D A Y ( 7 3 % O WN E R S H I P O F O P ) 3. MGM RESORTS LONG-TERM STRATEGY
Net Revenue Adjusted EBITDA
$265
$134
$79
$33
1Q21 1Q20 1Q21 1Q20
• Hotel Stats • Key Balance Sheet Items (as of 3/31/21)
– Occupancy of 41.3% compared to 86.0% in 1Q 2020 – Cash and cash equivalents: $137 million
– ADR declined 27% to $209 compared to $285 in 1Q 2020 – Availability under revolver: $121 million
– RevPAR1 decreased 65% to $86 compared to $245 in 1Q 2020 – Total debt: $1.73 billion
MGM RESORTS INTERNATIONAL 1RevPAR is hotel revenue per available room. Rooms that were out of service during the three months ended March 31, 2021 and 2020 including full and midweek closures, as a result of
13
the Covid-19 pandemic were excluded from the available room count when calculating hotel occupancy and REVPAR.1Q 2021 – MGM CHINA
Net Revenues Adjusted Property EBITDAR
($ in U.S. millions)
($ in U.S. millions)
Actual Hold-Adjusted Actual Hold-Adjusted
$296
$294 $5 $5
$275
$272
$(17)
$(22)
1Q21 1Q20 1Q21 1Q20 1Q21 1Q20 1Q21 1Q20
• VIP table games: 31% decrease in turnover year-over-year; win percentage of 3.3%
• Main floor table games: 34% increase in volume year-over-year; win percentage of 22.0%
• See Supplemental section for MGM China reported property-level details
MGM RESORTS INTERNATIONAL 14MGM CHINA’S MARKET OUTPERFORMANCE
GGR MARKET SHARE IN 1Q 2021 STILL WELL ABOVE 2019 / 2020 LEVELS
MGM China GGR Market Share
12.6%
11.5%
9.9%
9.4% 9.5%
9.2%
8.7%
7.4% 7.4%
1Q19 2Q19 3Q19 4Q19 1Q20 2Q20 3Q20 4Q20 1Q21
MGM RESORTS INTERNATIONAL Source: DICJ Macau GGR
15FINANCIAL ITEMS
• BetMGM
– 1Q 2021 net revenues associated with BetMGM operations were $163 million1
– MGM Resorts’ 50% share of BetMGM’s operating loss2 was $59 million in 1Q 2021
– MGM Resorts and Entain expect to fund approximately $450 million in 2021
• Management and other operations3
– 1Q 2021: $14 million
– Included a non-recurring $20 million benefit related to the buyout of a profit share agreement with PlayStudios, which the Company expects to
fund directly back to PlayStudios as part of a PIPE investment as they prepare to go public
• Corporate expense (net)3
– 1Q 2021: $67 million, down 26% year over year
– Expect net corporate expense to run higher through the remainder of 2021 as business volumes continue to improve, and the Company ramps
investments in IT, digital and IR efforts in Japan
• Capital expenditures
– 1Q 2021 U.S.: $49 million
– 1Q 2021 MGM China: $30 million
1 Net revenues for 1Q 2021 for the BetMGM joint venture on a GAAP basis was approximately $156 million, which includes $12 million related to Nevada sportsbooks operations for which
BetMGM records on a net basis as BetMGM is considered to be the agent in the Nevada transactions for GAAP purposes. MGM Resorts recorded $17 million of net revenues for Nevada
MGM RESORTS INTERNATIONAL sportsbooks operations during 1Q 2021, which does not include Aria’s sportsbook net revenues
2 Reported as part of the Company’s Adjusted EBITDAR under “Unconsolidated affiliates”
16
3 Refer to “SUPPLEMENTAL DATA – ADJUSTED PROPERTY EBITDAR AND ADJUSTED EBITDAR” table within the Company’s 1Q 2021 earnings releaseTRIPLE NET LEASE REITS & GROUND LEASES
• The Company has rental obligations to the following entities: MGM Growth Properties, the Bellagio BREIT venture and the MGP BREIT
venture (Mandalay Bay and MGM Grand Las Vegas)
• Given the Company’s controlling interest in MGP (42% economic ownership), MGP is consolidated within the Company’s financial statements.
However, the BREIT ventures are not consolidated
• Thus, MGM Resorts’ rent expense associated with the BREIT ventures and other ground leases are expensed within the Company’s
consolidated income statement as part of “General and administrative” expenses
– Recognized on a straight-line basis ($189.6 million in 1Q 2021)
• Additionally, the Company’s income is recognized via the equity method under “Income (loss) from unconsolidated affiliates” ($41.7 million in
1Q 2021) and “Non-operating items from unconsolidated affiliates”(-$14.9 million in 1Q 2021)
– 5% ownership of Bellagio BREIT venture
– 50.1% ownership of MGP BREIT venture through the consolidation of MGP within MGM Resorts financial statements
• Consolidated net income is adjusted to exclude the impact of these items in our Adjusted EBITDAR calculation1
• 1Q 2021 triple net operating lease rent expense on a cash basis:
– MGP: $206.9 million (partially offset by $72.4 million in distributions received from MGP)
– BREIT ventures: $136.0 million
• Our ground lease expenses aggregate to approximately $8 million of rent expense per quarter (~$32 million per year)
MGM RESORTS INTERNATIONAL 1 Refer to “Reconciliation of Net Income (Loss) Attributable to MGM Resorts International to Adjusted EBITDAR” table within the Company’s 1Q 2021 earnings release
17• 1Q 2021 HIGHLIGHTS
• 1Q 2021 FINANCIAL RESULTS
TABLE OF
CONTENTS • BETMGM
• SUPPLEMENTAL
18KEY HIGHLIGHTS FROM BETMGM INVESTOR DAY
$163 $1+ $450
million billion million
Estimated 1Q 2021 net Forecasted 2022 Expected capital consumed in 2021
revenues associated with net revenues associated (2021 highest planned annual cash usage)
BetMGM operations1 with BetMGM operations2
$32 20-25% 30-35%
billion
Long-term total addressable Expected long-term Expected long-term
market (TAM) U.S. market share EBITDA margin
1 Net revenues for 1Q 2021 for the BetMGM joint venture on a GAAP basis was approximately $156 million, which includes $12 million related to Nevada sportsbooks operations for which
MGM RESORTS INTERNATIONAL BetMGM records on a net basis as BetMGM is considered to be the agent in the Nevada transactions for GAAP purposes. MGM Resorts recorded $17 million of net revenues for Nevada
sportsbooks operations during 1Q 2021, which does not include Aria’s sportsbook net revenues 19
2 Refer to “Important Note Regarding BetMGM Financial and Other Information” on slide 2SIGNIFICANT LONG-TERM MARKET OPPORTUNITY
$32 BILLION SPORTS BETTING AND IGAMING TAM IN NORTH AMERICA
TOTAL LONG TERM U.S.
ADDRESSABLE MARKET (“TAM”) ONLINE • ~65% of the adult population
SPORTS
BETTING • Average GGR per adult of ~$90
CANADA
(“OSB”)
$4.4 BILLION
• ~35% of the adult population
U.S.
$32 BILLION
NORTH AMERICAN TAM
U.S. OSB
$14.1
BILLION
iGAMING • Average GGR per adult ~$160
U.S.
iGAMING
$13.4 • ~65% of the adult population1
BILLION
CANADA • Average GGR per adult of ~$65 for
OSB and ~$115 for iGaming
MGM RESORTS INTERNATIONAL 1 Includes OSB and iGaming
20GROWING PRESENCE & BROAD-BASED MARKET ACCESS
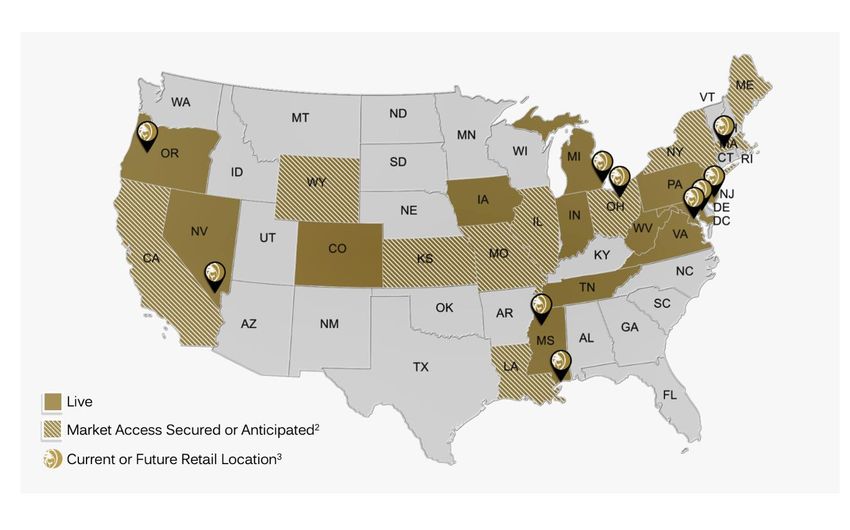
12 20
Active Expected live
jurisdictions jurisdictions in
next 12 months
40% 24
Population with Market
expected access access Live
in next 12 secured or
months1 anticipated2 Market Access Secured or Anticipated2
Current or Future Retail Location3
1 Approximate U.S. adult population with access to OSB and / or iGaming in jurisdictions where BetMGM is expected to be active
MGM RESORTS INTERNATIONAL 2 Includes open license jurisdictions where BetMGM intends to apply for market access 21
3 Future locations at MGM properties subject to enabling legislationPROVEN ABILITY TO WIN IN DIFFERENT MARKETS
MICHIGAN COLORADO NEW JERSEY
Market
Position1
#1 #1 #1
OSB, iGaming, Retail OSB (est.) iGaming
Products
OSB Gaming Poker OSB OSB Gaming Poker
Day-1
Launch
Omni-
channel
Local
Partnerships
MGM RESORTS INTERNATIONAL 1 Based on market share for products listed for last 3-month (L3M) period ended February 2021; CO based on internal estimates
22STRONG MARKET SHARE GAINS CONTINUE IN 1Q 2020
BETMGM’S MARKET SHARE CONTINUES TO GROW DRIVEN BY ONLINE SEGMENTS1
Online Sports Betting* iGaming* All (Online & Retail Sports Betting and iGaming)*
25% February total market
22% share across all active
jurisdictions2
20%
February iGaming market
15%
25% share across all active
jurisdictions2
10%
February OSB market
5% 17% share across all active
jurisdictions2
0%
Feb-20 Mar-20 Apr-20 May-20 Jun-20 Jul-20 Aug-20 Sep-20 Oct-20 Nov-20 Dec-20 Jan-21 Feb-21
MGM RESORTS INTERNATIONAL 1 In markets that BetMGM is active
2 Based on BetMGM revenues as a percentage of state reported revenues in markets where BetMGM is active 23
* December market share includes PA where BetMGM had a partial month of sports betting and iGamingPOISED TO SUSTAIN RAPID GROWTH
MONTHLY GROSS GAMING REVENUE (“GGR”)
✓ Proven ability to launch
1
on day 1
+400%
✓ Platform built to deliver
rapid market rollout
✓ TOP 3 in U.S. OSB2
✓ #1 in U.S. iGaming2
Dec 2019 Mar 2020 Jun 2020 Sep 2020 Dec 2020 Mar 2021
STATE LAUNCHES
WV NV MI CO OR TN PA IA
IN VA
1 Represents approximate increase in March 2021 GGR versus September 2020
MGM RESORTS INTERNATIONAL 2 Measured by GGR for the L3M period ended February 2021 across all U.S. jurisdictions 24POSITIONED TO BE A LONG-TERM LEADER
OVERALL ESTIMATED NATIONAL MARKET SHARE1
35%
30%
COMPETITOR 1
25%
20%
BetMGM
COMPETITOR 2
15%
10%
COMPETITOR 3
COMPETITOR 4
5%
0%
Jan 2020 Feb 2020 Mar 2020 Apr 2020 May 2020 Jun 2020 Jul 2020 Aug 2020 Sep 2020 Oct 2020 Nov 2020 Dec 2020 Jan 2021 Feb 2021
1 Total market share by GGR for retail, OSB and iGaming across all U.S., including jurisdictions where BetMGM is not currently active; internal estimates used where operator-specific
MGM RESORTS INTERNATIONAL results are unavailable
25LEADING RETAIL INTEGRATION & OMNI-CHANNEL OFFERING
35 million+ 100%
M life Rewards of BetMGM players are
Members 10% 44% enrolled in M life
of new BetMGM of new M life players
players in 1Q 2021 BEST LOYALTY PROGRAM in 1Q 2021 were from
were active with BetMGM1
Global Gaming Awards in 6 of the last 7 years
MGM1
MGM RESORTS INTERNATIONAL 1M life players who were active in the 12 months prior to acquisition
26THE OMNI-CHANNEL ADVANTAGE
Non-MGM Sourced
MGM Sourced1 Marketing ROI is
Est. Normalized Avg.
5.4x
157%
higher for MGM-
sourced players2
100% 100%
Value of omni-
channel will increase
28% post-COVID
CPA GGR
1 MGM Sourced players include on-site registrations and other directly attributable marketing sources
MGM RESORTS INTERNATIONAL 2 Marketing ROI defined as GGR per month divided by cost per acquisition (“CPA”)
27
All information presented for 1Q 2021BETMGM’S SUSTAINABLE COMPETITIVE ADVANTAGES
NATIONAL MARKET
ACCESS
• Market access currently
LEADING PRODUCT
AND TECHNOLOGY
MARKET
secured or anticipated in
EFFICIENT PLAYER LEADING
POSITION
24 jurisdictions
• Fully-featured proprietary ACQUISITION AND RETENTION
WITH
Relationship with MGM tech-stack
•
Resorts minimizes cost of
RESPONSIBLE
GAMBLING
SUPERIOR
• Proven capability and • Omni-channel attracts
market access
superiority worldwide and retains players with
• Platform enables B2C
• Relationship with Entain
money-can’t-buy
experiences • Longstanding history in ECONOMIC
STRUCTURE
and B2B entry responsible gambling
provides structural cost
• Award-winning rewards leadership
advantage
program builds loyalty
and provides distinct • Committed to a balanced
competitive advantage approach to growth
• Strategic partnerships • Our goal is to provide
deliver players nationwide players with an
at attractive costs per entertaining and safe
acquisition (“CPA”) gambling experience
MGM RESORTS INTERNATIONAL 28SUPPLEMENTAL • MGM CHINA PROPERTY DATA
29MGM CHINA FINANCIAL INFORMATION UNDER IFRS
Due to the time differences between Macau and the United States, this supplemental information is being provided on behalf
of MGM China for the benefit of MGM China investors
Three Months Ended
March 31
2021 2020
HK$'000 HK$'000
(unaudited) (unaudited)
Revenue
MGM Macau $1,318,121 $1,128,806
MGM Cotai $980,703 $984,255
Total Revenue $2,298,824 $2,113,061
Adjusted EBITDA1
MGM Macau $169,973 $34,121
MGM Cotai ($85,610) ($156,800)
Total Adjusted EBITDA $84,363 ($122,679)
1
Adjusted EBITDA is profit/loss before finance costs, income tax expense/benefit, depreciation and amortization, gain/loss on disposal/write-off of property and equipment, and other assets,
interest income, net foreign currency difference, share-based payments, pre-opening costs and corporate expenses which mainly include administrative expenses of the corporate office
and license fee paid to a related company. Adjusted EBITDA is used by management as the primary measure of the Group’s operating performance and to compare our operating
performance with that of our competitors. Adjusted EBITDA should not be considered in isolation, construed as an alternative to profit or operating profit as reported under IFRS or other
MGM RESORTS INTERNATIONAL combined operations or cash flow data, or interpreted as an alternative to cash flow as a measure of liquidity. Adjusted EBITDA presented in this announcement may not be comparable to
30
other similarly titled measures of other companies operating in the gaming or other business sectors.MGM CHINA FINANCIAL INFORMATION UNDER IFRS
Due to the time differences between Macau and the United States, this supplemental information is being provided on behalf
of MGM China for the benefit of MGM China investors
Three Months Ended
March 31
2021 2020
HK$'000 HK$'000
MGM MACAU (unaudited) (unaudited)
(in thousands, except for percentages and revenue per available room (“RevPAR”))
VIP Table Games Turnover 10,398,589 15,792,808
VIP Gross Table Games Win1 368,985 502,552
VIP Table Games Win Percentage 3.55% 3.18%
Average Daily Gross Win Per VIP Gaming Table 60.6 111.5
Main Floor Table Games Drop 4,672,214 3,413,565
Main Floor Gross Table Games Win1 980,622 744,335
Main Floor Table Games Win Percentage 21.0% 21.8%
Average Daily Gross Win Per Main Floor Gaming Table 50.5 55.0
Slot Machine Handle 3,527,202 3,324,631
Slot Machine Gross Win1 142,756 113,114
Slot Hold Percentage 4.0% 3.4%
Average Daily Win Per Slot 2.4 1.8
Commissions, complimentaries and other incentives1 (307,695) (332,258)
Room Occupancy Rate 81.1% 44.0%
RevPAR 961 881
As of March 31
Gaming Units: 2021 2020
Tables2 287 285
Slot Machines 694 575
1
The total of “VIP gross table games win”, “main floor gross table games win” and “slot machine gross win” is different to the casino revenue because casino revenue is reported net of
MGM RESORTS INTERNATIONAL commissions and certain sales incentives including the allocation of casino revenue to hotel rooms, food and beverage and other revenue for services provided to casino customers on a 31
complimentary basis.
2
Permanent table count as of March 31, 2021 and 2020MGM CHINA FINANCIAL INFORMATION UNDER IFRS
Due to the time differences between Macau and the United States, this supplemental information is being provided on behalf
of MGM China for the benefit of MGM China investors
Three Months Ended
March 31
2021 2020
HK$'000 HK$'000
MGM COTAI (unaudited) (unaudited)
(in thousands, except for percentages and revenue per available room (“RevPAR”))
VIP Table Games Turnover 8,007,850 10,823,869
VIP Gross Table Games Win1 237,200 340,911
VIP Table Games Win Percentage 2.96% 3.15%
Average Daily Gross Win Per VIP Gaming Table 51.2 92.8
Main Floor Table Games Drop 3,427,066 2,628,142
Main Floor Gross Table Games Win1 803,010 713,537
Main Floor Table Games Win Percentage 23.4% 27.1%
Average Daily Gross Win Per Main Floor Gaming Table 41.6 56.4
Slot Machine Handle 3,992,534 3,397,889
Slot Machine Gross Win1 93,604 111,598
Slot Hold Percentage 2.3% 3.3%
Average Daily Win Per Slot 1.5 1.7
Commissions, complimentaries and other incentives1 (289,225) (328,406)
Room Occupancy Rate 47.0% 33.2%
RevPAR 469 585
As of March 31
Gaming Units: 2021 2020
Tables2 265 267
Slot Machines 662 462
1
The total of “VIP gross table games win”, “main floor gross table games win” and “slot machine gross win” is different to the casino revenue because casino revenue is reported net of
MGM RESORTS INTERNATIONAL commissions and certain sales incentives including the allocation of casino revenue to hotel rooms, food and beverage and other revenue for services provided to casino customers on a 32
complimentary basis.
2
Permanent table count as of March 31, 2021 and 2020You can also read


