COMMERCIAL PROPERTY MARKET GERMANY'S TOP 7 CITIES 2017/Q1-4 - NVESTMENT/OFFICE LETTING - blackolive
←
→
Page content transcription
If your browser does not render page correctly, please read the page content below
LOCAL EXPERTISE – ACROSS GERMANY

NVESTMENT/OFFICE LETTING
COMMERCIAL PROPERTY MARKET
GERMANY’S TOP 7 CITIES
2017/Q1-4

                                          WWW.GERMANPROPERTYPARTNERS.DE
LOKALEEXPERTISE
               LOCAL  KOMPETENZ– ACROSS
                                  – DEUTSCHLANDWEIT
                                        GERMANY                                                                                                                                                                                      MARKTBERICHT INVESTMENT/BÜROVERMIETUNG
                                                                                                                                                                                                                                      MARKET SURVEY  INVESTMENT/OFFICE LETTING 2017/Q1-4

ABOUT US
GERMAN PROPERTY PARTNERS
Each of us being a leading commercial real estate company           We have founded German Property Partners with the aim
in its respective region, we have joined together to form a         of providing our special services in all of Germany’s major
Germany-wide real estate network. We are five strong                real estate centres. That way, whatever your commercial
partners.                                                           real estate requirements, wherever you are in Germany,
                                                                    you can obtain your advice from a single provider, and that
In Northern Germany, Grossmann & Berger offers its real             is us. Via our network and thanks to our respective market
estate services out of its locations in Hamburg and Berlin,         positions, we can offer you outstanding local knowledge                LOCAL EXPERTISE – ACROSS GERMANY
while ELLWANGER & GEIGER Real Estate covers Southern                and preferential market access throughout Germany.
Germany from its bases in Stuttgart and Munich. ANTEON                                                                                     GERMAN PROPERTY PARTNERS
Immobilien is the firm to contact about property matters            The many years of service our employees have put in with
in and around Düsseldorf, while GREIF & CONTZEN Immo-               us, and the affiliation of Grossmann & Berger and ELL-                 Dear Readers,
bilien are your eyes and ears in the metropolitan area of           WANGER & GEIGER Real Estate with reputable regional
Cologne and Bonn. blackolive guarantees full market cov-            banks, make German Property Partners a reliable partner                Property business professionals will long remember the                                   The process of preparing and interpreting the data was
erage in the Frankfurt region.                                      for long-term collaboration in the fields of commercial real           year 2017. This is because office markets in Germany’s                                   made possible thanks to a partnership between four of the
                                                                    estate and finance.                                                    top 7 locations posted their best result in over ten years                               leading service providers specialized in commercial prop-
                                                                                                                                           to close the year on an all-time high. The investment                                    erties based in north, central and south Germany - the
                                                                                                                                           markets in the top 7 cities likewise returned results that                               nationwide network German Property Partners (GPP). Our
                                                                                                                                           outstripped figures seen in recent years, so that the final                              knowledge of local markets is as broad as it is deep, giving
 Partner                                                                                                                                   total was second only to that posted in 2007.                                            us access to data on the entire market, the top 7 locations
                                                                                                                                                                                                                                    and the sub-markets within each one.
Grossmann & Berger                            ANTEON                                        GREIF & CONTZEN                                This market survey provides a review of the year 2017 as
A real estate consultant with expe-           ANTEON is an owner-managed real               This owner-managed service company             it played out on Germany’s top 7 markets. In addition to                                 The present survey offers you a general view of the market.
rience stretching back for over 80 years,     estate consultancy firm that specializes      has been providing consultancy, evalu-         drawing comparisons between the top 7 markets, we offer                                  We would be happy to hold personal talks with you and
Grossmann & Berger is one of the leading      in brokering lets and investments in com-     ation, brokering and management ser-           a detailed look at the investment and office letting markets                             answer your specific questions about property matters.
service providers for the sale and letting    mercial, logistics and residential prop-      vices for commercial and residential           in Hamburg, Berlin, Düsseldorf, Cologne, Frankfurt/Main,
of commercial and residential real estate     erties. In addition, as one of the market     properties in the metropolitan region of       Stuttgart and Munich.                                                                    Guido Nabben
in Northern Germany, and is an affiliate in   leaders, ANTEON offers property mar-          Cologne | Bonn for over 40 years, and is ex-                                                                                            Spokesman for German Property Partners
the HASPA-group of companies.                 keting, project support and research ser-     perienced in the entire value chain of real    TOP 7............................................................................... 4
                                              vices.                                        estate transactions.                           HAMBURG....................................................................... 8
                                                                                                                                           BERLIN.......................................................................... 10
blackolive                                    ELLWANGER & GEIGER                                                                           DÜSSELDORF................................................................ 12
blackolive is an owner-managed real           ELLWANGER & GEIGER Real Estate offers                                                        COLOGNE....................................................................... 14
estate consultancy firm that focuses          a full range of services in connection with                                                  FRANKFURT.................................................................. 16
on office letting and investment. The         commercial property assets. With the re-                                                     STUTTGART................................................................... 18
managing directors both have more             sources of the parent company’s private                                                      MUNICH......................................................................... 20
than 26 years of experience and stand         banking business, this service provider
for an in-depth understanding of the          has over 100 years of experience.
market.

                                                                                                                                                                                                                                                                                              3

                                                                                                                                                                                                                                                                    WWW.GERMANPROPERTYPARTNERS.DE
LOCAL EXPERTISE – ACROSS GERMANY MARKET SURVEY INVESTMENT/OFFICE LETTING 2017/Q1-4
TOP 7
FACTS & FIGURES 2017/Q1-4 KEY FIGURES 2017/Q1-4
Investment: strongest buyer groups by location Office letting: strongest industries by location
HAMBURG BERLIN
(share of take-up of space) (share of transaction volume)
640,000 m² (+16 %) 900,000 m² (+10 %)
26.00 €/m² (0 %) 30.00 €/m² (+9 %)
Hamburg 36 % Open-end/specialized funds Hamburg 16 % IT & telecommunication 15.20 €/m² (-2 %) 19.50 €/m² (+21 %)
4.3 % (-0.8 %-Pkt.) 2.2 % (-1.5 pp)
Berlin 27 % Pension schemes Berlin 23 % Public administration € 3.60bn (-20 %) € 7.3bn (+45 %)
2.90 % (-0.4 %-Pkt.) 3.00 % (-0.3 pp)
Düsseldorf 31 % Asset managers Düsseldorf 12 % Industry and Trade
Cologne 30 % Other Funds Cologne 19 % Public administration, associations
Frankfurt 29 % Open-end/specialized funds Frankfurt 24 % Financial services DÜSSELDORF
358,700 m² (+8 %)
Stuttgart 24 % Open-end/specialized funds Stuttgart 40 % Industry 27.00 €/m² (+2 %)
15.35 €/m² (+7 %)
Munich 51 % Open-end/specialized funds Munich 20 % Industry 8.4 % (-1.5 pp)
€ 2.96bn (+13 %)
3.40 % (-0.4 pp)
Key figures top 7
Hamburg Berlin Düsseldorf Cologne Frankfurt Stuttgart Munich Top 7
Take- up of space
640,000 900,000 358,700 310,000 729,100 270,000 877,600 4,085,400
[m²]
Year-on-year change [%] +16 +10 +8 -30 +30 -38 +15 +5
COLOGNE FRANKFURT
Average rent 310,000 m² 729,100 m²
15.20 19.50 15.35 13.70 20.30 13.70 16.90 - (-30 %) (+30 %)
[net €/m²/mth]
21.50 €/m² (0 %) 39.75 €/m² (+3 %)
Year-on-year change [%] -2 +21 +7 -3 +13 +6 +9 - 13.70 €/m² (-3 %) 20.30 €/m² (+13 %)
3.6 % (-1.0 pp) 8.7 % (-1.8 pp)
Premium rent
26.00 30.00 27.00 21.50 39.75 24.30 35.00 - € 2.30bn (+28 %) € 6.72bn (+3 %)
[net €/m²/mth]
3.70 % (-0.1 pp) 3.30 % (-0.6 pp)
Year-on-year change [%] 0 +9 +2 0 +3 +6 -1 -
Vacant space
580,200 430,000 630,000 280,000 1,005,700 167,000 580,000 3,672,900
[m²]
Year-on-year change [%] -15 -39 -16 -22 -19 -24 -31 -24
Vacancy rate
4.3 2.2 8.4 3.6 8.7 2.1 2.5 4.1
[%] STUTTGART MUNICH
Year-on-year change 270,000 m² (-38 %) 877,600 m² (+15 %)
-0.8 -1.5 -1.5 -1.0 -1.8 -0.7 -1.1 -1.3
[percentage points (pp)] 24.30 €/m² (+6 %) 35.00 €/m² (-1 %)
13.70 €/m² (+6 %) 16.90 €/m² (+9 %)
Transaction volume
3,600 7,300 2,960 2,300 6,716 1,200 5,872 29,948 2,1 % (-0,7 pp) 2.5 % (-1.1 pp)
[m €]
€ 1.2bn (-34 %) € 5.9bn (-9 %)
Year-on-year change [%] -20 +45 +13 +28 +3 -34 -9 +4 3.50 % (0% pp) 3.00 % (-0.1 pp)
Share of asset class
68 71 81 45 91 78 59 72
Office [%]
Prime yield
2.90 3.00 3.40 3.70 3.30 3.50 3.00 3.26
Office [%]
Year-on-year change [pp] -0.40 -0.30 -0.40 -0.10 -0.60 0 -0.10 -0.27
KEY FIGURES OFFICE LETTING/INVESTMENT:
Prime yield
2.90 2.90 3.50 3.20 3.40 3.10 2.45 3.06
Commercial premises [%] Take-up of space (year-on-year change) Vacancy rate (year-on-year change)
Year-on-year change [pp] -0.40 -0.20 -0.10 -0.40 -0.10 0 -0.15 -0.19
Premium rent (year-on-year change) Transaction volume (year-on-year ch.)
Prime yield
4.60 4.90 4.75 4.70 4.80 4.50 4.60 4.69
Logistics [%] Average rent (year-on-year change) Prime yield office (year-on-year ch.)
Year-on-year change [pp] -0.30 -0.20 -0.25 -0.30 -0.30 -0.60 -0.40 -0.34
4 5
WWW.GERMANPROPERTYPARTNERS.DE
LOCAL EXPERTISE – ACROSS GERMANY MARKET SURVEY INVESTMENT/OFFICE LETTING 2017/Q1-4
TOP-7
INVESTMENT OFFICE LETTING
At the close of 2017 the volume of investment transac- INVESTORS AND VENDORS At the close of the year 2017 a new record take-up of with appreciably reduced amounts of vacant space. The
tions in commercial properties (excluding buy-to-let res- International investors continued to take a great interest 4.1m m² was announced for Germany’s top 7 office other top 7 cities saw vacancies drop by between 22 % Co-
idential) located in Germany’s top 7 cities had reached a in commercial properties located in Germany’s top 7 cities letting markets. This result was the best in over ten logne) and 15 % (Hamburg). Some 260 office new builds
total of €29.9bn. Compared with the prior year’s €28.8bn, and, having increased their activities somewhat, these years and for the first time in history the four-million are scheduled for completion this year and next, offering
this represented an increase of 4 %. Not only did the top players accounted for nearly half of the total volume mark was passed. a total rental space of around 2.5m m². A majority of this
7 cities surpass the prior year’s volume of transactions, traded. Berlin remained the hot spot for international space has, however, been pre-let or is being constructed
but the result was also the second highest since 2007. capital, where foreign investors accounted for 73 % of TAKE-UP OF SPACE for an owner-occupier.
total trades. Year on year portfolio sales in the top 7 cities By the end of 2017, office-letting in Frankfurt had reached
TRANSACTION VOLUME accounted for the same proportion of transactions by an all-time high of 729,100 m², which was 30 % above OUTLOOK
At the end of 2017 Berlin posted the biggest increase in value, at 23 % of the total. the figure for 2016 and on a par with the property mar- In view of the economic stability, the market for office let-
the volume of transactions, which rose by 45 % to €7.3bn. ket’s high-water mark in 2000. In Hamburg the take-up of tings in Germany will continue to boom in 2018. However, it
Five transactions, each priced at over €200m, were partly YIELDS space rose by 16 % in 2017, reaching a new record level is to be expected that total take-up of space will be lower
behind this result, the capital city’s second highest ever. In view of the mismatch between supply and demand, of 640,000 m². Year on year 15 % more office space was than in 2017 because the shortage of available property
The “Sony Center” on Potsdamer Platz was one such sale; the prime net yield continued its downward slide across taken up in Munich, leading to a total of 878,000 m². The will become more acute. In view of burgeoning demand
a consortium headed by Oxford Properties paid €1.1bn for all asset classes and top 7 cities. The lowest prime net office market in Berlin surged forward to the best result and the low rates of completion scheduled for this year,
this complex alone. In 2017 it was the biggest single com- yield was the 2.45 % noted for commercial buildings in of the 7 cities and total take-up of 900,000 m², (+10 %) to speculative new builds would possibly serve to steady
mercial investment transaction in any of the top 7 cities. Munich, followed by 2.90 % for commercial buildings in place ahead of Munich. The year-end total for Düsseldorf office rents but would not ease the situation in the short
Cologne also set a new record with year-on-year growth Hamburg and Berlin. Yields on offices ranged from 2.90 % was 358,700 m² of office space taken up. This translated to medium term.
of 28 %. The transaction volume of €2.3bn was some in Hamburg to 3.70 % in Cologne. The most expensive city into an 8 % higher result than in 2016. In Cologne, however,
20 % higher than the previous record set in 2015. A new for logistics properties was Stuttgart, where the yield was the take-up of office space fell by 30 % to 310,000 m², Clients in Cologne, Düsseldorf and Frankfurt are still
record was also set in Düsseldorf, where the sales of com- 4.50 %. largely due to outlier transactions in the record year of looking for large suites of offices, which may result in
mercial properties reached a total of €3.0bn by the end 2016. In Stuttgart the take-up of office space declined by agreements in 2018. Considering that supply is becoming
of the year. The result in Frankfurt rose year on year by OUTLOOK 38 % year on year to 270,000 m². ever shorter, it is unlikely that this year’s take-up totals in
a moderate 3 % to €6.7bn. Despite a 9 % drop compared In 2018 commercial properties in Germany’s top 7 cities the top 7 office-letting locations will match the record re-
with 2016, sales in Munich totalled €5.9bn. With a trans- are set to remain a good investment. However, this pre- In 2017 the operators of co-working space or business sults of 2017. Nevertheless, the office-letting business is
actions result of €3.6bn, Hamburg slipped 20 % short of supposes a stable, predictable environment on the capital centres were very active in the pursuit of new premises set to have a very good year because the overall stability
the record €4.5bn posted in the prior year. Stuttgart gen- markets and on the political stage. In view of the re- to rent. In almost all the top 7 cities these enterprises of the economy and a resilient labour market will continue
erated a transaction volume of €1.2bn and thus attracted markably high demand and the glut of cash for investment posted rising shares of total take-up. The industry’s total to fuel demand for office space.
much less investment activity than in prior years. it is unlikely that there will be any great atmospheric of 214,000 m² represented some 5 % of the total take-up
changes this year on the property investment markets of space or nearly three times the amount rented in 2016.
in the top 7 cities. Due to the shortage of real estate, the
transaction volume is not expected to be as high in 2018. RENTS
As a result of tight supply and a shortage of vacant space,
almost all the top 7 cities reported rising office rents in
2017. The biggest leap was seen in Berlin, where the av-
Transaction volume top 7 Transaction volume by asset classes top 7 erage rent rose by 21 % to €19.50/m²/month and the Take-up of space top 7
premium rent rose by 9 %, thus reaching €30.00/m²/
(in €bn) month for the first time. Two other factors, apart from the (in 000s m2, incl. owner-occupiers)
5-year average (2013-2017): Logistics | 2 % Other | 1 % mismatch between supply and demand, are driving up
ca. €25.4bn office rents: owners and landlords are passing on to their
Commercial premises | 3 %
Undeveloped land tenants both the ever higher prices for building land as 5-year average (2013-2017):
well as the rising construction costs. ca. 3.5 million m2
6%
Retail
8% AVAILABLE AND VACANT SPACE
With the total stock of office space including sub-let
Hotel 8%
72 % Office space standing at 90.7m m², the reserve of available
space in the top 7 cities has contracted further to total
a mere 3.7m m² at the end of the 4th quarter. This trans-
lates into 4.1 % of the total stock of office space. The
17.3 21.8 29.3 28.8 29.9 26.0 most dramatic decline in office space available at short
2013 2014 2015 2016 2017 2018
notice was seen in Berlin, where supply contracted by 2.9 2.9 3.5 3.9 4.1 3.5
39 %. Munich (-31 %) and Stuttgart (-24 %) also struggled 2013 2014 2015 2016 2017 2018
6 7
WWW.GERMANPROPERTYPARTNERS.DE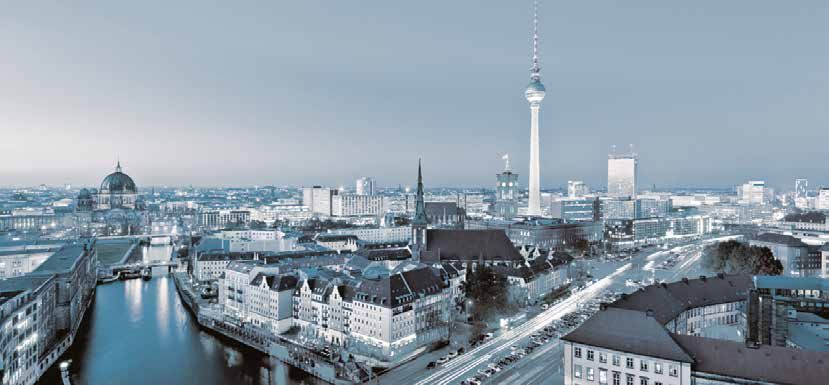
LOCAL EXPERTISE – ACROSS GERMANY MARKET SURVEY INVESTMENT/OFFICE LETTING 2017/Q1-4
OFFICE LETTING
HAMBURG
The take-up of office space in Hamburg set a new record. AVAILABLE AND VACANT SPACE
In the year 2017 some 640,000 m² of office space was As had been expected, the amount of space standing
let and thus 16 % more than in the year before. This ap- empty was further reduced. By the end of 2017 the va-
preciable increase is a reflection of the dynamic state of cancy rate had sunk to the new record low of 4.3 %. A mere
Hamburg’s office-letting market. 580,000 m² of space was available to new tenants within a
period of three months. 32 developments are likely to add
TAKE-UP OF SPACE some 160,000 m² of space in 2018, followed in 2019 by a
In 2017 clients seeking office suites offering 5,000 m² or further 167,000 m² in 24 developments.
more generated 26 % of total take-up, almost the same
proportion as in 2016. Overall, 13 contracts for large OUTLOOK
premises were signed. The three biggest contracts of The positive economic and job market forecasts indicate
the year included two rental agreements for new builds, that demand for office space will increase. Nevertheless,
when Olympus Deutschland signed for 34,500 m² (Wen- the growing shortage of suitable offices makes a new
denstrasse 14-18, City South) and Gruner + Jahr signed take-up record unlikely. In all likelihood the take-up of
INVESTMENT for 34,000 m² (Am Hannoverschen Bahnhof, HafenCity); space will dip back below the 600,000 m² mark in 2018.
the University of Hamburg took 19,700 m² in an existing
HAMBURG building (Überseering 35, City North). Some 55 % of the
space taken up and 52 % of the agreements signed in 2017
Year on year the volume of investments in commercial INVESTORS AND VENDORS related to premises in the central sub-markets City, City
properties in Hamburg fell by a fifth below the record In 2017 open-end/specialist funds were the most active South and HafenCity. As before, Hamburg City district was TOP 3 SUB-MARKETS (take-up of space / average rent)
result of 2016 (€4.5bn) to close the year 2017 at €3.6bn. buyers of Hamburg properties and responsible for 36 % top of the league.
The number of properties traded also fell; a decline from of the total traded volume (some €1.3bn). Asset/property CITY / 153,000 m² / €19.50/m²/month
174 to 125 translates into a dip of 28 %. portfolio managers were the biggest single group of RENTS CITY SOUTH/ 115,300 m² / €12.40/m²/month
sellers, with a share of 27 % (€968m). At the close of the year the premium rent was unchanged HAFENCITY / 85,100 m² / €19.60/m²/month
INVESTMENT PROPERTIES at €26.00/m²/month. The average rent softened slightly
The 4th quarter of 2017 was the year’s strongest, with a total OUTLOOK and fell from €15.50 in 2016 to €15.20/m²/month. In the TOP 3 CONTRACTS
of €1.3bn. This was primarily due to the portfolio transaction in In view of the unwillingness of owners to sell their com- various sub-markets considerable variations in rentals
which Signa Holding bought a total of five properties from RFR mercial properties in Hamburg, 2018 is unlikely to set were observed, generally depending on the quality of 1. OLYMPUS DEUTSCHLAND GMBH
Holding. Two of the properties in the portfolio are in Hamburg’s any new records. Nevertheless, several large trades are the space on offer. Year on year the average rents in the Wendenstrasse 14-16 / ca. 34,500 m²
City district and the selling prices were each in the treble-digit in the pipeline, such as the “Hanse-Viertel”, the “Wandel- central sub-markets of City and City South stayed the 2. GRUNER + JAHR GMBH
millions bracket. The transaction involved the two office and halle” concourse in the main station or the new Olympus same. In HafenCity they rose by 16 % due to numerous lets Am Hannoverschen Bahnhof / ca. 34,000 m²
commercial buildings named “Arkadenhof” (Neuer Wall/Jun- headquarters. For this reason 2018 is expected to return a in new builds. 3. UNIVERSITY OF HAMBURG
gfernstieg) and “Kaufmannshaus” (Bleichenbrücke 10/Grosse transaction total higher than the ten-year average volume Überseering 35 / ca. 19,700 m²
Bleichen). Other transactions with price tags in the three-figure of €2.8bn.
millions were already announced in earlier quarters: Wenaas-
gruppen paid Azur Property Investments about €200m for the Transaction volume Hamburg Take-up of space Hamburg Rents Hamburg
“Radisson Blu Dammtor” (hotel, Marseiller Strasse 2, Alster
West); Patrizia paid Orion Capital Managers around €175m for (in €bn) (in 000s m2, incl. owner-occupiers) (net in €/m2/mth)
the “HafenCity Gate” (office , Am Sandtorkai 74-77, HafenCity)
and the “Kaisergalerie” (office and commercial building, 5-year average (2013-2017): premium rent
Grosse Bleichen 23-27, City) was sold for some €170m by ca. €3.7nb
Quantum Immobilien and the alstria office REIT to the Swiss 5-year average (2013-2017):
ca. 539,000 m2
investor in foreign real estate Anlagestiftung für Immobilien- 26.00 26.00
24.50 25.00
anlagen im Ausland. In 2017 the most desirable class of asset 24.00 24.00
was, as in the prior year, office properties, which accounted for
68 % (€2.4bn) of the total traded volume.
average rent
Prime yields on all classes of asset continued their downward
slide. At the end of the 4th quarter the prime yield on office 15.50 15.20
14.00 14.50 14.50
and commercial buildings fell below the three-per-cent 14.00
threshold for the first time, to 2.9 %. The premium yield on 2.8 3.7 4.0 4.5 3.6 3.0 440 525 540 550 640 550
logistics properties fell to 4.6 %. 2013 2014 2015 2016 2017 2018 2013 2014 2015 2016 2017 2018 2012 2013 2014 2015 2016 2017
8 9
WWW.GERMANPROPERTYPARTNERS.DE
LOCAL EXPERTISE – ACROSS GERMANY MARKET SURVEY INVESTMENT/OFFICE LETTING 2017/Q1-4
OFFICE LETTING
BERLIN
Year on year take-up of space in Berlin offices rose by AVAILABLE AND VACANT SPACE
10 % thanks to a high number of agreements to rent large Empty space stood at a record low of 2.2 % or 430,000 m²,
amounts of space and construction starts for owner-oc- which was 39 % below the level noted in the prior year.
cupiers; the total of 900,000 m² set another new record. Berlin therefore has almost no space left to rent, which
The three biggest rental or owner-occupier transactions makes life difficult for companies that wish to move
alone accounted for take-up of 129,000 m². premises or expand their offices. Many firms that need
larger amounts of space are turning to new build develop-
TAKE-UP OF SPACE ments. This trend is leading to a further rise in new space
By the end of the year 32 agreements involving more being built, but the effects will not be very noticeable until
than 5,000 m² had been recorded, and eleven for more 2019. In 2018 some 294,000 m² of office space will be
than 10,000 m² of space, including the purchase of completed, in 2019 the scheduled volume is 417,000 m².
the former Vattenfall headquarters (about 47,000 m²,
Puschkinallee 52, Periphery South) which the new OUTLOOK
owner, the Federal real estate corporation Bundesan- In the medium to long term more space on the market will
INVESTMENT stalt für Immobilienaufgaben, will use itself, and the two ease the situation for tenants and keep rents reasonable.
large premises let to Zalando (about 45,000 m² at Tama- In 2018 take-up is expected to total some 750,000 m² be-
BERLIN ra-Danz-Strasse 7, Friedrichshain, and about 42,000 m² cause so little space is available on the market.
at Koppenstrasse 8, Friedrichshain). The most popular
The volume of investment transactions in commercial INVESTORS AND VENDORS sub-market was Friedrichshain with a share of some
properties rose by 45 % year on year to a total for 2017 Due to the sale of the “Sony Center” to a pension fund, 14.9 %, followed by Periphery South (about 12.4 %) and TOP 3 SUB-MARKETS (take-up of space / average rent)
of €7.3bn. This was the second highest total ever seen, buyers belonging to this sector accounted for the lion’s Kreuzberg (about 11.9 %). For the first time ever, the top 3
topped only by the €7.8bn posted in 2015. share of the traded volume, equivalent to 27 %. The selling sub-markets included neither Mitte nor Mitte 1a, thus un- FRIEDRICHSHAIN / 134,100 m² / €25.50/m²/month
side of the market was dominated by project developers/ derlining the shift in take-up locations. Public adminis- PERIPHERY SOUTH / 111,600 m² / €13.20/m²/month
INVESTMENT PROPERTIES builders who accounted for 18 %, and pension funds which tration/federations/social facilities accounted for 23 % of KREUZBERG / 107,100 m² / €20.20/m²/month
In 2017 more than 130 sales of commercial properties comprised 17% - likewise a result of the “Sony Center” the total take-up of space, dislodging the information and
were reported in Berlin. The three biggest sales were the transaction. The proportion of international investors rose communications sector from the top slot it held in the year TOP 3 CONTRACTS
“Sony Center”, sold in the 3rd quarter by the National pen- slightly from 64 % to 73 %. before.
sions Service for around €1.1bn to a consortium led by 1. FEDERAL INSTITUTE FOR REAL ESTATE MANAGEMENT
Oxford Properties (offices, Potsdamer Platz, Potsdamer/ OUTLOOK RENTS Puschkinallee 52 / ca. 47,000 m²
Leipziger Platz sub-market), and the two Axel-Springer The volume of transactions forecast for 2018 is around Within the space of a year the average rent rose by 21 % 2. ZALANDO
buildings. One was the new build “Axel-Springer Medi- €5.0bn, because no-one expects to see the same level of to the new record level of € 19.50/m²/month. The premium Tamara-Danz-Strasse 7 / ca. 45,000 m²
encampus” sold in the 3rd quarter by Axel Springer for big-ticket trades as 2017. rent was 9 % higher and its new level of € 30.00/m²/month 3. ZALANDO
around €425m to the Norwegian Government Pension was last seen in 2000. Koppenstrasse 8 / ca. 42,000 m²
Fund Global (offices, Axel-Springer Strasse, Mitte 1a sub-
market) and the “Axel-Springer-Passage” (offices, Zim-
merstrasse, Mitte 1a sub-market) that changed hands for Transaction volume Berlin Take-up of space Berlin Rents Berlin
€330m in the 3rd quarter and is now owned by Blackstone.
(in €bn) (in 000s m2, incl. owner-occupiers) (net in €/m2/mth)
As in previous years office properties were the dominant premium rent
asset class on the market, accounting for a share of 71 %
5-year average (2013-2017): 30.00
(about €5.2bn); hotels followed with 11 % of the market ca. 736,200 m2
(€780m) and retail with about 8 % (€584m). The proportion 27.50
of portfolio sales rose slightly from 29 % to 32 %. 5-year average (2013-2017):
ca. €4.8bn
24.00
The prime net yield on office properties fell year on year by 22.00 22.00 22.50
average rent
0.3 percentage points to an all-time low of a mere 3.0 %.
In the case of commercial buildings a decline of 0.2 per- 19.50
centage points brought the yield down to 2.9 %.
16.10
14.90
13.20 13.20
3.4 4.0 7.8 5.0 7.3 5.0 521 630 810 820 900 750 12.30
2013 2014 2015 2016 2017 2018 2013 2014 2015 2016 2017 2018 2012 2013 2014 2015 2016 2017
10 11
WWW.GERMANPROPERTYPARTNERS.DE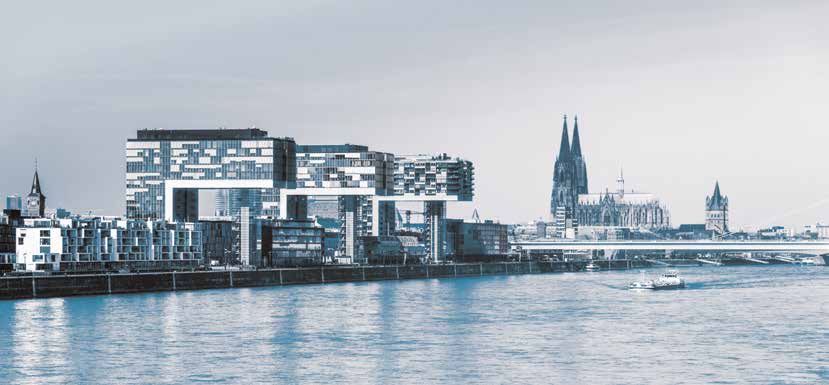
LOCAL EXPERTISE – ACROSS GERMANY MARKET SURVEY INVESTMENT/OFFICE LETTING 2017/Q1-4
OFFICE LETTING
DÜSSELDORF
In 2017 the office market in Düsseldorf continued its New building developments in 2017 totalled 105,000 m²,
upward trajectory. Over the past twelve months let- but most of the space has already been let. The new of-
tings rose to a total of 358,700 m². The result is some 8 % fices are spread over 11 development projects. Eight new
higher than in 2016, when about 330,800 m² of space was build projects are in the pipeline for 2018 (74,000 m²) and
let to new tenants. the same number is due in 2019 (127,000 m²); here too
future tenants have reserved a large proportion of the
TAKE-UP OF SPACE space.
Once again, the most popular sub-market was City, where
82,200 m² of space was taken up. The left bank district OUTLOOK
Linksrheinisch/Seestern was a close second with about Düsseldorf continues to be a very popular city for office
78,800 m². Third-placed Kennedydamm/Derendorf sub- users. Good economic growth will be reflected in the
market totalled around 43,900 m². take-up of space in 2018. Some clients are still in the
market for more than 10,000 m² of office premises, so that
Industrial and trading firms were the biggest single group the total letting result for 2018 could well be similar to that
INVESTMENT of clients for Düsseldorf office space in 2017, renting returned in 2017.
about 44,700 m². Two agreements for large amounts of
DÜSSELDORF space in new developments brought the total for banks
and financial services to about 39,700 m².
A new record result was posted for Düsseldorf in 2017. OUTLOOK
The year closed with sales of commercial real estate It is to be assumed that investor demand for properties RENTS TOP 3 SUB-MARKETS (take-up of space / average rent)
valued at some €3.0bn. The volume of transactions in Düsseldorf will remain high, even if the low yields are Compared with the prior year the average rent rose by
surpassed the previous two best marks, beating last unlikely to encourage record levels of trading. Some new 95 cents to €15.35/m²/month. The premium rent, which CITY / 82,200 m² / €15.10/m²/month
year’s figure by 13 % and the previous record of 2015 developments will come onto the market in 2018, offering had appeared settled at a high level, actually increased SEESTERN/LEFT BANK OF THE RHINE/ 78,800 m² / €14.20/m²/month
by 8 %. The biggest transaction of the year involved the potential buyers the opportunity to sign forward deals or slightly. From €26.50/m²/month at the end of 2016 it has KENNEDYDAMM/DERENDORF / 43,900 m² / €17.90/m²/month
Vodafone Campus, which AGC Equity Partners sold in make commitments. Portfolio adjustments provide other crept up to €27.00/m²/month.
the 4th quarter to Mirae Asset Global Investments for investment alternatives; in 2017 transactions of this kind TOP 3 CONTRACTS
some €280m. Over the course of the year the prime net comprised an appreciable slice of total turnover. As in pre- AVAILABLE AND VACANT SPACE
yields in Düsseldorf softened further, slipping to 3.40 % vious years, the two options just named will probably drive Year on year the amount of space standing empty fell by 1. HSBC TRANSACTION SERVICES GMBH
on office properties and 3.50 % on commercial buildings. investment turnover in 2018 to similarly high levels. about 120,000 m² to some 630,000 m². This translates into Hansaallee 1-3 / ca. 20,100 m²
a vacancy rate of 8.4 % based on a slightly reduced total 2. BANKHAUS LAMPE
INVESTMENT PROPERTIES stock of office space of around 7.5m m². Schwannstrasse 10 / ca. 13,000 m²
Office properties were the most popular investments in 3. BERUFSGENOSSENSCHAFT HOLZ UND METALL
Düsseldorf, where they accounted for a share of 81 % and Arcadiapark / ca. 11,200 m²
a total of some €2.4bn. Building land followed with 5 %
(about €154m), retail properties with 5 % (about €136m)
and mixed use properties accounted for 4 % (about Transaction volume Düsseldorf Take-up of space Düsseldorf Rents Düsseldorf
€133m). Hotels comprised 3 % of the market (about €77m).
(in €bn) (in 000s m2, incl. owner-occupiers) (net in €/m2/mth)
INVESTORS AND VENDORS
Opportunity and equity funds were the biggest vendors 5-year average (2013-2017):
ca. €2.4bn premium rent
of the year as they took advantage of the fact that in-
vestors were willing to pay high prices to sell properties 5-year average (2013-2017):
ca. 338,900 m2 27.50 27.00
26.00 26.50
for €806m, which translated into 27 % of the transaction 26.00 26.00
volume. Asset managers were the most active group of
buyers. They spent about €911m on properties. That is
equivalent to 31 % of the market. Last year foreign in-
vestors remained very much in evidence in Düsseldorf. By
average rent
the end of the year their share of total trades had reached
€1.4bn (49 %). 15.25 15.35
14.90 14.40
14.10 13.80
1.8 1.9 2.7 2.6 3.0 2.5 347 238 420 331 359 400
2013 2014 2015 2016 2017 2018 2013 2014 2015 2016 2017 2018 2012 2013 2014 2015 2016 2017
12 13
WWW.GERMANPROPERTYPARTNERS.DE
LOCAL EXPERTISE – ACROSS GERMANY MARKET SURVEY INVESTMENT/OFFICE LETTING 2017/Q1-4
OFFICE LETTING
COLOGNE
In 2017 total turnover of space was some 310,000 m². amount taken up in a year. The vacancy rate has slumped
Compared with the record set in 2016 this total is some to 3.6 %. Around 95,000 m² of new office space was com-
30 % lower but is nevertheless the third-highest result of pleted in 2017, the figure for 2018 is likely to be some
the past ten years. 80,000 m².
TAKE-UP OF SPACE OUTLOOK
The two biggest agreements of the year were the The strong economic upturn is pushing demand for office
18,800 m² rental by the Federal Office for Family and space. A large number of clients are seeking space in
Social Affairs (BAFZA) at Von-Gablenz-Strasse 2-6 and Cologne ranging from thousands to tens of thousands
the construction start of new headquarters for the own- of square metres and contracts could be signed in 2018
er-occupier STRABAG AG. This building will offer some - provided suitable premises in existing buildings or pro-
17,100 m² (Siegburger Strasse 241). Both properties are jected new-builds can be found. Overall, a total take-up
located in Cologne-Deutz, and this district accordingly of 300,000 m² once again seems to be attainable in 2018.
gained a 19 % share of the total market in 2017 to lead
INVESTMENT the ranking of sub-markets. Federations, associations
and public facilities were behind about 19 % of the total
COLOGNE take-up of space.
A transaction volume totalling €2.3bn makes 2017 a new “specialist funds” because, e.g., they are subject to foreign RENTS
record year for investments in commercial properties in regulations. Family offices and private investors were the The average weighted rent came to €13.70/m²/month. This TOP 3 SUB-MARKETS (take-up of space / average rent)
Cologne. The result surpassed that of 2015, the previous biggest sellers on the market. They accounted for about is some 3 % lower than the figure in 2016, largely because
high-water mark, by more than 20 %. 16 % of the total volume of transactions. fewer agreements for large amounts of expensive space DEUTZ / 57,000 m² / €15.50/m²/month
were signed. Compared with 2015, however, there has CBD NORTH / 27,000 m² / €15.00/m²/month
INVESTMENT PROPERTIES No reduction in demand for investment properties in 2018 been a rise of 10 %. In the premium segment, several con- MÜLHEIM / 23,000 m² / €10.50/m²/month
Six trades had price tags in the three-figure millions. The is foreseeable. The critical parameter remains the amount tracts were signed for rentals above the current premium
city centre “Gerling Quarter” (Christophstrasse, Hilde- of property on the market. The growing trend towards rent of €21.50/m²/month, the highest being a rent of TOP 3 CONTRACTS
boldplatz) was sold to Quantum and Proximus for some cashing in trading profits and re-structuring portfolios €26.50/m²/month.
€200m. Tristan Capital and the developer Concepta could lead to more properties on offer. In addition, devel- 1. FEDERAL OFFICE FOR FAMILY AND SOCIAL AFFAIRS (BAFZA)
Projektentwicklung paid an estimated €150m for the opment sites offer potential trades, so that a transaction AVAILABLE AND VACANT SPACE Von-Gablenz-Strasse 2-6 / ca. 18,800 m²
“DuMont Carré” (Breite Strasse), an inner-city shopping volume in the region of €2.0bn is within the range of pos- In 2017 there was a further decline in the amount of space 2. STRABAG AG (OWNER-OCCUPIER)
centre with a sales area of about 20,000 m². Gerchgroup sibility in 2018. available in Cologne city centre. In several popular central Siegburger Strasse 241 / ca. 17,100 m²
bought a large development site in Cologne-Mühlheim sub-markets, such as the Rings, MediaPark and Deutz 3. DESIGN OFFICES
(Deutz-Mühlheimer-Strasse); here too the price paid is district, there was less empty space than the average Untersachsenhausen 17-27 / ca. 9,000 m²
thought to be €150m.
Year on year offices accounted for a smaller proportion of Transaction volume Cologne Take-up of space Cologne Rents Cologne
total trades, closing at some 45 %. More retail properties
were traded, increasing their share of the market to 20 %. (in €bn) (in 000s m2, incl. owner-occupiers) (net in €/m2/mth)
Building complexes and property portfolios comprised
roughly half of total turnover and were instrumental in
producing the record result. premium rent
5-year average (2013-2017): 5-year average (2013-2017):
In 2017 the prime net yields on offices and logistics ca. €1.6bn ca. 316,000 m2 21.50 21.50
21.25 21.25 21.25
21.00
properties contracted slightly to 3.70 % and 4.70 % re-
spectively. The price of commercial buildings rose more
steeply. Prime yields thus sank from 3.60 to 3.20 %.
average rent
INVESTORS AND VENDORS
14.10
Foreign buyers furnished about 30 % of the capital. Ac- 13.70
12.70 12.70 12.40
counting for 30 % of the volume traded, the biggest single
group of buyers were “Other funds”. These are funds 0.8 1.3 1.9 1.8 2.3 2.0 280 260 290 440 310 300 10.80
that cannot be counted in the usual categories, such as 2013 2014 2015 2016 2017 2018 2013 2014 2015 2016 2017 2018 2012 2013 2014 2015 2016 2017
14 15
WWW.GERMANPROPERTYPARTNERS.DE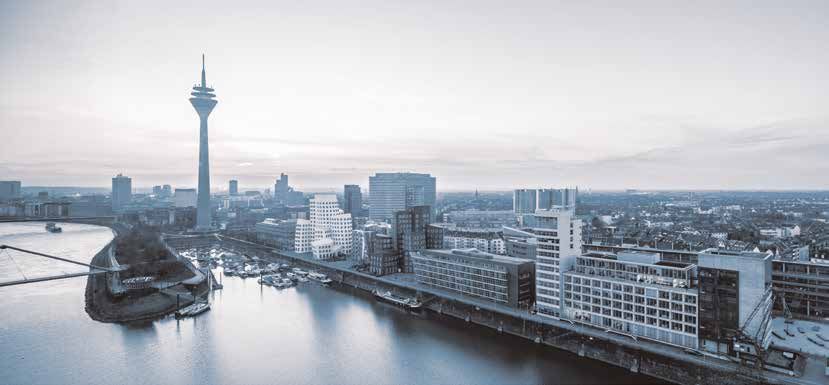
LOCAL EXPERTISE – ACROSS GERMANY MARKET SURVEY INVESTMENT/OFFICE LETTING 2017/Q1-4
OFFICE LETTING
FRANKFURT
In Frankfurt around 729,100 m² of office space was let, AVAILABLE AND VACANT SPACE
30 % more than in 2016. The result is comparable to The vacancy rate at the end of 2017 was 8.7 % and thus
volumes seen in the early 2000s. 1.8 percentage points below the prior year’s figure. Less
space stood empty in almost all the sub-markets. The
TAKE-UP OF SPACE biggest reduction was in the Banking District, where
Railway operator Deutsche Bahn AG was the biggest only half as much space stood empty as 12 months ago.
player on the Frankfurt office market in 2017, just as it Frankfurt North was the only sub-market to register an in-
had been in 2016. As of 2020 the firm will be occupying crease in empty space (+11 %). Following the low level of
some 52,600 m² in “The Brick” (Europa-Allee 70-76) and completions in 2017, when 81,100 m² came onto the market,
the neighbouring “Office Tower”, two building develop- the figure for 2018 will be around 138,200 m²; however, 73
ments in the Europaviertel district (City Periphery). The % of this space has already been pre-let. As of 2019 con-
next biggest transaction of the year was an agreement siderably more building projects will be completed.
by the central bank Deutsche Bundesbank to take some
44,400 m² in the “FBC” (Mainzer Landstrasse 46, Financial OUTLOOK
INVESTMENT District). Demand was greatest in the Central Business Demand will remain high in 2018. Considering that some
District (CBD), where 42 % of the total was registered. Be- clients are still searching for large premises, the annual
FRANKFURT cause Deutsche Bahn AG selected property in the City total take-up of space could be just under 600,000 m².
periphery district, this sub-market accounted for 17 %.
The volume of investment transactions in Frankfurt was share of 33 %. International investors took a 45 % share of Financial services comprised the biggest group of new
€6.7bn in 2017, just 1 % higher than in 2016. 40 % of this the total market, slightly less than the year before. This is tenants, taking a good quarter of the total space. Transport TOP 3 SUB-MARKETS (take-up of space / average rent)
total was traded in the 4th quarter. mainly attributable to the fact that two of the three most and construction & property firms shared second place.
expensive transactions featured buyers from Germany. Deutsche Bahn AG was by far the biggest of the transport FINANCIAL DISTRICT / 193,100 m² / € 31.00/m²/month
INVESTMENT PROPERTIES companies; the good result returned by property services CITY PERIPHERY / 127,300 m² / € 18.00/m²/month
The biggest sale of the year was the “Tower 185” (Frie- OUTLOOK is partly a result of a vast increase in demand by the pro- WESTEND / 60,400 m² / € 21.00/m²/month
drich-Ebert-Anlage 35-37) which Deka purchased for 2018 will continue to see unabated high demand but it will viders of co-working space, who secured over 40,000 m²
three open-ended funds, paying CA Immo, WPI Fund be increasingly difficult to find suitable investments. Even of space compared with 7,500 m² the year before. TOP 3 CONTRACTS
SCS-Fis, Fagas Asset GmbH and a pensions company if buyers tend to hold their properties for shorter periods,
some €775m. Another 4th-quarter sale was the “Japan investors are still resorting to B and C locations, high- RENTS 1. DEUTSCHE BAHN AG
Center” (Taunustor 2) for which GEG German Estate Group er-risk properties (core+, value-add) and other classes Several rental agreements for large amounts of space in “The Brick”/”Office-Tower”, Europa-Allee / ca. 52,600 m²
paid Commerz Real AG €280m. Finch Properties and a US of asset (mixed use buildings). International investors will top-quality properties in the CBD pushed the average rent 2. DEUTSCHE BUNDESBANK
fund sold the “MAC” (Unterschweinsstiege 2-14) by the continue to play an important part in 2018. up by 13 % to € 20.30/m²/month. The premium rent rose by “FBC”, Mainzer Landstrasse 46 / ca. 44,400 m²
airport for about €245m to CapitaLand and Lum Chang 3 % to € 39.75/m²/month. 3. HELABA LANDESBANK HESSEN-THÜRINGEN
Holdings from Singapore. As usual, the most popular “Mainblick³”, Kaiserleistrasse 26 / ca. 26,500 m²
assets were office properties, which accounted for 91 %
of the total investment trade. A disproportionately large
number of plots of land changed hands - but the over 20 Transaction volume Frankfurt Take-up of space Frankfurt Rents Frankfurt
transactions made up only 2 % of the total volume. Port-
folio purchases comprised 12 % of the total in 2017, com- (in €bn) (in 000s m2, incl. owner-occupiers) (net in €/m2/mth)
pared with 26 % the year before. This was largely due premium rent
to the big single transactions just described. Twice the 5-year average (2013-2017):
ca. €5.5bn 39.50 39.75
number of value-add properties were sold compared with 38.50
38.00 38.00
2016, - a result of the growing shortage of core properties. 5-year average (2013-2017):
With core properties still in great demand, however, the ca. 498,820 m2 35.00
prime net yield on office properties slid down to 3.3 %.
INVESTORS AND VENDORS
The biggest group of buyers consisted of open property
average rent
mutual funds and open-ended special property funds,
which together accounted for 30 % of the total volume.
20.30
However, project developers were involved in the largest 19.50
18.50 18.00 18.00
number of transactions (46). The first-named types of 3.4 5.0 5.7 6.5 6.7 6.5 448 368 389 561 729 575 17.50
funds were the most active sellers in the market with a 2013 2014 2015 2016 2017 2018 2013 2014 2015 2016 2017 2018 2012 2013 2014 2015 2016 2017
16 17
WWW.GERMANPROPERTYPARTNERS.DELOCAL EXPERTISE – ACROSS GERMANY MARKET SURVEY INVESTMENT/OFFICE LETTING 2017/Q1-4
OFFICE LETTING
STUTTGART
2017 closed with take-up of office space in Stuttgart at AVAILABLE AND VACANT SPACE
about 270,000 m². The result was thus some 38 % lower By the end of 2017 the vacancy rate had reached 2.1 %,
than the prior year’s. the lowest level for 16 years. The total space available at
short notice stood at a mere 167,000 m². Meanwhile the
TAKE-UP OF SPACE shortage of space has spread beyond the City and central
In what remained the biggest single transaction of 2017, area. Peripheral locations likewise have little to offer.
Daimler AG decided in the 1st quarter to have a new
building erected in Leinfelden-Echterdingen that will OUTLOOK
provide over 50,000 m² of space. The two biggest rental In the next two years no significant increase in the meagre
agreements were signed in the 3rd quarter. Daimler AG amount of space available in the City and central areas
took about 11,500 m² in the industrial estate Stuttgart Vai- is expected. Those who need large amounts of space will
hingen. And the law firm CMS Hasche Siegle took a lease increasingly look to the periphery, as the less central lo-
for some 11,300 m² in a new build under development on cations offer far more opportunities for new develop-
Rotebühlplatz, Stuttgart City district. Strongly influenced ments. This will lead to further price rises in such loca-
INVESTMENT by the Daimler AG development, Leinfelden-Echterdingen tions. Take-up of space in 2018 will probably be between
was the strongest sub-market with 61,300 m² of take-up. 230,000 m² and 250,000 m².
STUTTGART Around 52,000 m² of office space was let in the Vaihingen/
Möhringen sub-market. Stuttgart City followed with
Some €1.2bn were invested in commercial real estate opportunity funds with some 13 % each. Foreign investors 51,600 m² of space newly taken up. Once again industrial
in Stuttgart in 2017. The total fell far short of the prior made up some 50 % of the total. firms formed the biggest group of new office occupants TOP 3 SUB-MARKETS (take-up of space / average rent)
year’s - contracting by €600m or 34 %. in 2017.
OUTLOOK LEINENFELDEN-ECHTERDINGEN / 61,300 m² / €12.20/m²/month
INVESTMENT PROPERTIES It is expected that several outstanding transactions will RENTS VAIHINGEN/MÖHRINGEN / 52,000 m² / €12.30/m²/month
The following transactions accounted for some €320m be completed in the 1st half of 2018, so that the final tally The premium rent rose by 6 % year on year to €24.30/m²/ CITY / 51,600 m² / €18.50/m²/month
in total. The “Mercedes-Benz-Bank” (Siemensstrasse 7) for the year should be comparable with the total in 2017. month. The average rent for the entire city area including
was bought by the Baden-Würtemmberg Stiftung gGmbH, Leinfelden-Echterdingen was about €13.70/m²/month, TOP 3 CONTRACTS
a foundation, and the “City Plaza” (Rotebühlplatz) was likewise a year on year increase of some 6 %.
sold again. The building at Mittlerer Pfad 13-15 in Stutt- 1. DAIMLER AG (OWNER-OCCUPIER)
gart-Weilimdorf, also changed hands. Altogether, 65 Meisenweg / ca. 50,000 m²
transactions were completed in the past twelve months, 2. DAIMLER AG
about 50 % of them priced in the two or three-figure mil- Industriestrasse / ca. 11,500 m²
lions. Once again, the focus of investment activity - partly 3. CMS HASCHE SIEGLE
as a result of the three large sales noted in the foregoing Rotebühlplatz / ca. 11,300 m²
- lay on office properties, which accounted for around
78 % of the total volume of transactions. Other sectors
such as building sites, retail and hotel properties did not Transaction volume Stuttgart Take-up of space Stuttgart Rents Stuttgart
play a significant role this year. Portfolio trades accounted
for some 10 % (by value) of properties sold. The prime net (in €bn) (in 000s m2, incl. owner-occupiers) (net in €/m2/mth)
yield on office assets was 3.50 %, as it was in the prior premium rent
year. Research showed a prime net yield on commercial
buildings of 3.10 % and 4.50 % on logistics properties. 24.30
5-year average (2013-2017): 5-year average (2013-2017): 22.80 23.00
INVESTORS AND VENDORS ca. €1.3bn ca. 305,600 m2
21.50
Amounting to 24 % of the total, open-end/specialist funds
20.00 20.00
were the predominant buyers. Private investors/family of-
fices followed with a share of 13 % and insurance com-
panies with 11 %. Public administration and opportunity
average rent
funds each accounted for a share of some 10 %.
13.70
Sales were very evenly distributed. Private sellers/family 12.40 12.50 12.50
12.90
12.00
offices comprised about 14 % of the total traded, fol- 0.9 1.0 1.7 1.8 1.2 1.5 258 278 290 432 270 250
lowed by corporates, project developers/builders and 2013 2014 2015 2016 2017 2018 2013 2014 2015 2016 2017 2018 2012 2013 2014 2015 2016 2017
18 19
WWW.GERMANPROPERTYPARTNERS.DELOCAL EXPERTISE – ACROSS GERMANY MARKET SURVEY INVESTMENT/OFFICE LETTING 2017/Q1-4
OFFICE LETTING
MUNICH
Totalling a take-up of 878,000 m², the office market in AVAILABLE AND VACANT SPACE
Munich returned an above-average result. The year on The stock of empty space has once again shrunk dra-
year increase was about 15 %. Owner-occupiers ac- matically, so that by the end of the year it had fallen to
counted for some 108,000 m² of the total. Lettings alone 580,000 m², equivalent to a vacancy rate of 2.5 % for the
made up 770,600 m², which is still an exceptionally good city area and the environs. In some central locations there
result. is next to no empty space at all.
TAKE-UP OF SPACE OUTLOOK
As in the prior year, the biggest transaction of 2017 was Property in Munich will soon be fully let. This is due to the
one signed by BMW AG, this time as owner-occupier of great, unabated demand for office space and the per-
an extension to the research and innovation centre. In sistently low number of new builds in the pipeline. A no-
several sections, a total of 157,000 m² of office space is ticeable easing of the tense situation is not to be expected
to be built over the coming years in what is one of Europe’s before 2020.
biggest development projects. The 1st building section
INVESTMENT has been included in the statistics (74,000 m²) and is
scheduled for completion in 2019. Other large agreements
MUNICH included a lease signed by Deutsche Pfandbriefbank for
about 14,000 m² in the “Business Campus Garching” and
In 2017 the transaction volume on the market for invest- buying side of the equation. They were, however, not as the decision by Publicis Pixelpark GmbH to take some
ments in commercial properties totalled about €5.9bn in predominant as in past years. The same pattern was seen 13,000 m² in the “Atlas” development project on Rosen- TOP 3 SUB-MARKETS (take-up of space / average rent)
Munich. This translates into a 9 % decline compared with on the selling side of the market. heimer Strasse. Eight lets were recorded for more than
the excellent result of 2016. 13 transactions with price 10,000 m² of space each, with the result that in 2017 this PERIPHERY NORTH / 189,000 m² / €16.40/m²/month
tags of more than €100m together accounted for 47 % of OUTLOOK size sector registered the largest share of take-up. As far DOWNTOWN WEST / 110,000 m² / €18.70/m²/month
total turnover. No trend is discernible that would point to a weakening as the separate sub-markets are concerned, Periperhy DOWNTOWN / 105,000 m² / €28.20/m²/month
market in 2018. The first few months of the year are al- North easily led the field with a 21.5 % share of the market.
INVESTMENT PROPERTIES ready expected to produce a large volume of transactions, TOP 3 CONTRACTS
Apart from the period April to June, quarterly returns were because some big-ticket trades that were near com- RENTS
relatively equal. The 4th quarter lacked the agility of pre- pletion were postponed to the new year. Overall, the Ba- As the supply of space contracts, the average rent has risen 1. DEUTSCHE PFANDBRIEFBANK AG
vious years, and some of the larger transactions have been varian capital of Munich is expected to return a volume of appreciably year on year. Average rents increased by 9 % to Parkring 28-32 / ca. 14,000 m²
postponed until 2018. Some of the year’s biggest transac- between €5.0bn and €6.0bn on the market for commercial €16.90/m²/month. The premium rent, by contrast, softened 2. PUBLICIS PIXELPARK GMBH
tions were the 1st-quarter sale of the “Kap-West” devel- property investments. slightly to €35.00/m²/month. This was partly due to a shortage Rosenheimer Strasse 143a-d / ca. 13,000 m²
opment project (Friedenheimer Brücke) for which Allianz of expensive properties and partly to two agreements for 3. GEWOFAG GMBH
paid some €225m and the sale of the retail store “Karstadt large amounts of space at rents just below the premium rate. Gustav-Heinemann-Ring 109-115 / ca. 13,000 m²
am Hauptbahnhof”, for which Signa Holding paid RFR ap-
preciably more than €300m. Once again, consistently high
demand was registered for all types of asset in 2017 and Transaction volume Munich Take-up of space Munich Rents Munich
competition was correspondingly keen. As in the past, of-
fices were the most popular class of asset, accounting for (in €bn) (in 000s m2, incl. owner-occupiers) (net in €/m2/mth)
59 % of the market in 2017. Portfolio sales comprised less 5-year average (2013-2017):
than 10 % of the total in 2017. The prime net yield on office ca. 717,760 m2 premium rent
properties was further squeezed over the course of the
5-year average (2013-2017):
year and closed at 3.00 %. ca. €5.4bn 35.25 35.00
34.45
32.50 32.50
INVESTORS AND VENDORS 32.00
The Munich investment market was strongly charac-
terized by national investors, whose share of the total
traded was about 65 %. Correspondingly, around 35% of
average rent
the capital came from overseas. International investors
figured mainly in trades priced at more than €100m. In-
16.90
ternational investors were involved in about 50 % of these 14.90 15.10 14.60 15.00 15.50
big transactions. Once more, funds, above all open-end/ 4.2 5.0 5.5 6.5 5.9 5.5 608 584 755 764 878 700
specialist funds and pension funds, figured largely on the 2013 2014 2015 2016 2017 2018 2013 2014 2015 2016 2017 2018 2012 2013 2014 2015 2016 2017
20 21
WWW.GERMANPROPERTYPARTNERS.DELOKALEEXPERTISE
LOCAL KOMPETENZ– ACROSS
– DEUTSCHLANDWEIT
GERMANY MARKET SURVEY INVESTMENT/OFFICE LETTING 2017/Q1-4
GLOSSARY
GERMAN PROPERTY PARTNERS Across Germany Services
TAKE-UP OF SPACE TRANSACTION VOLUME » Hamburg » Real estate investments
Take-up of space is the total of all space let plus that sold to, or fin- The transaction volume is the sum of the purchase prices of all com- » Berlin » Commercial letting
ished by or for an owner-occupier during the period under review. The mercial property sold in Germany’s top 7 markets during the period » Düsseldorf » Corporate real estate management (CREM)
operative date for inclusion in the statistic is the date on which the under review. The date of signing determines when a transaction is » Cologne | Bonn » Research
lease or purchase agreement was signed. Lease renewals are not included in the statistics. Buy to let investments in residential prop- » Frankfurt » Banking and financing services
counted as take-up. Areas are stated on the basis of the guide for cal- erties are not included in the transaction volume. » Stuttgart » Equity financing of development projects
culating the rental area in commercial leases (MF/G). ASSET CLASS » Munich » Fund and asset management
PREMIUM RENT A property is allocated to an asset class according to the predominant » Real estate management
The premium rent relates to the top 3 % of the market for new lets way in which space is used (at least 75%) when the contract is signed. » Real estate valuation
(not counting owner-occupiers) during the 12 months just ended and INDIVIDUAL PROPERTIES AND PORTFOLIO TRANSACTIONS » Agriculture and forestry real estate
is stated as the average of such rents. An individual property transaction means the purchase of a building
AVERAGE RENT used for commercial purposes or of a piece of land for development.
The average rent is calculated by taking the individual rents agreed Portfolio transactions involve the purchase of at least two separate
in all leases signed over the past 12 months, weighting them by the properties in different locations.
amount of space rented and computing the mean value. Figures refer PRIME YIELDS
to nominal net rents ex services. The prime yield is the initial return attainable on a property that
VACANCIES has been let on normal market terms (tenants with good credit
We draw your attention to the fact that all statements made here are non-binding. Most of the information is based on third-party reports. The sole intention of this
Vacancies include all office space that is available to new tenants ratings), has top quality structure and fit-out and stands in one
market survey is to provide general information for our clients.
within three months. Sub-let space is counted as vacancy. of the very best locations. It is stated as the net initial yield in per
cent, i.e. the ratio between the annual rental income less non- Grossmann & Berger GmbH • Immobiliendienstleister • Bleichenbrücke 9 (Bleichenhof) • D-20354 Hamburg
apportionable ancillary costs and the gross purchase price (net pur- Phone: +49 (0)40 / 350 80 2 - 0 • Fax: +49 (0)40 / 350 80 2 - 36 • info@grossmann-berger.de • www.grossmann-berger.de
Managing directors: Holger Michaelis, Andreas Rehberg, Lars Seidel, Axel Steinbrinker
chase price plus land acquisition tax, notary’s fees and agency com-
Chairman of the Supervisory Board: Frank Brockmann • Entered in the commercial register: Hamburg B 25866
mission.) Supervisory authority: Borough Council Hamburg-Mitte, Department of Consumer Protection, Commerce and the Environment, Klosterwall 2, 20095 Hamburg
VAT identification number pursuant to Section 27a German Turnover Tax law: DE 118 556 939
SERVICES ANTEON Immobilien GmbH & Co. KG • Ernst-Schneider-Platz 1 • D-40212 Düsseldorf
Phone: +49 (0)211 / 58 58 89 - 0 • Fax: +49 (0)211 / 58 58 89 - 88 • immobilien@anteon.de
GERMAN PROPERTY PARTNERS Managing partners: Guido Nabben, Heiko Piekarski, Jens Reich, Dirk Schäfer, Marius Varro
Trading licence: a licence pursuant to Section 34 c of the German Industrial Code/GewO was granted with no restrictions by the Municipal Government of the State
Capital Düsseldorf, Department 32, Tel.: +49 (0)211 / 89 - 23 223. • ANTEON Immobilien GmbH & Co. KG • Registered office in Düsseldorf, entered in the Commer-
cial Register of Düsseldorf under HRA 19934 • General Partner ANTEON Verwaltungsgesellschaft mbH, registered office in Düsseldorf, entered in the Commercial
Register of Düsseldorf under HRB 58418
Naturally enough, when doing real estate business in Due to the banking background of two of our partners, we VAT identification number pursuant to Section 27a German Turnover Tax law: DE 259 465 200
Germany, you would like to work with a partner who can are familiar with the workings of the financial industry. We
Greif & Contzen Immobilien GmbH • Pferdmengesstrasse 42 • D-50968 Köln
provide you with expert professional support in all issues are also well placed to assist you in your search for office,
Phone: +49 (0)221 / 93 77 93 - 0 • Fax: +49 (0)221 / 93 77 93 - 77 • gpp@greif-contzen.de
relating to commercial property. retail, industrial, warehousing and logistics premises, as Managing directors: Mr Theodor J. Greif, Rainer Krauß
well as special uses, in the process bringing to bear our in- Amtsgericht (lower court) Registered in: Cologne, Company Register no. 11414
Supervisory authority: City of Cologne, Ordnungsamt, P.O. Box 103564, 50475 Köln
Our spectrum of services covers both real estate invest- depth local knowledge and outstanding regional contacts.
VAT identification number pursuant to Section 27a German Turnover Tax law: DE 123 055 006
ments and commercial letting. We are conversant with
all risk classes and types of property. For investors we In addition, we offer you corporate real estate man- blackolive advisors GmbH • Reuterweg 18 • D-60323 Frankfurt
Phone: +49 (0)69 / 907 44 87 - 0 • Fax +49 (0)69 / 907 44 87 - 10 • gpp@blackolive.de • www.blackolive.de
offer a Germany-wide service extending to the purchase agement, as well as research tailored to your specific
Managing directors: Oliver Schön, Rainer Hamacher
and sale of office, hotel, warehousing, logistics and retail project. Further services in the fields of finance, fund Trading licence: a licence pursuant to Section 34 c issued by the Ordnungsamt Frankfurt
real estate, as well as apartment buildings, either as in- management, asset management and administration Competent supervisory authority: Gewerbe- und Ordnungsamt Frankfurt, Kleyerstrasse 86, 60326 Frankfurt am Main
Commercial register and no. of entry: Registered in Frankfurt (Amtsgericht), HRB 93813
dividual properties or in portfolios. We are also ready to mean that you can obtain everything needed from us
VAT identification number pursuant to Section 27a German Turnover Tax law: DE 283 390 909
support you with preparation for development projects. to secure the effective long-term advancement of your
project. ELLWANGER & GEIGER Real Estate GmbH • Börsenplatz 1 • D-70174 Stuttgart
Phone: +49 (0)711 / 2148-300 • Fax +49 (0)711 / 2148-290 • gewerbeimmobilien@ellwanger-geiger.de • www.ellwanger-geiger.de
Managing directors: Mario Caroli, Björn Holzwarth
Competent supervisory authority: Amt für öffentliche Ordnung, Gewerbe- und Gaststättenbehörde, Eberhardstrasse 37, 70173 Stuttgart
Commercial register and no. of entry: Registered in Stuttgart (Amtsgericht) HRB 733293
Responsible under Section 55 par. 2 of the Interstate Broadcasting Agreement (RStV): Björn Holzwarth, managing director
VAT identification number pursuant to Section 27a German Turnover Tax law: DE 257 361 630
22 23
WWW.GERMANPROPERTYPARTNERS.DEYou can also read


